This guide explains how accounts receivable work, how they’re valued and managed, and how firms interpret them in decision-making. Background context covers the Receivables concept referenced by Investopedia, common risks like credit exposure and timing gaps, and the role of policies, documentation, and estimates such as allowances. The focus is practical and objective for analysts and operations leaders.
Accounts receivable are amounts customers owe for goods or services already delivered, and their quality can strongly influence liquidity, credit risk, and operating performance. In this guide, you’ll learn how the “Receivables” concept connects to the way Investopedia frames accounts receivable and related metrics, why valuation involves judgment, and what an expert approach looks like for tracking, collecting, and reporting outstanding invoices.
In financial reporting, accounts receivable is often treated as a current asset, but “current” does not automatically mean “collectible.” The core analytical question is not only how much is outstanding, but how likely it is to be collected within reasonable credit terms and under realistic recovery scenarios. That is where receivables management becomes both a finance function and an operational discipline.
When professionals discuss Receivables Investopedia and related terminology, they typically mean a set of widely used ideas: receivables arise from credit sales; they require tracking by customer and aging bucket; and they must be evaluated for collectability through an allowance (often linked to expected credit losses under modern accounting standards). Although terminology varies by jurisdiction and accounting framework, the analytical logic remains consistent: measure outstanding balances, assess credit risk, estimate losses, and ensure internal controls support the numbers.
Accounts receivable directly affects cash conversion. A company that records revenue but doesn’t successfully collect cash may face working-capital pressure, even if its top-line performance looks strong. Analysts therefore treat receivables as a bridge between reported revenue and real cash flows.
At an expert level, receivables analysis usually includes three intertwined lenses:
These themes align with the general educational framing you would find in materials like Receivables Investopedia: receivables represent claims to cash, and the key risk is that not all claims will convert to cash at the expected amounts and dates.
It’s also worth emphasizing that receivables are often “the first place cash disappears.” Investors may focus on revenue growth, margins, and EPS, but receivables quality can quietly undermine those numbers. Even profitable companies can suffer liquidity stress if collections lag, disputes linger, or credit policies loosen. In some sectors—such as staffing, construction, wholesale distribution, B2B software with extended terms, or complex project services—receivables are large enough to meaningfully determine whether the business funds itself through operations or needs outside financing.
In practice, receivables management is not just an accounting exercise. It’s a system that includes sales terms, contracting language, invoicing accuracy, delivery/acceptance verification, dispute resolution, collection staffing, customer communications, and the data pipelines that connect invoices to the general ledger. When the system is well designed, receivables behave more like a predictable cash stream. When it’s poorly designed, receivables become an unpredictable drag on liquidity.
In very mainstream interpretations, “receivables” refers to amounts due from customers for delivered goods or services. Depending on the business model, the category can include:
For very operating companies, trade receivables are the primary driver. From an analytical standpoint, you want to understand both the gross receivables and the allowance for expected credit losses (or a comparable valuation approach under the applicable accounting standard).
Even if your balance sheet aggregates numbers, top practice is to disaggregate by customer, contract, dispute status, and aging. The reason is simple: collectability is rarely uniform across all outstanding invoices.
For example, a company might have $50 million of gross trade receivables. But if $20 million belongs to one large customer that recently issued a formal dispute, that portion may be meaningfully less collectible than the remaining $30 million spread across stable customers with consistent payment behavior. Aggregation can obscure this. That’s why receivables reporting inside the organization often looks more detailed than what appears in external financial statements. Internally, finance teams typically maintain subledgers that track invoice-level details, customer master data, contract terms, and collection status.
Also note that classification matters. Some arrangements may look like receivables but are accounted for differently due to transfer of goods/services timing, variable consideration, or contract modifications. Depending on the accounting standard and the specific contract terms, some “amounts billed” might not fully meet the criteria for revenue recognition, or they may represent contract assets or liabilities rather than trade receivables. The borderline cases are where judgment increases—so it’s crucial that the accounting policy maps accurately to the operational reality.
Receivables collection is not only a matter of sending invoices. It depends on documentation, customer onboarding, clear credit terms, performance acceptance (for some industries), and dispute resolution workflows. A well-run receivables system ensures that what was billed is actually what was delivered and accepted—or that disputes are identified and handled promptly.
In many organizations, the operational stages of receivables conversion look like this:
This operational process is where the “conceptual” definition of receivables becomes measurable. When the process fails—such as invoice errors, unclear terms, or slow dispute handling—balances can age faster than expected, raising the risk that collections will not occur on schedule or at full value.
Consider a common scenario: a company provides services, and billing depends on “acceptance.” If acceptance documentation is delayed, the invoice may still be issued under a billing rule, but the customer may contest it later. If disputes aren’t processed quickly, they can remain “in limbo,” continuing to age. In those situations, the organization may still show receivables on the books, yet the cash conversion timeline shifts materially. From an expert standpoint, the accounting allowance and management actions should reflect that reality.
Another scenario: incorrect invoice amounts due to pricing errors, billing against the wrong contract version, or shipment quantity discrepancies. These issues can cause payment holds, late payments, or partial payments. Many companies treat these as operational mistakes. From a risk perspective, they’re also measurement issues because they increase the probability that receivables will not convert at full value. Expert receivables teams often build preventive controls around invoice accuracy and integrate exception reporting so that billing problems are detected early.
A key expert insight is that the valuation of accounts receivable is rarely a purely mechanical exercise. Under modern accounting guidance, the allowance approach is often based on expected credit losses rather than waiting for losses to occur.
Professional risk management typically applies the following principles:
In other words, receivables are valued as collectible assets, not as guarantees. The allowance is a disciplined estimate that reflects both statistical pattern and business judgment.
It’s helpful to break down what “expected credit losses” means in practice. The allowance attempts to estimate how much of gross receivables will not be collected. But instead of waiting until a customer fails to pay, the allowance reflects the likelihood of nonpayment based on multiple signals:
Under expected credit loss models, organizations must also consider whether they can reasonably and supportably apply forward-looking assumptions. The phrase “supportable” is critical. A model that relies on arbitrary or overly optimistic macroeconomic forecasts may fail internal governance and potentially face scrutiny in an audit.
From a data perspective, the quality of receivables valuation depends on having consistent aging calculation, accurate invoice-level information, and reliable history on collections and write-offs. If “write-offs” are recorded inconsistently or if recoveries are not tracked properly, the historical inputs will be weak. That can distort the entire allowance estimate. In mature finance organizations, valuation methodology is documented, periodically calibrated, and reviewed for reasonableness. Sensitivity analysis and governance approvals are common practices.
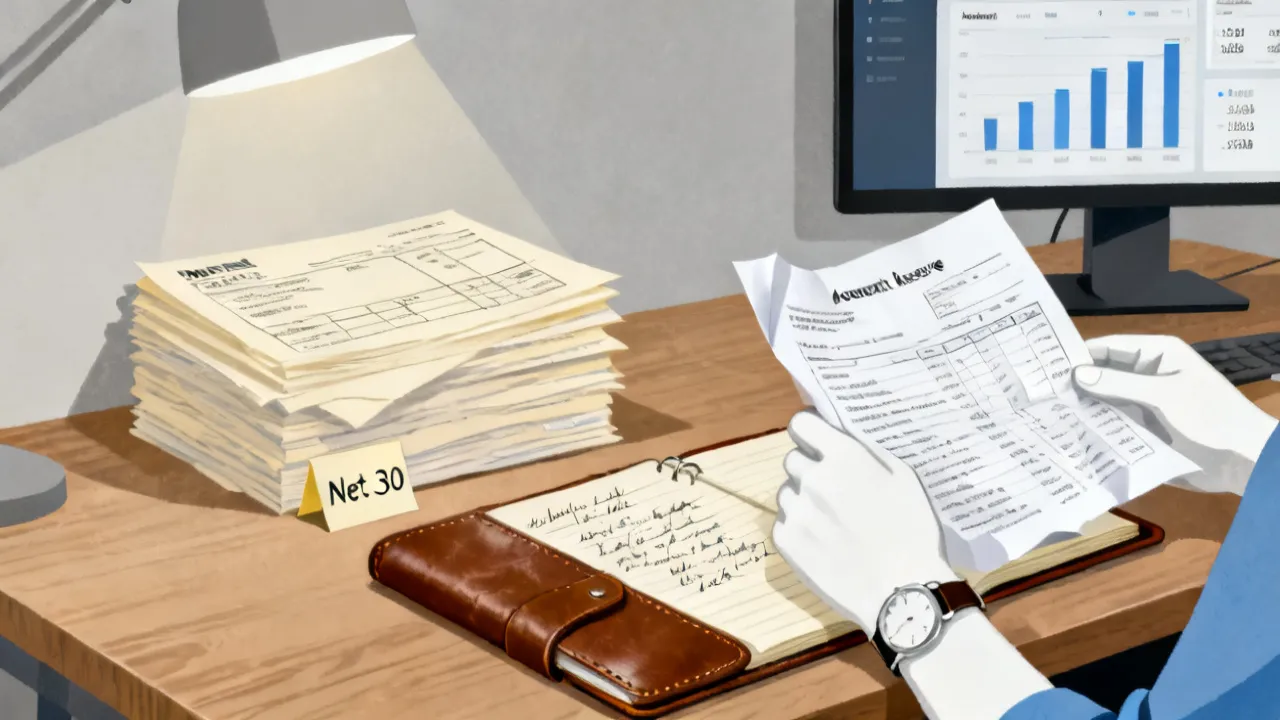
Credit terms are the “contractual timeline” for converting receivables to cash. Terms like Net 30 or Net 45 can be standard, but what matters is adherence and consistency. If a company’s collection period expands gradually over time, it can indicate either improving sales quality (less likely) or deteriorating collection effectiveness (more plausible).
Concentration risk is another practical issue. If a large portion of receivables sits with a small number of customers, a single dispute, bankruptcy, or operational disruption can materially affect liquidity. Expert teams therefore monitor:
These are not abstract considerations. They shape whether receivables should be considered stable, partially impaired, or at higher risk.
Concentration risk is not only about whether customers are “good” or “bad.” It’s also about whether the company can manage the operational consequences if a major customer stops paying. For instance, if a business depends on one distributor or one anchor tenant, and that party’s payment slows, cash flow can be disrupted quickly. The company may respond by increasing credit limits or speeding up billing in a way that inadvertently adds more risk. A disciplined receivables strategy connects credit policy, collection practices, and risk appetite.
Credit terms also tie into customer behavior. If contract language permits extended payment terms or if invoicing occurs late due to internal approval cycles, the effective collection timeline can differ substantially from the published Net terms. Analysts and internal teams should therefore examine both contractual terms and actual payment timelines. This is where receivables management becomes operational: finance teams and sales operations need alignment on when invoices can be issued, what documentation supports billing, and how quickly disputes are escalated.
While companies report financial statements, analysts often look at operational indicators that connect to receivables quality. Commonly used metrics include:
These metrics are helpful because they reveal whether a firm’s receivables management process is keeping pace with business growth and credit risk. However, they must be interpreted carefully: changes in invoicing practices, revenue recognition timing, seasonality, and contract structure can all distort comparisons across periods.
To understand DSO correctly, it helps to know what goes into it and how it can be affected. Typically, DSO uses average accounts receivable and relates it to revenue per day or cost of sales depending on the method. If the company changes billing frequency, moves from upfront to milestone billing, or changes how it recognizes revenue, DSO can move for reasons that don’t necessarily indicate deterioration. Similarly, seasonality can cause receivables to rise at quarter-end due to invoicing patterns, creating a “look bad” DSO even if cash conversion is stable.
A mature analysis therefore goes beyond a single DSO figure. Expert teams often compare DSO:
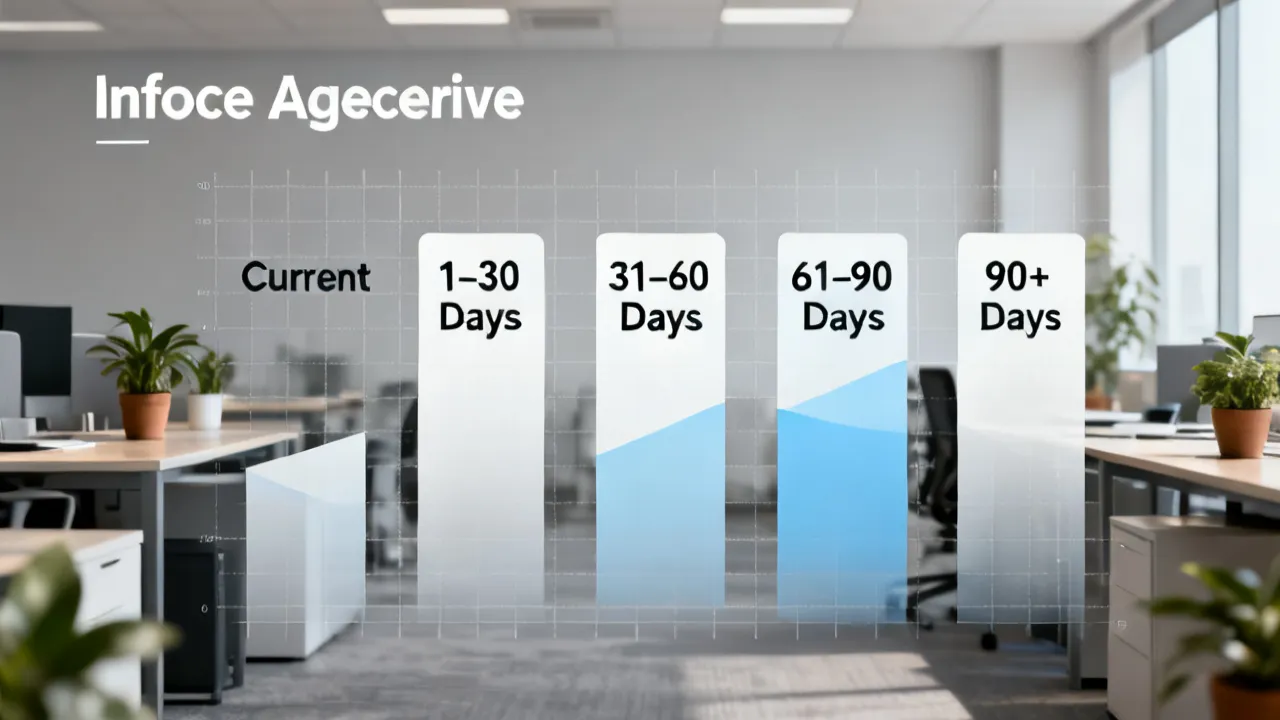
Aging distribution analysis is particularly powerful. If the share of past-due receivables increases—especially in severe buckets like 90+ or 120+ days—that can indicate collection challenges or disputes. But the “why” matters again. A temporary increase in past-due balances might reflect a short-term operational backlog in collections. In contrast, a persistent aging migration with rising disputes and increasing allowance suggests deeper issues with credit quality or process breakdowns.
From an industry-expert standpoint, the very preventable receivables problems tend to be procedural rather than conceptual. If invoices are inaccurate, customer master data is incomplete, or subledger-to-ledger reconciliation is weak, then allowance estimates will either be unsupported or inconsistent—both of which weaken reporting credibility.
Strong internal controls around receivables typically include:
When teams apply these controls, “Receivables Investopedia” concepts translate into reliable data: receivables are not just reported—they are supportable.
Internal controls are also central to preventing revenue “leakage” or mismatches between what was billed and what was actually delivered. For example, if a company has a robust delivery tracking system, it can ensure that invoices are issued only when delivery milestones are met. This reduces the likelihood that customers dispute invoices for reasons that are valid. Conversely, if invoices are issued without sufficient documentation, disputes become more frequent and collections slow down. That increases the probability that receivables will become impaired.
Data quality is often underestimated. A receivables aging schedule depends on invoice dates and posting dates. If invoices are dated inconsistently—or if the system backdates or forwards invoice posting—aging analysis can misclassify receivables into incorrect buckets. This can distort the allowance estimate and undermine monitoring metrics like DSO. Expert finance functions treat the receivables data pipeline as an auditable process with controls, exception handling, and periodic reconciliation checks.
Furthermore, internal controls should define clear ownership. Who is responsible for resolving disputes? Who approves credit limit adjustments? Who reviews allowance methodology? When responsibilities are unclear, receivables processes can degrade even if the tools are advanced. In many organizations, receivables performance improves significantly after establishing clear workflows and governance: the right team resolves the right problem at the right time.
A common misconception is that strong revenue growth automatically implies strong cash conversion. In reality, receivables are influenced by how quickly customers pay, not only how quickly revenue is recognized. Contract structures can also matter: for example, milestone-based billing can create temporary spikes in receivables that later normalize.
Expert analysis therefore separates:
Only by linking both can you judge whether receivables are becoming an operational strength or a latent liquidity risk.
For instance, a company might report higher revenue due to contract modifications or improved performance obligations. But if billing lags behind cash collection—or if collections slow due to disputes—cash flow from operations may not improve as expected. Investors who focus only on revenue growth could misread the financial health of the business.
Conversely, a company could have stable or declining revenue but improving collections due to better credit discipline, proactive dispute handling, or a shift toward customers who pay faster. In that case, receivables might shrink even if revenue doesn’t accelerate. This distinction helps analysts identify whether the business is improving its working-capital engine independent of sales trends.
It’s also valuable to consider revenue concentration and contract terms. If revenue is highly concentrated among long-term contracts with retention clauses or acceptance thresholds, receivables patterns will naturally show variability. A well-run company will anticipate this variability in its receivables allowance and in liquidity forecasting. Poorly run companies may let receivables drift without adjusting credit exposure or allowance methodology to reflect contractual realities.
Investors and lenders often pay attention to signals that receivables may be deteriorating or being measured optimistically. Common red flags include:
These are not accusations; they’re analytical prompts. A high DSO could be driven by new customer onboarding or extended contractual terms—so expert teams always confirm the “why” behind the numbers.
It can help to think of red flags in categories: speed, quality, and measurement. Speed red flags include DSO increases and rising past-due counts. Quality red flags include concentration to weaker customers and recurring disputes. Measurement red flags include allowance coverage ratios that decline even as past-due balances rise, or reconciliation weaknesses that make it hard to verify receivables aging.
Another red flag is “unexplained” receivables growth relative to revenue. If receivables rise faster than revenue, the company may be extending payment terms, loosening credit, increasing average invoice size for riskier customers, or encountering operational breakdowns in billing and dispute resolution. Expert analysis seeks to connect the change to documented business decisions and operational events.
Finally, pay attention to the timing of collections and quarter-end effects. Sometimes receivables peak at quarter-end due to end-of-quarter billing cycles, seasonal purchasing behavior, or contract timing. That can distort trend comparisons. A disciplined team will normalize for seasonality and use cash collection data over longer windows (for example, rolling 90-day or 180-day periods) instead of relying solely on quarter-end snapshots.
Below is a structured comparison and workflow supplement for interpreting accounts receivable concepts in a disciplined way. This section is designed to support decision-making rather than replace accounting judgment.
| Topic | What It Means in Practice | How to Assess It |
|---|---|---|
| Gross Receivables | The total invoice balances due from customers before valuation allowance | Review invoice population, customer concentration, and aging distribution |
| Allowance for Credit Losses | Estimated uncollectible amounts based on expected credit loss logic (where applicable) | Validate model inputs, use documented assumptions, compare to recent loss experience |
| DSO / Collection Speed | A proxy for how quickly receivables convert into cash | Compare DSO trend over time and reconcile to changes in contract terms |
| Aging Buckets | Classification of receivables by how long they have been outstanding | Examine current vs. past-due mix and whether past-due items are actively managed |
| Dispute Status | Balances related to disagreements over delivery, service, pricing, or terms | Confirm dispute ownership, resolution timetables, and accounting treatment |
To reach an Investopedia-level understanding, it helps to treat accounts receivable as a managed risk portfolio. Even though receivables are booked as a financial statement line item, internally they function more like a set of individual credit exposures tied to customers and contracts. This perspective changes how you interpret “good” versus “bad” receivables.
In a credit portfolio mindset, collectability is not binary (paid vs. not paid). It’s probabilistic. An invoice that is only 15 days past due might have a high likelihood of payment soon. An invoice that is 180 days past due might still be partially collectible through negotiations, legal actions, or recoveries—especially if the customer disputes a specific portion rather than all charges. The allowance aims to reflect this probability distribution in a systematic way.
That’s why expert teams pay attention to several “micro” signals:
Investopedia-style finance education often frames accounts receivable as “claims to cash.” The portfolio mindset adds the next step: claims to cash vary in likelihood and timing. Your models and management processes should reflect that variability.
While the accounting standard sets the overarching requirement to estimate credit losses, allowance methodologies can vary widely in implementation. Common approaches include using aging-based loss rates, customer segmentation, and scenario adjustments. Each has strengths and weaknesses.
Aging-based loss rates use historical default or write-off experience by aging bucket (for example, 0-30, 31-60, 61-90, and 91+). This is often a reasonable starting point because aging is correlated with payment behavior. However, it can break down if the customer base changes significantly, if credit policies tighten or loosen, or if collection processes improve. If the company’s operational environment shifts, historical patterns may no longer be predictive.
Segmentation models refine the methodology by grouping customers (or invoices) into risk categories. For example, customers might be segmented by internal credit rating bands, industry type, or payment history. Segmentation can improve accuracy because different customer groups may have different loss patterns. The pitfall is data quality: if segmentation categories are outdated or if customer risk indicators are not updated regularly, the segmentation may give a false sense of precision.
Forward-looking scenario adjustments incorporate macroeconomic or other forecasts. This can improve relevance if applied carefully. The pitfall is overfitting or subjective optimism. Experts typically look for a balance between model discipline and business judgment, and they document why particular scenarios are included, which variables are used, and how weighting decisions were made.
Practical governance pitfalls include:
A strong allowance process makes it possible to answer basic questions reliably: Which invoices are included? Which customers are segmented? Which assumptions change each period and why? How is the allowance calibrated against actual losses and recoveries?
Disputes can either be a temporary operational problem or a sign of deeper issues. Their impact is not only about whether cash is delayed; disputes can change the expected amount that ultimately gets paid. In many industries, disputes are often over billing accuracy, service performance, delivery terms, or contractual interpretation. If disputes are frequent and unresolved, they can inflate receivables and distort allowance estimation.
Expert receivables teams treat disputes as a separate “dimension” rather than blending them invisibly into general aging. That means tracking:
Why does this matter? Because disputes often have different collection patterns than straightforward late payments. A customer who disputes an invoice may keep paying other invoices on time, or may withhold all payments until a specific dispute is resolved. The cash collection behavior can differ significantly. Therefore, a “pure aging bucket” approach may be insufficient. Expert allowance models often adjust for dispute status by reducing expected recovery rates for disputed invoices or by applying a separate treatment logic.
Operationally, dispute management affects customer experience. Poor communication or slow resolution can lead to escalations that prolong the dispute. From a finance perspective, that prolongation is directly connected to liquidity risk and allowance risk. So dispute management isn’t only a legal or customer service function—it’s also a working capital strategy.
Accounts receivable does not exist in a vacuum. It’s the output of credit policy decisions. If a company extends credit limits too generously, approves customers with weak payment history, or fails to monitor credit deterioration, receivables risk increases. But the feedback loop is bidirectional: rising receivables risk can also cause business leaders to push back, attempt to accelerate billing, or introduce new credit terms that may affect customer relationships.
An expert approach recognizes that credit policy should be dynamic and connected to operational realities:
In addition, sales incentives can influence receivables quality. If sales teams are measured primarily on revenue booked without regard to collections performance, they may accept deals that create risky receivables. Modern organizations sometimes incorporate collections metrics into sales compensation or at least require finance approval for credit terms outside standard policy. This aligns incentives and reduces the likelihood of receivables ballooning due to poor credit underwriting.
Accounts receivable analysis is particularly vulnerable to timing distortions. Many businesses invoice more heavily at month-end or quarter-end. Others have seasonal demand patterns that lead customers to purchase more at certain times but delay payments due to internal procurement cycles. This means that receivables snapshots at period end can exaggerate underlying trends.
Expert analysts address this by using:
They also interpret changes in receivables in the context of business events. For example, if a company recently shifted to a new billing system, DSO might temporarily increase due to system cutovers. Or if a company changed its contract structure to bill in milestones, receivables may spike when milestones are achieved, even if the customers pay normally once invoices are issued. Without context, those changes can lead to misleading conclusions.
In other words, receivables analysis is as much about understanding the business as it is about calculating ratios.
It’s easy to treat receivables as a problem when they grow. But high-performing companies use receivables as a working capital engine. “Good” receivables typically means:
In organizations with strong receivables performance, collections are predictable enough to support reliable cash forecasting. That predictability reduces reliance on external financing, improves liquidity resilience, and supports operational stability.
Good receivables performance is also a sign of effective cross-functional collaboration. Finance, operations, customer service, and sales all contribute. For example, operations teams help ensure that delivery and acceptance documentation is ready for billing. Sales operations can clarify contract terms and credit approval logic. Customer service can handle invoice questions quickly to prevent disputes from turning into payment holds. When these functions align, receivables becomes a controlled system rather than a reactive firefighting process.
Beyond internal metrics, external stakeholders often focus on whether receivables represent a true source of liquidity. Lenders may require enhanced monitoring due to collateral considerations. Investors may examine whether receivables quality is deteriorating through trends in DSO, aging, allowances, and cash flow from operations.
Common questions stakeholders ask include:
Expert analysis links answers to evidence. For example, if allowances increase while aging worsens, that can be a healthy sign of measurement responsiveness. But if allowances decrease while past due balances rise, that can indicate underestimation of credit losses or delays in updating assumptions. Similarly, if DSO rises but the company’s dispute pipeline shows quick resolution times and customers are stable, the explanation could be a temporary billing shift rather than deeper credit deterioration.
If you want a concise expert bottom line, it’s this: accounts receivable should be managed as a cash conversion process, not only as an accounting line item. The “Receivables Investopedia” perspective is very useful when it reminds you that receivables quality depends on timing, evidence, credit risk, and valuation discipline.
For finance leaders, that means strengthening governance over allowances and ensuring the data behind receivables is reconciled and supportable. It also means integrating receivables performance analytics into planning and forecasting so that liquidity expectations match operational reality. Finance should partner with operations and sales to ensure that billing practices, contract terms, and dispute handling feed into the receivables model and into the internal control system.
For operations leaders, it means improving invoice accuracy, clarifying acceptance and delivery expectations, and reducing dispute cycle times. Operations-driven fixes are often some of the highest ROI actions in working capital management. When invoices are accurate and delivered/accepted properly, disputes decline and collections improve without needing overly aggressive collection tactics.
For risk teams, it means monitoring concentration and credit deterioration signals early—before they become write-offs. Risk management should include not only reviewing credit limits and customer ratings but also monitoring early warning indicators like rising dispute rates, growing aging buckets, and changes in payment behavior. When risk signals are detected early, the company can take action: adjust terms, tighten credit approval, prioritize collections, or restructure contracts.
When these groups align, receivables become predictable, reporting becomes credible, and liquidity planning becomes more reliable. That alignment is the difference between simply recording receivables and actually translating them into a controlled working-capital engine.
Accounts receivable are amounts owed by customers for products or services that have been delivered but not yet paid. They are recorded as assets because they represent claims to future cash, subject to collectability assessment.
It typically emphasizes the practical relationship between credit sales, invoice timing, and the need for valuation through allowances or credit loss estimates. It also highlights why receivables risk is different from other assets: collectability depends on customer behavior and contract specifics.
Because some customers may delay payment, dispute invoices, or fail to pay. The allowance represents an estimate of expected credit losses so that reported receivables are not overstated.
They are usually classified as current assets because very customer invoices are expected to be collected within a normal operating cycle. However, the classification can vary depending on contract terms and expected collection timing.
Common causes include slower customer payments, changes in credit policies, a shift toward customers with longer payment terms, invoicing delays, or dispute backlogs. Analysts should validate which driver applies rather than assuming a single explanation.
They should record disputes consistently, track them with clear ownership, and reassess collectability. Resolution timelines and evidence should be documented so that allowance updates reflect the true expected outcome.
Gross receivables are total invoice balances. Net receivables are gross balances minus the allowance for credit losses, reflecting expected uncollectible amounts.
Teams should rely on applicable accounting standards and regulators’ interpretations, such as IFRS 9 (IFRS jurisdictions) or ASC 326 (U.S. GAAP). Educational summaries can support understanding, but policy implementation should follow authoritative guidance.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Digio Livelo Explained: Rewards Integration and Use
This guide explains how Digio Livelo works for earning and using rewards, what to verify before you start, and how to choose sensible redemption options. “Digio Livelo” refers to a rewards relationship between Digio’s digital banking/payment experience and Livelo’s loyalty ecosystem. Practically, it’s about matching your spending or engagement to reward accrual, then selecting redemptions that fit your goals.
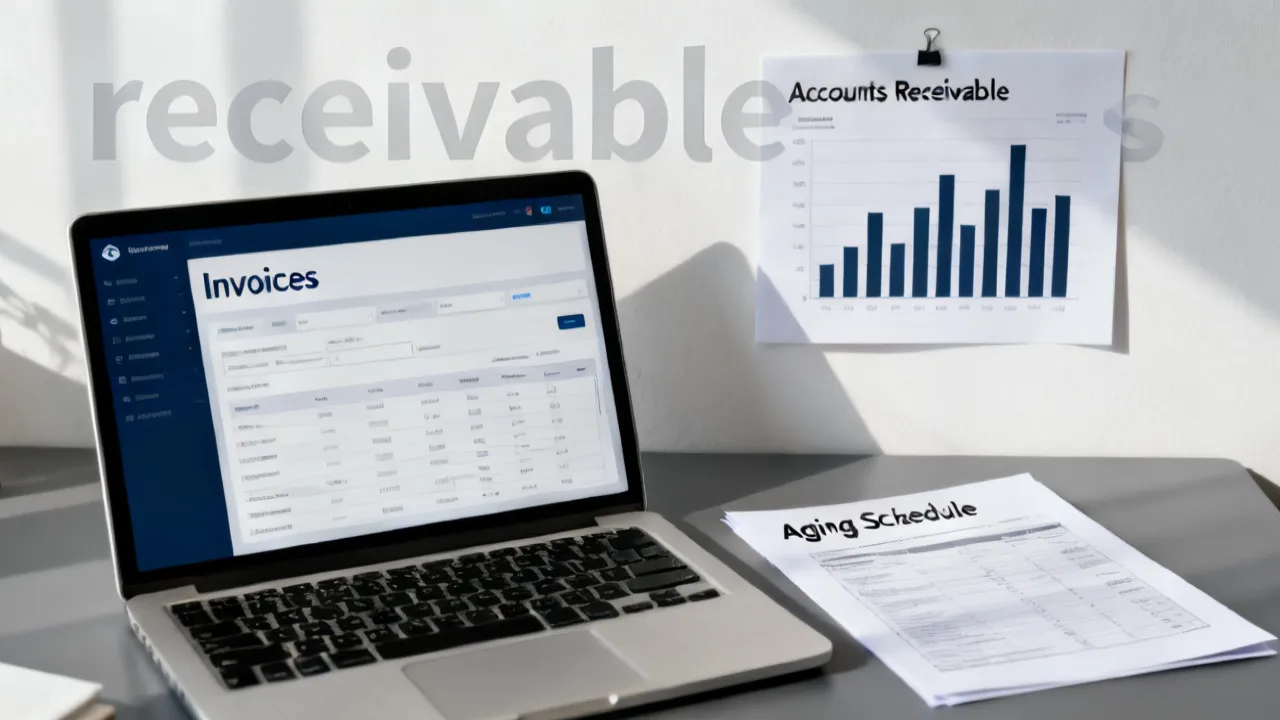
Receivables Explained with Investopedia Insights and Risk Controls
This guide explains receivables fundamentals and how to manage them with evidence-based controls aligned with Investopedia-style definitions. It provides objective background on what “receivables” means in accounting, why aging matters, and how businesses assess credit exposure, collect payments, and protect cash flow without assumptions.
Accounts Receivable Guide: Investopedia Insights for Clarity
This guide explains how accounts receivable work, how they’re valued and managed, and how firms interpret them in decision-making. Background context covers the Receivables concept referenced by Investopedia, common risks like credit exposure and timing gaps, and the role of policies, documentation, and estimates such as allowances. The focus is practical and objective for analysts and operations leaders.
Receivables: How to Interpret and Manage Credit Risk
Receivables are the lifeblood of many businesses because they represent money owed by customers. This guide explains how receivables are analyzed, why payment terms matter, and how “Receivables Investopedia” concepts help standardize thinking about liquidity and credit risk. Objective background follows, centered on accounting definitions, risk signals, and common management practices.
Bambora Payfac: A Practical Guide for Merchants
Bambora Payfac helps merchants structure card and digital payments through a streamlined payment facilitation model. This objective guide explains what payment facilitation is, how onboarding and compliance typically work, and what merchants should evaluate—pricing transparency, risk controls, settlement timing, and operational responsibilities—so you can choose an approach that fits your business needs.
Understanding Accounts Receivable and Investopedia Insights
This guide explains how accounts receivable work, how to interpret “Receivables” definitions (including perspectives aligned with Investopedia), and how to manage invoice collections with disciplined policies. Accounts receivable refers to money customers owe from credit sales. It sits on the balance sheet as a current asset, and its quality affects cash flow, risk, and working-capital decisions.
