This guide explains how to access and use Runpayroll.adp.com for payroll entry, approvals, and ongoing administration. It reviews what the ADP payroll workflow typically means for employers, how authentication and permissions shape day-to-day tasks, and why clean payroll data matters. It also includes a practical comparison table, requirements checklist, and expert FAQs to support informed setup decisions.
When organizations manage payroll through Runpayroll.adp.com, the very critical step is ensuring the correct user access and a consistent workflow for data entry, approvals, and reporting. In practical terms, a payroll portal isn’t just a place to “log in”—it’s the operational hub where payroll teams reduce errors, preserve audit trails, and coordinate approvals before pay runs are finalized. From an industry-expert perspective, the difference between a smooth cycle and last-minute fixes is usually not the portal itself, but the combination of access controls, role clarity, and disciplined data governance.
In many organizations, payroll is treated as a repeating monthly—or biweekly—event. Yet from a controls and risk perspective, payroll should be viewed as a controlled process that must remain accurate even when people are absent, systems change, and inputs arrive at different times. A portal like Runpayroll.adp.com supports that goal only when permissions are aligned to responsibilities and when the organization uses the portal in a predictable, repeatable way.
Even when teams “know” who does what, permission drift commonly occurs over time: a user changes roles, contractors are added for short periods, department responsibilities shift, or the organization expands into new states or pay frequencies. If permissions and workflows are not periodically reviewed, it’s possible for users to gain the ability to change data they shouldn’t, or for critical approvers to lose access right when they’re needed most. Either scenario can lead to delayed approvals, failed payroll runs, rework, or compliance issues.
That is why the key takeaway is not simply “use Runpayroll.adp.com,” but “use Runpayroll.adp.com with the right permissions and a consistent workflow.” The portal becomes reliable when it is embedded into internal SOPs (standard operating procedures), and when users understand the boundaries of their roles—what they can prepare, what they can review, what they can approve, and what they can only view.
Modern payroll processing is time-sensitive and compliance-sensitive. Employers typically need a workflow that supports:
Because Runpayroll.adp.com sits inside that broader operational framework, the portal’s value is top understood as part of an end-to-end system: inputs (employee and payroll data) flow into calculations and checks; then approvals confirm readiness; finally, pay-related outputs are produced for employees and downstream accounting workflows.
To make that real, consider the life of a payroll cycle. It usually begins well before processing day—when teams gather information such as time entries, compensation changes, one-time adjustments, benefit deductions, retroactive corrections, and special payroll items. Then, during the portal’s operational window, those inputs are uploaded, confirmed, or manually adjusted. Once the payroll run approaches, the workflow shifts into verification: exception checks, preview reviews, total validations, and approvals.
If the portal is not used as the operational source of truth, or if permissions are inconsistent, the organization can end up in a situation where different teams rely on different copies of data (or different statuses of records). That fragmentation may not be obvious until the payroll preview appears incorrect—or until accounting reconciliations do not match.
In other words, Runpayroll.adp.com matters because it helps connect the operational steps of payroll: preparation, validation, approval, processing, and reconciliation. When the portal is configured and governed properly, it supports auditability and reduces the “tribal knowledge” dependence that often causes delays when personnel change.
From a risk management standpoint, payroll is among the most visible internal processes—errors affect employees’ pay directly. Employees typically notice quickly when their pay is incorrect, delayed, or missing items like deductions or bonuses. That visibility makes it essential that the portal workflow reduces the chances of unreviewed changes, misapplied earning codes, or incorrect approvals.
Before teams rely on Runpayroll.adp.com operationally, expert payroll administrators typically validate four foundational areas:
Payroll portals are designed with security in mind. Ensure that each user role (e.g., preparer vs. approver vs. view-only) aligns with their responsibilities. If permissions are overly broad, controls weaken. If permissions are too narrow, staff may bypass process steps or delay approvals—both of which increase operational risk.
In expert practice, “access model” is not a one-time configuration. It is a living control. Organizations should plan for:
Authentication readiness also matters. Even if permissions are correct, portal access can fail if authentication methods, account status, or security policies are not aligned. For example, organizations may require multi-factor authentication (MFA) or follow particular login policies. If those requirements are new or inconsistently applied, payroll operations can suffer when critical users can’t access the portal during a processing window.
Payroll outcomes depend on the accuracy and timeliness of underlying information—such as earnings components, pay schedules, deductions, and employee eligibility rules. In practice, teams should establish where the “system of record” lives for each data type and define how changes propagate into payroll.
Data governance is especially important in payroll because many errors are not “calculation errors,” but “input errors.” A payroll calculation might be correct given the data it receives—but if the pay rate is wrong, if the effective date is incorrect, or if a deduction isn’t configured properly, the result is incorrect pay. Those mistakes can then require retroactive adjustments and create reconciliation headaches.
Expert teams often define ownership using a “data category” approach. For instance:
Data governance also includes defining what “effective date” means in your internal process. Payroll often applies rules depending on whether changes are effective for the current pay period or later periods. If a manager updates a change with an effective date that conflicts with internal scheduling, it can lead to partial or missing adjustments.
Experienced teams don’t treat approvals as a formality. They run a checklist: validate updates, confirm exceptions, check totals, and review status indicators before finalization. This is especially important when payroll cycles are tight or when multiple departments submit inputs.
In well-run environments, approvals are associated with specific decision points. For example:
These decision points matter because payroll often includes gray areas—late changes, retro pay, or exceptions caused by special circumstances. Approvals create a record of who made the decision and why, which reduces uncertainty later during audits or employee pay inquiries.
Payroll systems operate on defined cutoffs. Even a technically correct input may be ignored if submitted after a cutoff. The top approach is to align internal deadlines to the platform’s operational schedule, then communicate those deadlines consistently across managers and HR/payroll stakeholders.
To implement cutoffs effectively, organizations typically:
Timing also includes time zone considerations for global or multi-state operations. If employees are located in different time zones, internal deadlines must account for when data is captured and when it becomes effective. Inconsistent timing practices can create the perception that “the portal didn’t accept my update,” when the real issue is a mismatch between internal and portal timelines.
Although every organization’s process differs, very payroll teams using portal-driven systems follow a structure resembling the following:
In this context, Runpayroll.adp.com functions as an interface into those activities—helping teams execute them with consistent controls and visibility.
To further make this concrete, it’s useful to describe how these stages usually manifest. During Prepare, payroll staff may gather data from multiple upstream systems: time tracking tools, HR master data records, benefits enrollment systems, and manager-submitted adjustment forms. During this stage, the goal is not perfect payroll yet—it’s completeness and correctness of inputs.
During Validate, payroll staff inspect what the portal produces. This can include payroll previews, validation reports, or exception queues. The key is to catch issues before they become payroll paychecks. Many organizations use a “two-eye” or “maker-checker” approach: one person prepares and another independently checks critical totals and exception categories.
During Approve, the workflow requires that the approver confirm that there are no unresolved critical exceptions, that totals align with expectations, and that any known deviations are intentionally accepted. This stage ensures that finalization has governance.
During Process, the portal produces outputs for employees and downstream systems. The organization then needs to ensure that output files, payment confirmations, and accounting entries are consistent with internal expectations.
Finally, during Reconcile, payroll and finance compare totals, resolve discrepancies, and document deviations. Reconciliation is not only about correcting mistakes—it is also about creating a defensible audit trail that shows how totals were arrived at and what changes were made.
Since you asked to incorporate price information but no specific price figures were provided in the prompt, the comparison below focuses on cost-avoidance and operational impact instead of unverifiable pricing. Many payroll portal costs depend on contract terms, service tiers, and the size or configuration of the employer relationship. To stay accurate and objective, this table compares setup choices rather than speculative amounts.
| Area | Option A: Broad access | Option B: Role-based access | Operational condition |
|---|---|---|---|
| User roles | Many users can edit sensitive payroll inputs | Preparers edit; approvers confirm; others view only | Assign roles based on job responsibility, not convenience |
| Approval control | Approvals are informal or bypassed | Approvals are mandatory before finalization | Set a clear “ready for approval” standard |
| Change management | Edits happen late with little documentation | Edits are logged and reviewed with an exception workflow | Define what qualifies as an exception and who can approve it |
| Data quality | Multiple sources of truth cause discrepancies | Single system-of-record per data category | Establish ownership for employee master data and adjustments |
| Cost impact (indirect) | Higher likelihood of rework, corrections, and audits overhead | Fewer cycle disruptions; smoother reconciliation | Measure time spent on payroll corrections each cycle |
Although the table focuses on controls rather than pricing, it implicitly addresses a common “hidden cost” in payroll operations: the time and effort required to fix errors. When broad access exists, errors can occur more frequently, and approvals may not catch them early. When role-based access and structured approvals are used, the organization may not necessarily reduce the number of payroll steps, but it can reduce the number of fire drills.
For many organizations, that is where the true economic value appears—not in the “subscription price” alone, but in how quickly the payroll team can close each cycle and how confidently finance can reconcile. Even when pricing is fixed, operational savings come from reduced rework and fewer exceptions that require manual intervention after processing.
Payroll portal practices are shaped by provider documentation, security standards, and typical compliance expectations. For reliable, non-exaggerated guidance, organizations should align internal procedures with their provider’s official materials and relevant regulatory requirements. For risk context and top-practice themes (e.g., access control and identity security), organizations often consult recognized security frameworks such as NIST (National Institute of Standards and Technology) and use official payroll and tax compliance resources where applicable.
Because portals can be configured differently per organization, it’s important that internal stakeholders avoid assumptions like “all users see the same screens” or “this button behaves the same in every environment.” Instead, experts typically validate the actual permissions and workflow states in a staging environment or during pilot cycles.
Additionally, organizations should treat portal permissions and auditability as part of their broader compliance approach. Many jurisdictions require payroll records and tax reporting with appropriate documentation. Even when the portal is the operational tool, your internal policies govern how decisions are documented and how changes are reviewed.
Below is a practical implementation-style guide designed for payroll administrators, HR operations leaders, and finance partners. It focuses on process readiness and control design rather than unsupported assumptions.
Before relying on Runpayroll.adp.com for operational work, confirm which modules your organization has enabled and what each role can access. If your payroll workflow involves multiple teams (HR, time management, finance), clarify what each team is expected to do inside the portal.
This step includes verifying that the portal environment is aligned with your pay cycle needs. For example, confirm whether you are running single or multiple pay frequencies, whether your organization is managing multiple entities, or whether certain configurations (such as deduction structures or earning code setups) are ready. If you are onboarding new employees or expanding to new locations, confirm that the portal has the required rules for those jurisdictions.
It also includes a governance check: confirm who owns each step in the lifecycle and ensure the portal screens and actions correspond to those steps. When teams are unclear about what happens “before” and “after” portal actions, errors rise because users attempt to solve problems by editing more data rather than following the workflow.
Create or verify user accounts and map permissions to job duties. For example, one group should prepare, while another group should approve. Ensure view-only users cannot modify sensitive payroll inputs, and confirm audit-friendly behavior (e.g., logged changes where supported).
To make permission validation more robust, organizations often test with realistic scenarios:
In expert practice, permission validation also includes checking user lifecycle handling: new hires, transfers, terminated users, and temporary access for contractors. If access is not deprovisioned promptly after offboarding, it increases security risk and may create compliance problems if someone’s account remains active.
Define where key employee data is maintained and how changes are processed. If managers submit updates, confirm they flow correctly into payroll-ready records. This reduces mismatches like incorrect pay rates, outdated deduction settings, or missing earning codes.
Master data ownership should include escalation logic. For instance, if payroll discovers that an employee’s pay rate is incorrect, payroll must know whether to correct it directly (if permitted) or whether to route the issue to HR. The goal is to keep changes controlled and traceable. You can measure effectiveness by how often payroll must “hunt” for the right owner to solve an issue.
Ownership also relates to effective date policies. If managers submit changes, confirm they understand how effective dates work and how those dates impact payroll calculations. It’s common for mistakes to occur when a change is entered with an effective date that applies to the wrong pay period.
Set internal deadlines earlier than the portal’s effective processing deadlines. Communicate them to departments that supply payroll inputs. This is a common source of cycle stress—internal teams may assume “it’s in the system,” but the payroll run may only accept certain updates before a defined window.
To implement this successfully, many organizations publish a timeline that includes:
Another expert tip is to create a “cutoff exception policy.” For example, you might define what kinds of late changes are allowed (if any), and who can authorize them. Without such a policy, every late issue becomes a negotiation, slowing cycles.
If your configuration allows testing or previews, use it to validate end-to-end behavior: data entry → calculation preview → exception review → approval → output reconciliation. Treat the first cycle as a learning cycle to surface gaps in training or ambiguous role responsibilities.
During a test cycle, experts pay attention not just to whether the system runs, but to whether the process behaves consistently. For example:
If discrepancies arise during a test cycle, document them and refine the process. This can include updating training materials, clarifying responsibilities, or adjusting data submission practices.
Define what happens when something doesn’t reconcile—who investigates, what evidence is required, and how quickly escalation should occur. In expert terms, you’re building a “decision tree” so staff don’t improvise under time pressure.
Exceptions in payroll can take many forms. Examples include:
For each exception category, your decision tree should identify: likely causes, required data to confirm, the owner to contact, and what the resolution should be (e.g., revise inputs before approval, or accept a controlled exception and document it).
Escalation should also consider the urgency of the payroll stage. For example, an exception identified early in the cycle can be resolved more flexibly than an exception discovered after approvals are granted. Your escalation paths should reflect that reality.
After processing, compare payroll totals and key line items with finance expectations. If the portal’s results feed accounting entries, reconcile at the level your finance team requires. This is where many organizations either strengthen controls or accumulate future corrections.
Reconciliation is not solely an accounting task; it is a control verification step for payroll accuracy. A robust reconciliation process typically includes:
When discrepancies arise, document the cause and resolution. Then close the loop by updating upstream data sources or process steps to prevent recurrence.
Track operational friction: frequent exception types, recurring input mistakes, and approval delays. Update training and internal SOPs accordingly for the next run. Over time, this reduces both error rates and cycle time.
Post-cycle reviews should also include “process metrics,” not only outcome metrics. For example:
These metrics help identify whether improvements should focus on user training, cutoffs, system configuration, or ownership clarity.
Below are common conditions/requirements organizations should plan for when operating payroll through a portal environment such as Runpayroll.adp.com:
It may help to think of these conditions as “pillars” of safe payroll operations. If any pillar weakens—if roles are unclear, if cutoffs are ignored, or if training is incomplete—errors increase and the process becomes reactive. Reactive processes are expensive and stressful, and they increase the chance that an error could slip through without proper review.
Also, consider operational resilience. Payroll teams must often meet deadlines despite interruptions: sick leave, vacation coverage gaps, unexpected system issues, or organizational changes. A resilient portal workflow includes backup approvers, documented procedures, and training materials that allow new users to ramp quickly.
Finally, payroll is an area where data sensitivity is critical. The portal will handle personally identifiable information (PII) and financial data. Organizations must therefore treat access, authentication, and audit logs as part of the “day-to-day” operations—not as a one-time IT project.
Runpayroll.adp.com is used as a payroll portal access point in many ADP-powered environments. Employers typically use it to support payroll-related tasks—such as reviewing payroll data, performing or validating payroll steps, and coordinating approvals—depending on the specific configuration and your organization’s enabled modules.
In many organizations, the portal also serves as the place where payroll administrators monitor the status of payroll tasks. This means the portal is often used not only for editing but also for checking progress and verifying that the cycle is within the correct workflow stage.
In well-controlled payroll operations, editing permissions are restricted to designated preparers or authorized roles. Approvers usually confirm readiness but do not edit unless your policy explicitly allows it. View-only access is typically assigned to stakeholders who need visibility but not modification rights.
What qualifies as “authorized” should be defined in internal policy. Some organizations allow a limited set of corrections by preparers under specific conditions (for example, correcting a typo in a non-sensitive field). Others require that any change after validation be treated as an exception requiring additional approval. The correct choice depends on internal control requirements, risk tolerance, and audit expectations.
Approvals serve as a control checkpoint. They verify that the payroll inputs and calculated outputs match expectations before finalization. Without approvals, payroll teams may end up correcting issues after processing, increasing rework and reducing audit defensibility.
Even if payroll calculations produce a number that “looks right,” there can be misconfigurations (wrong earning codes, incorrect effective dates, missing deductions) that only become visible through careful review. Approvals create a structured pause where an accountable person confirms that everything is in order.
Common causes include late submissions past cutoffs, incorrect pay rates or earning codes, incomplete deductions, ambiguous changes submitted by managers, and unclear exception handling. Another frequent factor is insufficient training on portal workflow and status indicators.
Other practical contributors often include:
Yes—when cycle time is driven by process improvements. Organizations typically gain by tightening cutoffs, reducing manual rework, clarifying ownership, and standardizing review steps. The portal helps, but the process design determines whether time savings are real.
Cycle time improvements usually come from predictable inputs and fewer surprises. For example, when managers submit changes earlier and payroll can validate without chasing missing data, the cycle becomes faster and calmer. Similarly, when approvers follow the same review checklist each cycle, approvals become less time-consuming.
There is usually no single universal price for portal access because payroll offerings typically depend on contract terms, service tiers, number of employees, and configuration. For pricing, the very reliable approach is to consult your specific ADP agreement or a formal quote from your provider or implementation team.
Organizations that want clarity typically request pricing details that separate portal access from implementation, configuration, and support services. This helps ensure there are no misunderstandings about what is included in the subscription or managed service.
If access fails, first confirm role assignment and whether the user has been provisioned correctly. Then check authentication requirements and any organization-level security policies. If the issue persists, escalate to your internal system administrator or ADP support channels per your organization’s established procedures.
In urgent payroll windows, organizations should have a “break-glass” or emergency access process aligned to policy. This reduces delays when a critical user’s access fails close to approval time, while still maintaining governance and documentation.
Compliance and audit readiness depend on your internal policies and the controls you apply to data changes, approvals, and documentation. Use a structured review workflow, restrict editing permissions, and keep records of approvals and exception decisions consistent with your governance requirements.
Audit readiness also depends on how consistently the organization follows the workflow. If approvals are sometimes skipped or if changes are made outside of the portal workflow (even when technically possible), the audit trail may become incomplete. Therefore, audit readiness requires both the system configuration and consistent operational adherence.
For payroll professionals, the very productive mindset is to treat Runpayroll.adp.com as a control system embedded in your operational governance. When roles are clearly defined, cutoffs are respected, and approvals follow a consistent checklist, payroll cycles become more predictable and corrections decrease. Over time, the portal supports better consistency across teams—and that consistency is where operational value is created.
To operationalize this mindset, organizations should invest in three long-term practices: governance (so roles and access remain correct), education (so users understand the workflow and status cues), and measurement (so the business can identify recurring friction). These practices are what turn a portal into an operational advantage rather than a new place where errors can occur.
Ultimately, payroll is high-trust work. Employees trust their employer to pay them correctly and on time; finance trusts payroll to produce totals that reconcile; compliance depends on auditability. A portal like Runpayroll.adp.com can support these expectations—but only when the organization designs around it, governs it, and uses it consistently.
Note: This article does not provide unverifiable pricing figures and does not assume specific features that may vary by ADP configuration. For exact capabilities, permissions, and any plan-related cost details, consult your organization’s ADP agreement or implementation documentation.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

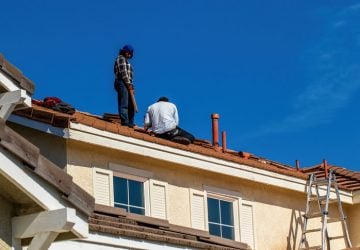
Smart Strategies to Slash Costs on Your Roof Replacement Endeavor
Opening Remarks: Smart budgeting doesn't mean cutting corners on quality. This guide will delve into cost-effective approaches for roof replacement that maintain high standards.
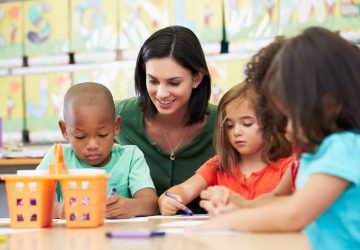
Unlocking the Secrets of Preschool: Your Ultimate Guide to Early Childhood Education Programs
The significance of early childhood education programs is paramount in shaping the foundational stages of a young child's life. These educational experiences aim to furnish children with a diverse skill set before they face the structured environment of elementary education. Such programs offer a dynamic and engaging atmosphere where children's natural curiosity leads to the broadening of their thought processes. Moreover, they focus on rectifying behavioral patterns and fostering positive principles and routines.
Enhance Your Smile: Essential Gum Care Tips After Teeth Replacement
After getting new dental implants, it's crucial to look after your gums to aid recovery, shield against infection, and enhance the durability and function of the implants. This discussion delves into the key methods and top tips for gum care that are vital to keep your gums robust and healthy after your procedure.
Unlock the Secrets to Championing Fair Pay: A Guide to Fighting for Competitive Nurse Salaries at Your Hospital
To effectively navigate the intricacies of nurse compensation in healthcare institutions, a thorough understanding goes beyond the basics. Strategic advocacy is essential, honoring nursing as a critical profession while also deeply comprehending the economic aspects of healthcare. This article lays out systematic methods to advocate for fair remuneration for nurses, aimed at closing the divide between managerial policies and the realities nurses face daily.
Protect Your Golden Nest Egg: Smart Strategies and Essential Precautions for Securing Your Gold Investments
Investing in gold requires more than just purchase; diligent protection and a strategic mindset are crucial. A secure gold investment is built on thoughtful planning, alert risk management, and the capacity to adapt to changes. We'll explore various ways to protect these investments from the diverse challenges they face.
Unlock Higher Earnings: Master the Art of Leveraging Your Nursing Expertise for a Hefty Pay Raise!
Unraveling the complexity of the payment landscape in nursing isn't for the faint-hearted, yet it's a manageable task with a strategy in place, enhancing one’s prospects for improved salary through skill and knowledge. This delicate dance of upholding patient care while seeking just rewards is a path all nurses must walk. Grasping the elaborate character of the nursing role and what propels one's income forward is crucial. Within this paper, we dissect insightful methods to maximize the impact of your nursing qualifications.
