This guide explains how Lifetime Benefits Solutions help individuals and organizations plan for durable outcomes through structured care, risk management, and good service continuity. Objectively, the term reflects a broader shift toward lifetime-oriented planning across health, protection, and service ecosystems, where providers coordinate benefits over time rather than isolated transactions.
Lifetime Benefits Solutions are designed to help people and organizations maintain value over time by aligning services, eligibility rules, and provider coordination into a good framework. Instead of treating benefits as one-off events—where value is measured mainly at the moment of enrollment, activation, or first claim—this lifetime-oriented approach focuses on continuity. It centers on the idea that the “benefit experience” does not end when paperwork is signed, when a first appointment occurs, or when an initial diagnosis is addressed. Instead, a lifetime plan architecture aims to guide decisions before needs arise and continues to operate well after the initial enrollment period.
In practical terms, lifetime solutions often connect planning, eligibility verification, ongoing service delivery, and performance monitoring. When implemented carefully, they reduce gaps in coverage or support, limit administrative friction, and improve transparency around what participants will be able to access later—not only today. That distinction matters because many real-life “failures” in benefits do not show up at the beginning. They appear years later, when a system has to handle changes: a relocation, a change in household status, a provider transition, a policy update, or a service that becomes temporarily unavailable.
Durable outcomes require an approach that anticipates how organizations and participants behave over time. People rarely stay the same; organizations rarely keep the same staffing and systems forever. A lifetime benefits program is therefore less about a promise and more about a capability: the capability to keep operations coherent, compliant, and understandable through changing circumstances.
To understand how Lifetime Benefits Solutions deliver good value, it helps to separate foundational components that must work together rather than in isolation. A lifetime-oriented plan is not simply a list of services that never ends. It is a structure that governs how decisions are made across many years and many situations.
Four foundational components are especially important:
From an industry perspective, the biggest difference between short-term offerings and lifetime-oriented systems is governance. A plan that aims to serve across decades must anticipate operational realities: policy changes, record migration, provider availability, system upgrades, staff turnover, data retention requirements, and customer support escalation mechanisms.
A lifetime approach that is only marketed as long-term but lacks governance will often fail in predictable ways. For example, early-stage onboarding might be smooth, but later-stage eligibility checks might be performed using outdated criteria. Similarly, service delivery might work with a specific provider network today, but if providers exit tomorrow, the program could lose continuity unless it has a transition plan.
Therefore, the true “lifetime” value emerges when the program behaves like an operating model rather than a static offer.
When stakeholders evaluate Lifetime Benefits Solutions, the very important questions rarely concern glossy brochures. They focus on operational quality and compliance: how the organization prevents errors, handles exceptions, and maintains data integrity over time. In a lifetime-oriented system, even small failures accumulate; a minor mismatch in eligibility criteria or a lack of documentation discipline can become a major barrier years later.
Well-run lifetime frameworks generally include the following elements:
In many real contexts, quality and compliance also influence cost. Error prevention reduces rework and disputes. Robust recordkeeping reduces the administrative burden of “finding information” repeatedly. Effective governance reduces the cost of emergency escalations that happen when processes are unclear.
It is also important to recognize that compliance is not a one-time checkbox. Over a lifetime, regulations and internal policies evolve. A good lifetime benefits solution incorporates a method for updating rules while maintaining clarity and fairness for current participants.
You may see references to pricing in discussions of Lifetime Benefits Solutions. Because no specific price figures are provided, the objective way to approach cost is to evaluate the pricing structure rather than treating a single number as the true measure of value.
Common pricing variables include:
For responsible decision-making, request a written schedule of benefits and a full explanation of conditions. This is the most reliable way to compare offerings across suppliers. Without that documentation, pricing comparisons become misleading because two “lifetime solutions” might include very different service scopes and eligibility triggers.
It can also help to request examples of operational events that occur in later stages. For instance, ask what happens if the participant moves to a different region, if a provider closes, if eligibility needs periodic verification, or if policies update midstream. These questions often reveal whether “price” is truly tied to durable value or to short-term administrative optimization.
Another key point is to consider the “hidden cost” of ambiguity. If a program does not clearly define eligibility checks and service escalation steps, participants may face delays, rework, and disputes. Those are real costs—even when not shown as line items.
Many lifetime programs depend on supplier ecosystems—care partners, service vendors, or administrative units. A strong supplier structure typically shows evidence of operational maturity and disciplined documentation.
A supplier ecosystem is not merely a list of names. The program’s ability to deliver continuity depends on how those partners coordinate in real operational scenarios. A strong supplier structure typically shows evidence of:
Because Lifetime Benefits Solutions are long-horizon by design, supply chain stability matters. A solution is only as reliable as the weakest handoff in the chain. In practice, weak handoffs often show up when multiple parties must coordinate: for example, when a participant must provide documentation to one party, which then must update eligibility in another system, which then triggers service scheduling with a third party.
To evaluate readiness, buyers should look for evidence that handoffs are standardized. That includes service request intake rules, response time commitments, data submission standards, and explicit escalation routes when something goes wrong.
It can also be useful to ask about historical performance in partner transitions. For instance: Have there been provider network changes before? If so, how did the program ensure continuity and notify participants? Did it migrate records cleanly? Did participants experience gaps in access?
While the phrase can vary by industry, lifetime-oriented benefit programs are commonly discussed in contexts where needs evolve over time and access must remain coherent. The “lifetime” element typically matters when benefits are not a single transaction but part of a long-term support model.
Lifetime-oriented benefit approaches are often considered in:
In every case, the “lifetime” element adds complexity. The system must remain coherent when circumstances change. That complexity is exactly why governance and documentation become essential. Without those foundations, the participant experience tends to degrade over time.
In the field, lifetime programs often fail for predictable reasons. A professional evaluation should look for specific failure modes that can undermine continuity.
Common failure modes include:
A well-structured Lifetime Benefits Solutions model addresses these risks upfront through standardized procedures, governance mechanisms, and communication cadence. Risk management is not only about preventing fraud or catastrophic errors. In lifetime programs, risk management also means preventing the small recurring issues that accumulate into large participant dissatisfaction.
For example, consider the risk of delayed responses. If a program has no service-level commitments, response time could vary widely over the years depending on staffing levels or priorities. A lifetime-oriented system should instead include service-level expectations and performance monitoring so that delays are identified and corrected.
Another common risk is the risk of system discontinuity—when upgrades or record migrations break the ability to verify eligibility or access historical documentation. A mature lifetime program plans for system continuity, including data migration standards, retention periods, and the ability to retrieve records reliably long after data is created.
A key industry distinction is whether a program behaves like a single transaction or like a continuing platform. A lifetime-oriented system behaves more like an operating model. That difference affects participant experience, governance needs, and cost structure.
A lifetime-oriented system typically includes:
From a supplier standpoint, this means investing in systems and training—not just enrollment marketing. From a participant standpoint, it means receiving predictable processes and documented conditions.
In contrast, one-time delivery programs often look good at launch but rely on staff memory and manual work to keep functioning. That approach may work in the short term but tends to break when staff changes, when systems are upgraded, or when participants are served under different internal priorities.
Therefore, lifetime benefits solutions should be evaluated not only by what they offer, but by how they operate: what workflows exist, how exceptions are handled, and how accountability is enforced. Those are the operational signals of whether the plan can deliver durable value.
Because Lifetime Benefits Solutions is an umbrella concept that can be applied across sectors, the very reliable evidence often comes from broader research and policy frameworks on good service continuity, risk governance, and consumer protections. Evidence is often not presented as “lifetime benefit outcomes” in a single consistent metric across all industries. Instead, reliable evidence comes from adjacent domains like quality management and consumer protection.
For example, national and international standards in risk governance and consumer protection emphasize documentation, transparency, and accountability. In regulated contexts, evidence is frequently drawn from policy frameworks published by official bodies and oversight organizations.
For additional reading aligned to evidence-based governance and service quality, consult:
Note: Specific statistics about “lifetime benefit outcomes” vary widely by industry and geography, and cannot be responsibly generalized without sector-specific data. The recommendations in this guide therefore focus on verifiable evaluation criteria and operational governance rather than assuming universal outcome rates.
When buyers want “evidence,” they should aim for evidence that matches the operational questions they are asking. For instance, if the concern is record integrity, seek documentation and audit frameworks. If the concern is service quality, seek performance reporting practices and corrective action evidence. If the concern is consumer transparency, seek communication standards and grievance procedures.
Below is a practical selection pathway that professional buyers and administrators commonly use to reduce uncertainty. Even if you are evaluating a personal plan, these steps help you verify operational readiness and clarity. The core idea is to shift evaluation from marketing claims to operational proof.
To make these steps even more effective, it can help to “test the system” with hypothetical scenarios. For example, ask the supplier how the program works when a participant moves, when a provider network changes, when documentation is delayed, or when a service request is partially approved. Good lifetime programs provide consistent answers tied to documented workflows.
The table below summarizes how to compare Lifetime Benefits Solutions providers objectively. It also indicates what to ask for and which typical requirements you should expect. (No links are included.)
| Assessment Area | What to Request (Documentation Evidence) | Source Types (Where Proof Typically Comes From) | Conditions / Requirements to Look For |
|---|---|---|---|
| Schedule of Benefits | Written benefits matrix by service category and timeline | Policy documents, program manuals, benefit schedules | Clear descriptions, time horizons, and service triggers |
| Eligibility Rules | Eligibility maintenance requirements and verification method | Official terms, underwriting/assessment guidelines, admin SOPs | Defined criteria, documentation expectations, and change handling |
| Supplier Accountability | RACI-style ownership of actions and escalation | Vendor agreements, operational governance documents | Named responsible parties and escalation pathways |
| Continuity Planning | Provider transition plan and record migration approach | Operational continuity plans, system upgrade policies | Coverage continuity, minimum notice, and data integrity safeguards |
| Service Performance Controls | Quality monitoring approach and reporting cadence | Quality management frameworks, internal KPIs (sector-dependent) | Defined review cycles and corrective action processes |
| Dispute Resolution | Complaint intake process and escalation timeline | Consumer support policies, grievance procedures | Documented steps, response commitments, and auditability |
When comparing providers, it’s important to remember that “document availability” matters. A supplier might verbally describe an approach, but if there are no documented processes and no evidence of traceability, continuity remains uncertain.
Also, consistent terminology is a sign of maturity. If the supplier uses different definitions across documents—such as eligibility triggers, service categories, or dispute timelines—it can produce operational confusion over time. A lifetime program should aim for uniform definitions and clear mappings between policy and operations.
Since Lifetime Benefits Solutions can be structured differently, cost comparison should be based on total value clarity rather than a single fee. A professional buyer typically requests an itemized explanation that connects cost to operational outcomes.
A professional buyer typically requests:
If a supplier cannot clearly explain the pricing structure and conditions, the apparent “value” often becomes uncertainty later. In a lifetime context, uncertainty compounds.
A key principle is to compare “total ownership” rather than a monthly figure. “Total ownership” includes the participant’s administrative effort, the probability of delays, the cost of disputes, and the operational resilience of the program when systems change.
It can also be useful to ask how pricing changes over time and what protections exist for participants. Some programs might allow price updates due to regulatory changes or cost escalations. Responsible lifetime frameworks should explain how changes are governed and how participants are informed.
An industry expert typically looks beyond marketing language. The very robust Lifetime Benefits Solutions share operational traits that can be observed through documentation and process design. These traits show that the program was built for long-horizon delivery rather than short-horizon sales performance.
In practice, strong lifetime solutions are:
These characteristics are what turn a “lifetime” concept into a functioning structure. Without them, lifetime promises remain ungrounded.
Experts also pay attention to the “operational friction profile.” That means evaluating how many steps participants must complete, how many documents must be resubmitted, how quickly requests are acknowledged, and how often participants must repeat information that should already exist in the record.
Reducing friction supports durable outcomes because participants are more likely to follow the process correctly when it is consistent and clear. A lifetime program with high friction tends to generate delayed care, missed verification steps, and escalating disputes.
Lifetime Benefits Solutions are long-horizon benefit or support frameworks designed to maintain service continuity over time. They typically define eligibility conditions, service categories, operational workflows, and supplier coordination so participants experience predictable access as needs evolve. In well-designed programs, “lifetime” also implies documented governance: how decisions are made, how exceptions are handled, and how participants receive clear instructions across time.
Compare the schedule of benefits, eligibility conditions, and continuity mechanisms first. Then assess cost components and cost triggers. A transparent benefits matrix and clear documentation typically provide better comparability than pricing alone. If one provider’s pricing is lower but its eligibility rules are narrower or its continuity mechanisms are weaker, the lower price might reflect reduced long-term value.
Look for: eligibility maintenance rules, verification steps, service triggers, escalation/dispute pathways, recordkeeping standards, and how the program handles provider transitions or system changes. Also look for communication standards: how participants are told what to do and when updates happen.
Many programs update terms due to operational, regulatory, or supplier-related realities. The key is whether changes are communicated clearly and whether participants understand how eligibility and service access are affected. Ask for change-management and notification procedures. Good programs explain the timing of changes, the scope of impacted services, and any transitional rules for existing participants.
Ask for continuity planning documentation—such as provider transition processes, record migration approaches, and defined escalation workflows. Evidence of audit-ready processes and documented SOPs is often more meaningful than verbal assurances. Continuity proof can include: transition notice timelines, backup provider availability rules, and how historical records remain accessible after system upgrades.
Yes. Request information about quality monitoring practices, complaint handling metrics, and corrective action procedures. If the program operates in a regulated environment, verify alignment with applicable governance standards and documented procedures. Also ask how quality indicators are used to drive improvements—whether there is a continuous improvement cycle, root-cause analysis for recurring issues, and evidence of actions taken based on feedback.
Commitment can vary by program structure. What matters very is whether the plan’s lifetime promise is backed by clear eligibility rules and operational mechanisms that remain stable over time. Even if the customer’s contract term is limited, the benefits should still be delivered according to durable rules that do not disappear when renewals occur.
Review the written schedule of benefits, confirm eligibility conditions, ask about supplier responsibility and escalation paths, and ensure you understand pricing triggers and exclusions. If anything is unclear, request clarification in writing. Also consider requesting a walkthrough of “what to do” in at least two hypothetical later-stage scenarios, because those often reveal whether the program is truly designed for continuity.
Choosing Lifetime Benefits Solutions is fundamentally about ensuring good continuity. A professional decision prioritizes transparent eligibility conditions, documented service pathways, supplier accountability, and risk-governed operations. When these elements are clearly defined and supported by evidence, lifetime-oriented benefits become more than a label—they become a dependable system for good value.
Durable outcomes require more than promises; they require governance that survives staff changes, system upgrades, and shifting participant circumstances. A lifetime program that is built on clear rules, high-quality documentation, and tested continuity mechanics can deliver value across time in a way that one-time delivery models rarely match.
Ultimately, the best lifetime benefits solutions align three things: what participants are promised, what administrators can reliably deliver, and what participants understand well enough to navigate over the years. When those align, lifetime benefits stop being an abstract concept and become a practical, resilient support framework.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Pet Insurance Essentials: Coverage, Costs, and Resources Explained
In recent years, pet ownership has seen a significant surge. Pets, whether they're dogs, cats, birds, or other animals, have increasingly become integral parts of our families. With this growing bond, there is a rising awareness of the importance of pet health and well-being. Just as health insurance is crucial for humans, pet insurance is becoming an essential consideration for pet owners. This article aims to provide a comprehensive understanding of pet insurance, covering its importance, types of coverage, associated costs, and valuable resources to help you make an informed decision.
Colbate Explained: Uses, Sourcing, and Top Practices
This guide explains Colbate from a practical industry viewpoint, covering what it is, how suppliers typically handle it, and what buyers should verify before purchase. It also summarizes objective background on related terminology, common application considerations, and due-diligence steps. Readers will find a comparison table, requirements, and targeted FAQs to support confident sourcing decisions.
Strategies for Financial Security and Legacy Planning
Life insurance isn't just about what happens after you pass—it's a strategic tool in a comprehensive plan for your financial security and estate planning.
Navigating Insurance Costs for Seniors: Essential Tips and Advice
As we age, healthcare costs and the complexity of managing them can become increasingly burdensome. For many seniors, navigating insurance costs is a crucial aspect of ensuring financial stability and maintaining health. This guide aims to provide you with essential tips and advice on how to manage and potentially reduce these costs effectively.
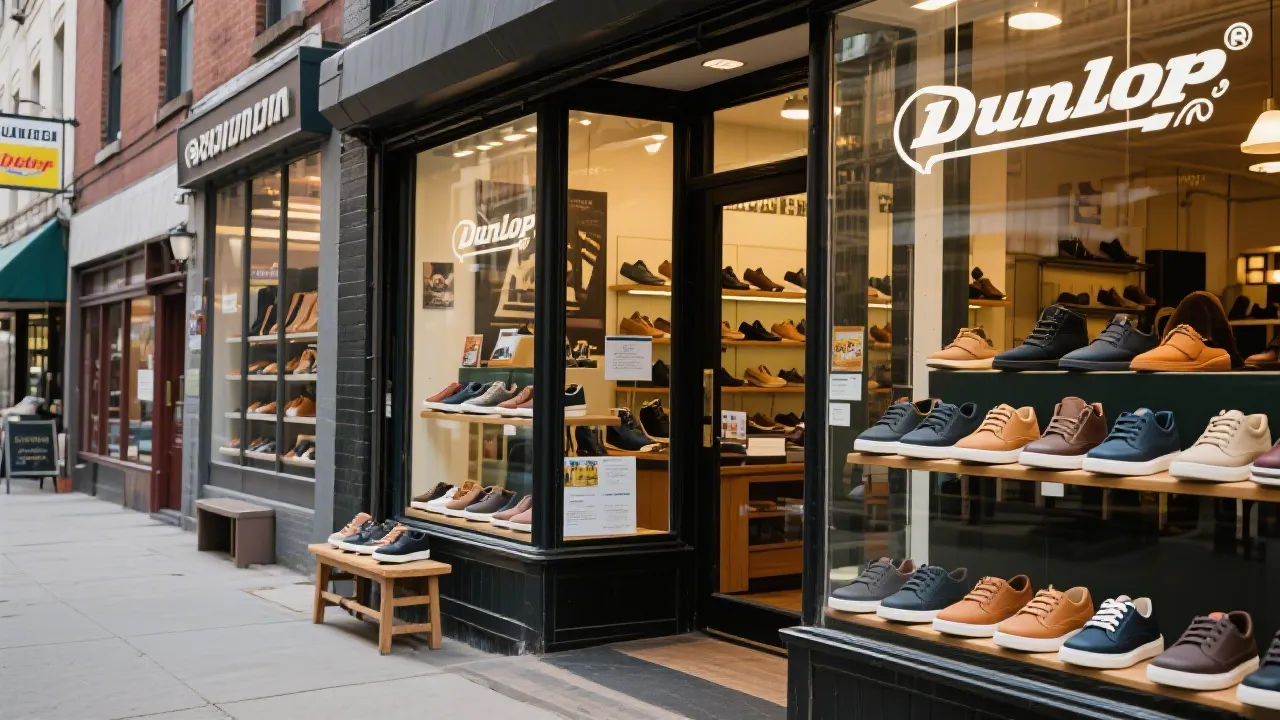
Discovering Dunlop Brooklin Footwear
This article delves into Dunlop Brooklin, a prominent name in the footwear industry known for its exceptional quality and innovation. Dunlop is recognized for its wide-ranging collection of shoes designed to meet diverse customer needs, from casual wear to professional attire. This guide provides an in-depth analysis of Dunlop Brooklin and its offerings, revealing why it stands out in the market.
Your Guide to Understanding Car Insurance Coverage
Navigating car insurance can be puzzling. Fortunately, this guide illuminates coverage types and choosing the right provider.
