Layaway can help shoppers manage costs by paying over time while keeping the item reserved. This guide explains how layaway works in practical terms, what buyers should verify before committing, and how retailers structure payments. It also covers key conditions—eligibility, timelines, fees, and refunds—so consumers can evaluate options with clear expectations.
Layaway is a payment arrangement where you secure an item by making scheduled payments, typically before the retailer releases the product to you. Instead of purchasing immediately and paying later through credit, layaway generally involves reserving the merchandise while you complete a pre-set payment plan. In many versions of the program, the retailer keeps the item available for you until the plan is completed (or until a specific pickup deadline). For consumers who prefer budgeting over traditional “pay all at once” purchases—and for retailers that want to reduce uncertainty—layaway remains a useful option when you understand the terms. The very important starting point is not the monthly amount, but the conditions that govern your reservation: the purchase deadline, cancellation rules, applicable fees, and what happens if you miss a payment.
When layaway is used well, it can turn a “maybe I can afford this later” situation into a structured plan you can follow. It can also help you avoid the temptation to change your mind midstream without financial consequences. However, layaway is not risk-free. Because the retailer holds inventory and applies administrative handling, their policies often include time limits, non-refundable components, and consequences for missed payments. The key to using layaway responsibly is understanding those tradeoffs before you commit.
Unlike credit-based options, layaway generally focuses on installment payments toward a specific purchase while the item remains under the retailer’s control until fully paid (or until a pickup date). In many markets, the retailer holds the merchandise for a defined period, after which the policy may change if the shopper has not completed payments.
From an industry perspective, layaway programs can serve multiple roles:
To make it simple, think of layaway as a “reservation with a payment schedule.” Payment is the condition that keeps the reservation intact. Ownership transfer typically happens later, when the required payments are complete and you meet pickup or receipt requirements. In contrast, some other “pay later” products may involve credit approval and immediate purchase, meaning you could be responsible for payments even if you never receive the item in the same way.
Another difference is how you manage the risk. With some alternatives, the risk of delayed delivery or return disputes can shift in different ways between you and the provider. With layaway, the major risks often include cancellation policy outcomes and the consequences of missing payments that cause the reservation to expire. The more you can align your plan with your real pay schedule, the more layaway functions like a budgeting tool instead of a source of surprise costs.
If you’re considering a layaway arrangement, the “small print” matters. An industry expert would typically recommend verifying the following items before you sign or agree:
Beyond those core questions, it also helps to ask about communication and recordkeeping. For example, how will you be notified about upcoming payments or deadlines? Do you receive printed receipts after each installment? Is there an online account or a way to check status? A plan can still be “fair” on paper, but if it’s difficult to track or correct, it becomes stressful in practice.
You should also ask what exactly is being reserved. Sometimes “the item” can be a broad category (e.g., “a similar model”) rather than a specific unit. If the product’s features matter—like the size of an appliance, the storage capacity of electronics, the model number of a tool, or the color variation of an item—clarity about what’s reserved is crucial.
Policies vary by retailer and jurisdiction, so use this comparison as a checklist framework—not as a substitute for reading the store’s official terms. The value of a checklist is that it pushes you to think about risk and consequences in the same way you would for any other contract. Even if you’re confident you’ll finish the plan, it’s wise to understand what happens if you can’t.
| Policy Area | What to Verify | Typical Shopper Impact |
|---|---|---|
| Eligibility | Minimum purchase amount, eligible product categories, and any customer ID requirements. | May limit what you can reserve (e.g., certain sale items). |
| Deposit & Payment Schedule | Required initial payment, installment frequency, and acceptable payment methods. | Determines whether the plan fits your monthly budget. |
| Plan Duration | Reservation length (deadline for completing payments). | Missing the deadline can end the reservation or trigger fees. |
| Fees | Setup/service fees, storage charges, or cancellation/restocking fees. | Can change the effective total cost of the item. |
| Late or Missed Payments | Grace periods, reactivation rules, and consequences for non-payment. | May require catching up quickly to protect the reservation. |
| Cancellation & Refunds | Whether partial refunds apply and whether refunds are reduced by fees. | Impacts your risk if your plans change. |
| Pickup & Ownership Transfer | Pickup deadline, proof-of-payment requirements, and when ownership transfers. | Late pickup could result in forfeiture or additional charges. |
| Item Substitution & Availability | Whether the original item can be replaced if inventory changes. | Helps avoid surprises if the product is out of stock. |
To go deeper than this table, think about the “decision points” in the plan. For instance, one decision point occurs at the moment you begin the layaway: the retailer might require a deposit and reserve a specific unit or reserve “comparable inventory.” Another decision point occurs when you make each installment: the retailer’s policy might allow grace periods or might treat any missed payment as grounds for cancellation. A third decision point occurs near the end: the final payment might be due by a certain date, and even after you finish paying, pickup might be required within a narrow window.
Those decision points are where most layaway friction arises. If you understand them before you start, you can avoid losing the reservation due to misunderstanding. If you don’t understand them, layaway can become a guessing game at the worst possible time—right when deadlines are approaching.
To understand layaway, it helps to look at how retailers manage inventory and risk. When an item sits reserved but not yet paid in full, retailers face a mismatch between immediate demand and cash flow. In response, many layaway systems incorporate:
These design choices are not inherently consumer-friendly or consumer-unfriendly; they are operational levers. Your goal as a shopper is to ensure the levers align with your ability to complete payments and follow through on pickup. If the policy is strict, you should treat it as a commitment device: it will help you stay disciplined, but it will also impose consequences if life changes.
From a consumer psychology perspective, layaway can be effective because it creates “progress.” Every payment you make signals that the item is closer to being yours. That progress can motivate better budgeting behavior. At the same time, because layaway ties you to a specific item, it can reduce flexibility. If you might need the cash for an emergency, you should consider what portion of your payments would be at risk under cancellation rules.
Retailers also design policies to reduce fraud and reduce administrative complexity. Clear identification and documented payment records lower the chance of disputes about whether you paid on time. That’s why some retailers require specific identifiers or require proof of prior payments when you return for pickup.
Below is a practical sequence you can follow. If any step feels unclear, ask the retailer to explain the policy in writing. You want a paper trail not just for reassurance but because disputes are easier to resolve when terms are clearly documented.
One additional step that many people forget is to plan for contingencies. For example, if you pay in person, what happens if the store closes early on a payment date? If you pay by cash, what should you do if you run short? If you pay using a specific method, what happens if that method isn’t available at the last moment? Many retailers can accommodate reasonable changes, but accommodations are policy-dependent. Thinking about these scenarios before they occur helps you prevent small problems from turning into missed deadlines.
Also, keep in mind that “installment” doesn’t always mean equal amounts. Some plans might include a larger final payment or might apply fees spread across installments. Make sure you understand the full payment map, not just the next payment.
Layaway decisions typically fall into a few recurring patterns. Consider these examples as decision frameworks rather than predictions of any specific retailer’s policy. Different product types raise different risks. For example, electronics raise the risk of model substitutions, appliances raise the risk of delivery logistics, and seasonal items raise the risk of price changes and inventory movement.
Electronics and appliances can carry higher price tags, which makes installment planning attractive. However, because high-demand items may sell out, a key verification is whether the reserved item remains guaranteed until pickup or whether substitutions are possible. Ask whether the retailer can hold a specific model and serial-equivalent details (where applicable) or whether it reserves a comparable item.
When dealing with appliances, additional practical questions often matter:
For electronics, model-specific questions may include:
Even if a retailer promises substitution is “similar,” “similar” can still be materially different for you. The safest approach is to ask what criteria define “similar” and whether the substitution would preserve the features you care about most.
Some shoppers assume layaway automatically applies to promotional pricing. The better approach is to ask whether sale pricing locks in when the plan begins or whether the price can change if payments extend beyond the promotion window. If pricing stability is important to you, request confirmation in writing.
Promotions introduce a subtle risk: even if the plan is structured, the economics may change. Retailers might change prices due to supplier costs, inventory levels, or competitive pressures. Some stores may honor the promotion as long as the layaway is active and payment milestones are met. Others may revise pricing when the promotion ends, especially if the plan continues.
To evaluate the risk, compare the potential impact to your budget. If the promotional price is a significant portion of the total cost, even a small increase could affect your ability to finish. You can reduce risk by:
If you’re not able to get those confirmations, treat the plan as carrying some uncertainty and consider whether another budgeting approach would be safer.
If your pay cycle might vary, layaway can still be workable, but you should prioritize a policy with clear grace periods or flexible payment options—if offered. If the program requires exact dates with no extensions, you may be taking on avoidable risk.
Uncertain income can be unpredictable due to overtime changes, commission work, variable schedules, medical issues, or unexpected expenses. When you’re uncertain, the critical layaway question becomes: “What happens if I miss a payment?” If missed payments result in cancellation, losing the reservation may also mean losing some portion of your money depending on refund and cancellation rules. That’s why policy clarity becomes more important when your financial rhythm is less stable.
To use layaway with uncertain income, you should consider:
Another strategy is to start with a shorter layaway duration, if available. Shorter durations reduce the number of deadlines you must meet and can lower total risk—assuming you can still afford the installments.
In retail operations, “supplier” can refer to the manufacturer, wholesaler, or inventory source used by the store. For layaway buyers, the relevance of supplier details often appears indirectly—through availability, hold policies, and whether the retailer can replace an item if the supplier cannot fulfill the exact unit.
Before placing an item on layaway, a prudent shopper asks:
This is especially important for electronics, tools, and products with model-specific accessories, where substitutions may not match the features you intended to buy. For instance, power tools might have different battery systems. If the substitute uses a different battery platform, you might end up needing new accessories to use it. Similarly, medical devices or specialized tools may require specific parts or compatibility.
Even for everyday items, suppliers matter. If a supplier changes packaging, colors, or included items, the “equivalent” replacement might not satisfy your expectations. If you need a specific brand name, compatibility detail, or packaging configuration, don’t rely on assumptions—confirm what is reserved and what can be substituted.
Retailers may advertise installment amounts, but your decision should be based on the full “effective cost.” That means looking beyond the base price and understanding any fees, deposits, and potential adjustments.
By calculating all components, you can compare layaway fairly against alternatives like debit budgeting, credit installment plans, or savings-based purchasing. A helpful approach is to compute three totals:
This “complete, cancel, change” model gives you a more realistic view of the plan’s financial risk. Many people only think about the total cost if everything goes well. But layaway’s defining uncertainty is what happens if you do not reach “everything goes well.”
It’s also worth comparing to a savings alternative: if you were saving the deposit plus future installments instead of paying them to a retailer, you might earn interest (depending on your situation) or at least maintain flexibility. Layaway can still be beneficial if your budget discipline would be difficult without the structure, but you should be aware you are trading some flexibility for reserved inventory.
Layaway is often marketed as a budgeting tool, but it can become costly if you cannot complete the plan. The very important “risk map” elements are:
An objective approach is to assume cancellations may not be fully reimbursed. Treat the deposit and early payments as “at risk” until you confirm the refund policy in writing. That mindset helps you decide whether layaway is compatible with your financial stability.
Missed payments often happen for reasons that feel small at the time—forgetting a date, underestimating the time needed to travel, a bank issue, or temporary cash constraints. In strict layaway policies, missing a payment can trigger cancellation even if you were otherwise on track. That means the retailer’s consequence is not only about money; it’s also about losing the reservation, meaning the item might be sold to someone else or substituted with a different model.
To navigate missed payments, ask and document:
Think of layaway as requiring two types of compliance: payment compliance and procedural compliance. Payment compliance means paying the correct amounts. Procedural compliance means following the retailer’s process (keeping receipts, meeting deadlines, and contacting the store when needed). If either one is ignored, consequences may follow.
Layaway practices can feel culturally familiar in local retail environments where shoppers frequently visit nearby stores for household essentials, seasonal items, or seasonal upgrades. In “nearby” communities, the practical difference often comes from how consistently staff apply the policy and how quickly you can make payments and pick up on schedule. If the retailer’s hours are limited or if customer service is harder to reach, your plan should account for travel time, payment cutoffs, and pickup logistics—because layaway success depends on follow-through.
When you live far from a retailer, layaway can be riskier for logistical reasons. For example, you might need to travel to make each payment, meaning you have to plan time and transportation every month. If you miss a payment because you couldn’t get to the store or because the store’s hours changed, the plan can be canceled. In that case, layaway’s administrative requirements become a real barrier to completion.
To reduce logistical risk, you can:
Also consider local practices around holiday shopping. During peak seasons, stores can face higher customer volumes, and the time needed to process payments or pickup might be longer. That affects whether you can meet deadlines. If your pickup deadline falls on a date when the store is short-staffed, you may need to schedule slightly earlier or ensure you have enough time for processing.
While layaway terms vary, reputable retailers tend to offer transparent documentation. A strong sign of operational reliability is that the layaway agreement includes clear details about:
From a consumer-protection standpoint, clarity helps reduce disputes. If a retailer cannot or will not provide written terms, consider it a red flag for planning certainty. Layaway agreements should typically include the installment schedule and the rules governing what happens if you cancel or miss payments. If the store’s staff provide answers only verbally or inconsistently, you may face an unfair outcome later if there’s disagreement about policy interpretation.
Trust is not just about promises; it’s about systems. Reliable retailers usually have staff who can explain layaway steps clearly and who can locate your account or payment record. They might also provide receipts for each payment and confirm your updated balance. In contrast, stores with weaker processes may lose records, misapply payments, or communicate deadlines poorly. Even if they intend to be helpful, weak systems create risk.
Before you begin, you can ask for a copy of the written terms and confirm where to direct questions. If there’s a phone number, email address, or customer service desk, note it. If the retailer uses an in-store kiosk or offers a receipt printout, ensure you receive documentation.
Another trust-related consideration is how the retailer treats substitutions. A reputable policy will describe substitution rules in a way you can evaluate: what types of substitutions are allowed, how pricing is handled if the substitute is higher or lower cost, and how you are notified. If substitution rules are vague, you may end up with an item that you didn’t actually plan to buy.
Because layaway policies are retailer-specific, consumer expectations should be built from official guidance and general consumer-protection principles. For broader legal and regulatory context on retail consumer rights in the U.S., the U.S. Federal Trade Commission (FTC) provides general consumer protection resources. For understanding payment practices and business transparency principles, consumers can also consult guidance published by consumer protection agencies.
Even when you’re not dealing with a credit product, disputes can still occur around refunds, missing payments, or misunderstanding cancellation rules. That’s why documentation—receipts, written terms, and clear communication—matters. While consumer protection frameworks differ by jurisdiction, the general principles often overlap: clear disclosures, fair treatment, and the ability to resolve disputes when policies are not followed.
No. “Buy now, pay later” products typically relate to third-party installment or credit arrangements, while layaway is usually a retailer-managed reservation with scheduled payments until the item is secured for pickup or transfer.
In other words, with layaway you are generally paying into a specific reservation at the retailer. With many “buy now, pay later” plans, the purchase may occur immediately and you then repay under a structured installment agreement. That difference affects risk: with layaway, the big risk is often losing the reserved item if you don’t complete payments; with credit-based arrangements, the big risk may include repayment obligations even if you don’t receive the item as expected.
Deposit requirements vary by retailer and sometimes by product category. The very reliable approach is to ask for the exact deposit and confirm whether it is refundable under specific cancellation conditions.
Deposit refundability is not always intuitive. Some retailers may treat the deposit as a refundable amount minus administrative costs; others may treat the deposit as part of the payment stream that can be recovered only if you cancel within a certain time window. Always ask what portion, specifically, could be forfeited.
Often you can, but cancellation terms differ. You may receive a partial refund and may be charged administrative or restocking fees. Review the written policy before starting.
When cancellations occur, the retailer may also reassess inventory costs. For example, if the item is returned to stock and sold to someone else, the retailer may have to reverse or update the reservation. The administrative fees that protect the retailer’s process are often what reduce your refunded amount. If possible, evaluate whether you could finish the plan under realistic constraints before committing.
Policies vary. Some plans include grace periods; others may cancel the reservation after a missed payment. Ask about reinstatement options and whether late payments can be caught up.
When you miss a payment, speed matters. If you discover the missed installment quickly and can pay immediately, some retailers can reinstate the plan under their policy. Others may treat the reservation as ended regardless of how quickly you correct. A written policy is particularly important here, because it prevents “we can make an exception” surprises.
Not automatically. Ask whether the retailer locks in the price and whether it reserves the specific model (especially for electronics and appliances). Also confirm substitution rules if the original item is unavailable.
Price lock matters particularly during promotions. If the plan spans beyond the promotional period, ask whether the retailer will honor the original advertised price or whether you could be required to pay more. Likewise, model lock is important for products where specifications differentiate value or compatibility.
Sometimes. Many retailers include a plan fee or apply charges related to holding inventory. Confirm all fees upfront so you can compute the true total cost.
Also confirm whether fees are charged only when you begin, or whether they can continue to apply until completion. If storage fees apply, the longer your plan lasts, the more those fees could add up. If you cancel late, the refund might be reduced by those same fees.
There is usually a deadline after which the reservation expires. The exact length is retailer-specific, so confirm the completion timeline and pickup window in writing.
Some plans might be tied to seasonal calendars or inventory cycles, especially during high-demand periods. The practical lesson is that layaway success depends not only on completing payments but also on meeting the entire timeline through pickup and final processing.
Typically you’ll need proof of payments and identification if required by the retailer. Keep receipts or confirmations for each installment to simplify pickup.
If your layaway agreement was in your name, bring identification that matches the agreement. If someone else is picking up the item for you, ask whether they need written authorization. If the retailer provides a pickup receipt or layaway claim number, keep it accessible.
Not necessarily. Some retailers restrict eligible items (for example, certain clearance or nonstandard inventory). Ask which product categories are eligible.
Eligibility can also be impacted by inventory status. Some stores may not place a high-risk item on layaway if it’s likely to move quickly or if it’s subject to special handling. If you’re attempting to reserve something that’s already marked down, ask whether layaway is allowed and whether the discount is preserved.
Compare effective total cost (including fees), risk (refund/cancellation terms), and convenience (payment deadlines, store hours, and pickup timing). If a layaway plan has strict deadlines with unclear refund rules, it may carry more risk than it appears at first glance.
When comparing, don’t only compare monthly payment amounts. Compare the worst-case scenario too: how much money could you lose if you must cancel? Some alternatives, such as budgeting and saving, might take longer but offer full flexibility. Others, such as credit installments, might offer more immediate purchase rights but introduce interest or credit risk. The “best” choice depends on what risks you can manage and what tradeoffs you’re comfortable with.
Layaway can be a practical way to reserve an item while paying over time, provided you approach it with clarity and discipline. The very reliable outcome comes from verifying total cost, understanding conditions, and planning around deadlines. When you treat the agreement like a real contract—reading fees, cancellation rules, and missed-payment consequences—you turn layaway into a structured purchasing method rather than an uncertainty you hope will work out.
Consider layaway a tool that rewards preparation. If you can track your payments, understand the cancellation and refund rules, and ensure you can complete both the payment schedule and the pickup timeline, layaway may help you achieve your purchase goal without relying on credit approvals or full upfront payment. If your situation is unpredictable, you may still be able to use layaway, but you should choose a policy with clearer grace periods and more forgiving missed-payment terms, and you should start only after you know what money is at risk.
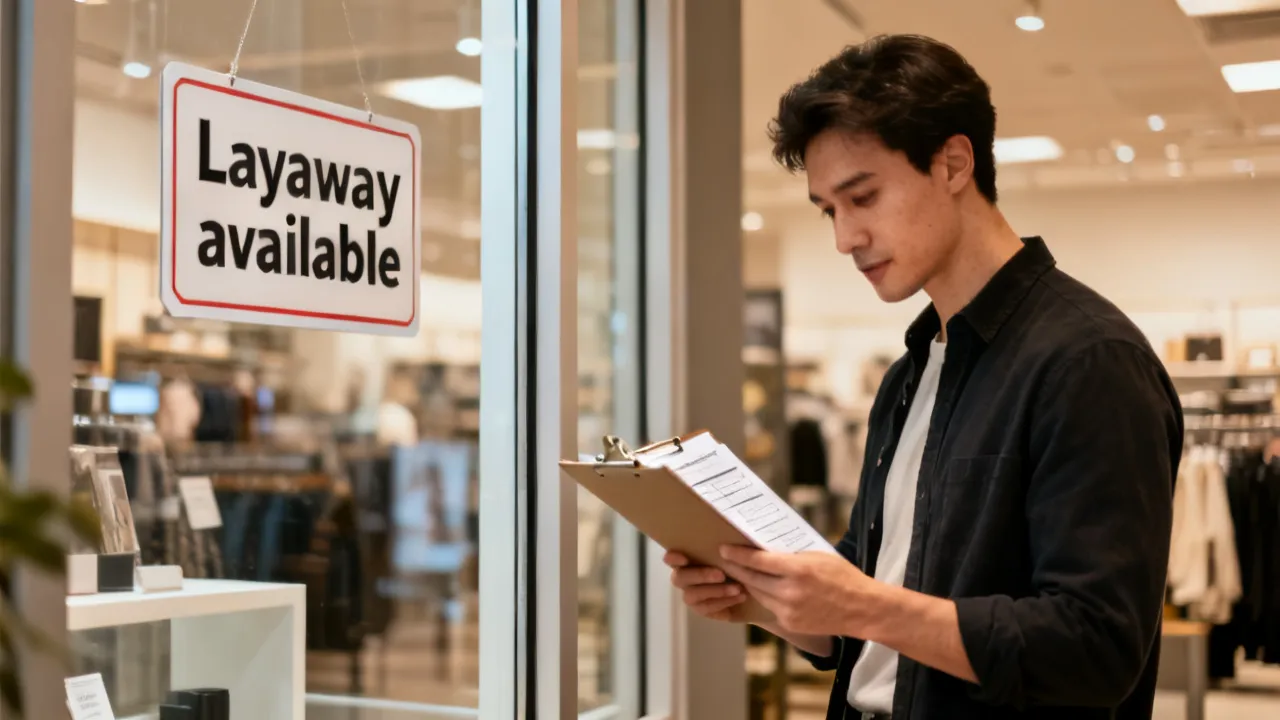
Cover prompt recap: A professional photo-style image showing a “Layaway available” storefront sign, a customer reading reservation terms, and a neutral, trustworthy retail atmosphere with no brand logos.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Pet Insurance Essentials: Coverage, Costs, and Resources Explained
In recent years, pet ownership has seen a significant surge. Pets, whether they're dogs, cats, birds, or other animals, have increasingly become integral parts of our families. With this growing bond, there is a rising awareness of the importance of pet health and well-being. Just as health insurance is crucial for humans, pet insurance is becoming an essential consideration for pet owners. This article aims to provide a comprehensive understanding of pet insurance, covering its importance, types of coverage, associated costs, and valuable resources to help you make an informed decision.
Colbate Explained: Uses, Sourcing, and Top Practices
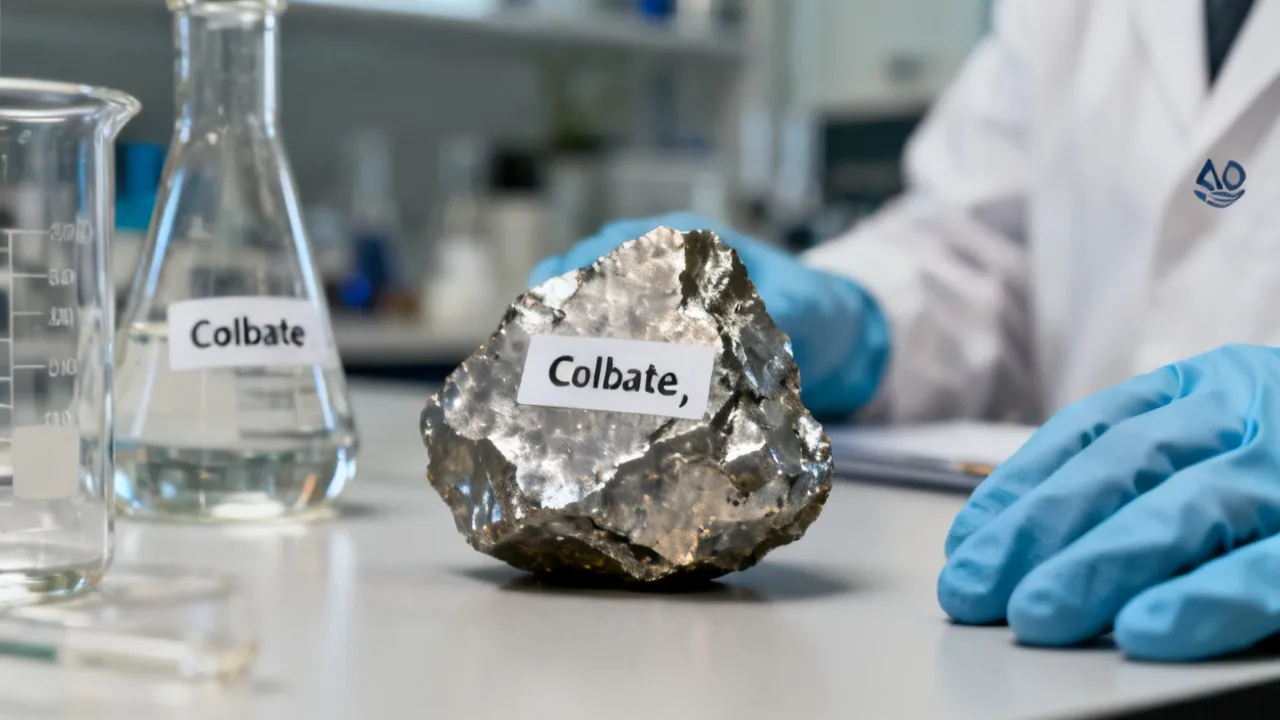
This guide explains Colbate from a practical industry viewpoint, covering what it is, how suppliers typically handle it, and what buyers should verify before purchase. It also summarizes objective background on related terminology, common application considerations, and due-diligence steps. Readers will find a comparison table, requirements, and targeted FAQs to support confident sourcing decisions.
Strategies for Financial Security and Legacy Planning
Life insurance isn't just about what happens after you pass—it's a strategic tool in a comprehensive plan for your financial security and estate planning.
Navigating Insurance Costs for Seniors: Essential Tips and Advice
As we age, healthcare costs and the complexity of managing them can become increasingly burdensome. For many seniors, navigating insurance costs is a crucial aspect of ensuring financial stability and maintaining health. This guide aims to provide you with essential tips and advice on how to manage and potentially reduce these costs effectively.
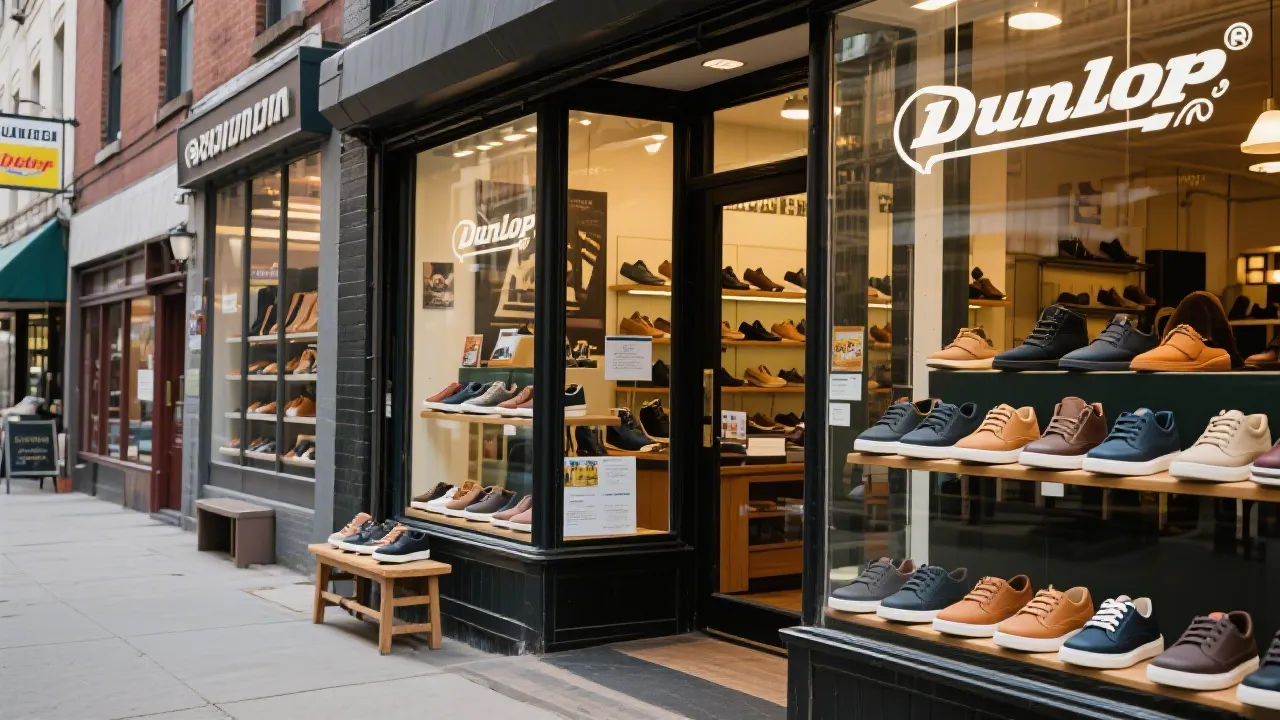
Discovering Dunlop Brooklin Footwear
This article delves into Dunlop Brooklin, a prominent name in the footwear industry known for its exceptional quality and innovation. Dunlop is recognized for its wide-ranging collection of shoes designed to meet diverse customer needs, from casual wear to professional attire. This guide provides an in-depth analysis of Dunlop Brooklin and its offerings, revealing why it stands out in the market.
Your Guide to Understanding Car Insurance Coverage
Navigating car insurance can be puzzling. Fortunately, this guide illuminates coverage types and choosing the right provider.
