This guide explains how to evaluate Paychex 401k offerings alongside Fidelity-related plan options, with a focus on what participants should check before making decisions. Background sections provide an objective overview of how 401(k) plan administration, recordkeeping, and investment lineups generally work, and why payor/administrator relationships can affect plan access and service workflows.
When you’re reviewing a Paychex 401k Fidelity setup, the very important step is to verify how your specific plan is administered and which party controls each part of the experience—recordkeeping, investment menu, and participant support. Even if your employer uses Paychex for payroll and benefits administration, your plan’s investments and account services may follow a distinct structure. Your goal is clarity: confirm what you can trade, where contributions land, which fees apply to which layer, and how support works when you need help.
In practical terms, focus on these high-priority checkpoints: (1) your plan’s recordkeeper and investment lineup, (2) the fee disclosure sections for both plan-level and fund-level costs, (3) any eligibility and enrollment rules, (4) the distribution and rollover process, and (5) the service channels for transactions and account questions. If you keep these items straight, you’ll avoid “assumptive” decisions that can happen when plan branding is confusing.
Additionally, it helps to remember that retirement plans can be “branded” in multiple ways. One vendor may appear on one screen, another on a statement, and a third may show up in investment materials. Those names may reflect different contracts for different responsibilities. Your decision should be based on the plan’s contractual reality—what the plan document and fee disclosure actually say—not on the marketing or the order in which names appear.
Because 401(k) outcomes depend heavily on process (how quickly trades occur, what happens when you request a withdrawal, whether loans are permitted, how match is deposited and when it vests), it’s worth spending time on verification before you commit your ongoing contributions. For many participants, “thinking ahead” prevents painful surprises later—especially around rollovers, loan repayments, and situations where you change jobs or need money before retirement.
The phrase Paychex 401k Fidelity often appears in conversations about retirement accounts because many employers select multiple vendors for different responsibilities. Paychex is commonly associated with payroll and benefits administration. Fidelity, on the other hand, is frequently discussed in connection with retirement-plan recordkeeping and investment management. However, in real plan design, the “Paychex” part and the “Fidelity” part may not map 1:1 to a single operational function for the participant.
From an industry perspective, a 401(k) program can involve several components:
Because these functions can be split across vendors, your experience may depend more on the recordkeeper and fund platform than on the payroll/benefits administrator name. That’s why your top starting point is always your plan’s official documents and the disclosures that govern your account.
To make this idea concrete, imagine three different “views” of the same plan:
These views can all be accurate. They’re not competing stories; they’re different layers of the same system. Your job is to identify which layer matters for the decision you’re trying to make.
For example, when you decide which funds to invest in, you primarily care about the recordkeeper platform and the investment menu it provides. When you decide how quickly your payroll contributions start investing, you care about the administrative and recordkeeping integration (and the plan’s contribution timing rules). When you decide what happens to your money when you leave your job, you care about the distribution and rollover process in the plan’s document and the support channel used for those transactions.
To make an informed decision in a Paychex 401k Fidelity context, prioritize what affects outcomes immediately and directly. Lower down in this article, you’ll find supplemental comparison tools and conditions/requirements. For now, here’s what should be top-of-mind.
Participants sometimes assume that the payroll administrator is the same entity providing the investment account portal. In many employer arrangements, the recordkeeper is the organization that produces your quarterly statements and hosts the main participant website or app. Look for the entity named in your account statements and fee disclosures. If Fidelity is the recordkeeper for your plan, that should be explicit in the materials you receive.
Why this matters: recordkeeping determines transaction processing speed, fund availability, distribution workflow, loan rules support, and the path you take when you need to correct contribution issues.
It also determines where you’ll navigate “life events.” For example:
To confirm the recordkeeper, use more than one clue. Don’t rely only on what you see on a pay stub or in an HR benefits email. Instead, cross-check three documents:
401(k) fee transparency is not a “top effort”—it’s regulated and disclosed through specific disclosures, including information that helps participants understand both plan-level and investment-related costs. Your decision quality improves when you separate:
For reliable context on what disclosures exist and why they matter, the following sources are frequently used in compliance and participant education: the U.S. Department of Labor’s retirement plan guidance and participant resources, and regulatory fee disclosure requirements under ERISA.
Professional note: avoid judging a plan based solely on the vendor brand. Two “similar-sounding” setups can have different fund menus, different expense structures, and different administrative fee arrangements.
When you review fees, treat the “total cost” concept seriously even if you don’t have a perfect apples-to-apples comparison. Participants often get misled by a single number (like an expense ratio you see in a mutual fund listing) without considering plan-level expenses that may reduce account value indirectly.
To organize your review, you can break fees into three questions:
Even if you ultimately don’t change anything, reviewing fee disclosures helps you understand whether the plan’s design creates unnecessary friction between you and your long-term goals.
A retirement plan’s value is not only in who administers it—it’s also in the available investments and the ability to implement a strategy (diversification, rebalancing, and contribution discipline). In a Paychex 401k Fidelity environment, the investment menu you can access is the critical element you should validate in your plan materials.
As an industry expert would frame it, you should identify whether your options include:
Then compare those options to your timeline and risk tolerance, remembering that diversification and discipline typically matter more than short-term returns.
To make this step more practical, it can help to translate the menu into “usable building blocks.” For many participants, a good plan design gives at least two layers of building blocks:
Also, check how the plan’s lineup handles international exposure, bond options, and any sector-specific funds. Many plans offer too much overlap in overlapping index funds (which can be fine but may limit diversification if you end up concentrating). Other plans offer a very limited set that can make it difficult to maintain an appropriate risk level without using a target-date fund.
One more key nuance: some recordkeepers also offer “manager research,” model portfolios, or glidepath educational information. Those features might appear in the interface, but your real investment freedom is determined by what the plan allows. Always align what you see in the portal with the official fund lineup documents.
Finally, confirm whether automatic enrollment uses a specific default investment. If your employer uses an automatic default, you should know exactly what it is—because those contributions might be invested differently than what you would choose personally.
In many plans, employer contributions (including matching contributions) are conditional. Even if the “Paychex 401k Fidelity” relationship is clear, the plan’s matching policy is what ultimately affects your effective compensation.
Confirm:
Match mechanics are often misunderstood because participants focus only on the percentage match and ignore the fine print. But the “fine print” can determine whether you capture the full match.
When reviewing match terms, consider these additional details:
If your plan provides a match that vests over time, consider whether your job stability aligns with the vesting schedule. Even for participants who are “only passing through,” taking advantage of the match can still be worthwhile—but you should model it realistically.
Participants often learn about distributions only when they need them. Instead, review the plan’s rules earlier. Distribution and rollover mechanics can differ by plan document, and recordkeeping workflows matter in real time.
Key points to validate include:
For those who relocate or change employers, getting the mechanics correct can reduce delays and avoid avoidable tax or processing complications. Always follow the plan’s official instructions.
It’s particularly important to review rollover mechanics before you leave a job. Participants sometimes assume that any transfer is the same. In reality, a direct rollover can protect you from withholding-related issues, while an indirect rollover might introduce additional paperwork and tax complexity. Your plan’s distribution guide or SPD typically describes the process and the required forms.
Also, evaluate the participant experience for distributions:
Similarly, check loan rules as part of an overall “contingency plan.” Some plans allow loans but restrict how you can use them, limit the number of loans, or impose repayment rules that can trigger taxable events if you miss payments or end employment. Understanding these rules earlier reduces the risk of unexpected tax consequences.
Even when Paychex 401k Fidelity appears to describe a single relationship, treat it as a clue rather than a final answer. The step-by-step review below is designed to help you build a factual understanding of your plan—what it does, who does what, and what it costs.
This method reduces reliance on secondhand descriptions and aligns your plan decisions with the governing paperwork.
To further improve this review, consider building a “one-page plan facts sheet” for yourself. You can capture the following items after you check documents:
That “facts sheet” becomes especially helpful if you need to troubleshoot errors or coordinate with an IRA provider later.
Because vendor roles may differ, it’s useful to evaluate “administrator-like” functions and “recordkeeper/investment platform-like” functions separately. The table below avoids assumptions and frames the very common participant-facing differences you should confirm in your plan documents.
| Category to Verify | What to Look For | Why It Impacts You |
|---|---|---|
| Recordkeeping identity | Name of the company issuing statements and processing account transactions | Determines your main account portal, trade timing, and support routing |
| Investment menu and share classes | Fund names, fees/expense information, and any platform-specific access constraints | Directly affects ongoing costs and your ability to diversify |
| Contribution flow | How payroll deductions are transmitted and when investments are applied | Impacts whether your deferrals are invested promptly |
| Employer match implementation | Match formula, vesting schedule, and timing of match deposits | Changes your effective return and the value of staying enrolled |
| Fees and fee sources | Plan administrative expenses vs fund-level expense ratios as disclosed | Helps you avoid “brand confusion” and measure total cost |
| Loans and withdrawals | Loan availability, eligibility standards, repayment rules, and rollover procedures | Determines your options if you need funds or change jobs |
| Participant service routes | Whether you contact the administrator or the recordkeeper for each type of request | Reduces delays when fixing contribution errors or executing transactions |
As a best practice, you can also capture the “routing map” for yourself—what to contact for what. For instance:
This “routing map” can save hours of back-and-forth during stressful moments, especially when you have a deadline (like a separation date or distribution timeline).
In the employer retirement-plan ecosystem, payroll and benefits administration providers often integrate with recordkeeping platforms so that employee eligibility and payroll contributions flow into the retirement account correctly. In some arrangements, employees see both vendor names because different portions of the workflow are branded or communicated through different channels.
From a professional standpoint, it’s normal for participants to encounter multiple names—particularly during enrollment, when disclosures are prepared, or when statements show different entities. The meaningful question is not which brand appears where, but what each entity is responsible for under the plan documents.
For objective and compliant background on participant rights and plan disclosure expectations, the U.S. Department of Labor provides educational resources that describe how retirement plans are governed and what information participants should receive. For fee disclosure structure and fiduciary considerations, participants are commonly directed to official regulatory materials and ERISA-related guidance. (Always rely on your plan’s own documents for your specific plan terms.)
It’s also useful to understand that plans can change vendors. Vendor transitions happen when an employer rebids contracts, changes payroll systems, or upgrades service arrangements. During a transition, your experience can temporarily shift—login credentials can change, statements may show a transition period, and processing timelines can be slightly different.
If you suspect your plan is in or near a transition, check notices from your employer or recordkeeper. Those notices usually explain:
Knowing this in advance reduces frustration if you submit an investment change and it appears delayed or processed after a transition window.
Below is a concise list of requirements and “conditions to confirm” that commonly apply when participants enroll, update contributions, or make account changes in a Paychex 401k Fidelity context. Your plan may vary; use your own plan documents to validate each item.
To make the checklist even more useful, you can turn each item into a question you ask during onboarding or when you encounter confusion. For example:
These “operator-level” questions push you toward the correct documentation and reduce the chance you misunderstand basic processing rules.
Not necessarily. Paychex is often associated with payroll and benefits administration workflows, while the recordkeeper is typically the entity that maintains the participant account, processes trades, and issues statements. In a Paychex 401k Fidelity context, your plan documents should explicitly identify the recordkeeper.
Look at your quarterly statements, plan fee disclosures, and the disclosures provided during enrollment. These documents usually name the recordkeeping platform and the investment providers or fund lineup used in your plan.
If Fidelity is not the recordkeeper, you might still see Fidelity in educational materials, in association with certain investment options, or as a vendor involved in one part of the plan. But the recordkeeper name on statements is the key indicator for where transactions and account access happen.
Start with the fee disclosures that separate plan-level expenses from fund-level costs (e.g., expense ratios). Your top reference is the official fee information provided to participants, not assumptions based on vendor branding.
Also consider reviewing whether there are any additional fees that aren’t reflected in expense ratios, such as loan-related fees or distribution processing fees. These can vary by plan design and sometimes surprise participants who assume costs are only the fund expense ratios.
Not always. Many plans process investment trades on a set schedule (e.g., next business day or next available valuation window). The plan’s trading and processing rules should be stated in participant materials.
Because contribution timing and trade timing can be different, you may want to confirm how investment instructions are handled for:
Often, yes—but the timing and method matter (direct rollover vs. indirect rollover). Your plan’s distribution and rollover section in the SPD or distribution guide will describe requirements and any forms you must complete.
Also confirm whether the plan requires you to use specific forms and whether it supports direct rollovers in a straightforward way. If you’re planning to move money, collecting your receiving IRA’s information early can reduce delays.
No. Loan availability depends on the specific plan document. If loans are allowed, additional conditions such as repayment terms and what happens upon employment termination will apply.
When loans are permitted, it can also be useful to check whether interest is charged to your own account and how that affects your effective cost of borrowing (for many participants, the “cost” is the opportunity cost plus any fees, not a separate interest expense to the lender like a traditional bank loan).
Use a “factual comparison” rather than a brand comparison: confirm recordkeeper identity, review disclosed fees and investment options, understand employer match and vesting, and verify distribution/loan rules. This approach works regardless of whether you see both Paychex and Fidelity names in communications.
After you confirm the operational details behind Paychex 401k Fidelity, you can focus on strategy. From an industry lens, strategy typically rests on four pillars: contribution level (including match capture), investment allocation (diversification), cost awareness (fee structure), and ongoing discipline (rebalancing and staying invested through market cycles).
To make this actionable, consider the following planning behaviors:
These behaviors are not dependent on the administrator brand—they depend on the plan’s actual offerings and terms.
To expand the strategy discussion in a “participant-friendly” way, you can think of the plan’s mechanics as setting constraints and the investment strategy as setting your goals within those constraints.
1) Contribution level: Your match is often the most immediate “return” in your 401(k). Many participants benefit from at least contributing enough to capture the full employer match, if the match is offered and if they can comfortably afford the employee deferral.
However, match capture should be balanced with other priorities. For example, if you’re paying high-interest debt or lacking emergency savings, your financial stability might be improved by addressing those first. There’s no universal rule, but understanding the plan mechanics helps you make an intentional decision.
2) Investment allocation: Many plans include a set of diversified funds. Your task is to match your allocation to your risk tolerance and time horizon. Younger participants may be better positioned to take more equity risk, while participants nearing retirement may prefer greater stability.
Because your plan might offer a target-date series, an alternative strategy is “set-and-review”: choose a target-date fund and then rebalance only as needed by reviewing whether the selected fund still aligns with your expected retirement timeline.
3) Cost awareness: Even if your plan isn’t the lowest-cost option, you can still make cost-sensitive decisions within the lineup. For instance, if you have access to index funds at reasonable expense ratios, those may reduce drag compared with more expensive actively managed options. But always check for share classes and ensure you’re comparing the same type of fund.
4) Ongoing discipline: Investing discipline is often more powerful than predicting short-term returns. If you implement a diversified allocation, then maintain regular contributions and periodic rebalancing, your outcomes improve through consistency.
Also consider plan features. Some plans offer automatic rebalancing, automatic escalation of contributions, or online modeling tools. Even if these features are not part of the core mechanics, they can reduce “behavioral risk”—the risk that you stop contributing or drift away from your intended allocation.
Finally, keep in mind that 401(k) investing isn’t only about choosing funds. It’s also about avoiding transaction errors, missed enrollment deadlines, and misunderstandings about trade timing. Understanding the plan’s processing rules can prevent avoidable mistakes.
If your enrollment documents don’t clearly explain how the Paychex 401k Fidelity arrangement works, ask targeted questions. The very effective requests are the ones that lead to verifiable documents. Examples include:
When you ask these questions, you steer the conversation toward plan documentation, which is the very reliable source for decision-making.
It can also help to ask for “process documentation” rather than only policy statements. For example:
Another useful request is a “participant support routing guide” if it exists. Some employers provide a simple document that clarifies whether participants should contact HR/payroll or the recordkeeper for specific issues. If such a guide isn’t available, you can still ask the administrator to confirm the correct routing for your most common needs.
Finally, keep a timeline for your own records. If you make changes (contribution amount, investment allocations, beneficiary updates), document the date/time and confirm you see the change in the portal. This “transaction log” approach can be a lifesaver if you later need to reconcile discrepancies with support.
For objective background on retirement plan governance, participant disclosure expectations, and fiduciary-related guidance, refer to U.S. Department of Labor resources on ERISA and retirement plan information. For fee disclosure structure and compliance framing, review official regulatory guidance tied to ERISA participant communications. Always rely on your employer’s plan documents (SPD, plan summaries, and participant fee disclosures) for your exact terms, investment menu, and operational workflows.
Note: Any employer-specific “price” references (such as plan administrative fee amounts) can vary widely by plan design, participant count, and negotiation terms. In a Paychex 401k Fidelity context, the only accurate way to assess costs is to use the fee information included in your plan’s official disclosures.
In addition to official plan documents, you may use your own account data to validate what’s happening in practice. For example, compare the timing of payroll contributions posted in your account versus the trade date rules stated in the plan materials. Small differences can be normal due to processing cycles, but large or repeated discrepancies may indicate an operational issue worth reporting.
If you receive notices during plan transitions, keep them. Those notices often provide the only “ground truth” for how trades, statements, and participant access work during those windows.
Understanding Paychex 401k Fidelity is less about identifying a single vendor and more about verifying the functional layers that affect your account: recordkeeping, investment access, fee structure, employer match, and distribution rules. By using the checklists and comparisons in this guide—then validating every claim against your plan documents—you’ll be positioned to make decisions grounded in the actual terms of your retirement program.
The most practical mindset is simple: treat vendor names as “clues” and plan documents as “proof.” Once you know who is responsible for what, you can focus on strategy with confidence—capturing match opportunities, choosing appropriate investments, and understanding what happens when life events require withdrawals or rollovers. That approach reduces uncertainty, improves decision quality, and helps protect your retirement savings from preventable process errors.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Exploring the Retipster Club Advantage
The Retipster Club is an invaluable resource for real estate investors, offering a plethora of insights, tools, and community support to boost investing endeavors. Aimed at helping both novice and seasoned investors, the club provides educational materials, success stories, and expert strategies tailored to the ever-evolving real estate market landscape. Dive into this analysis to understand the manifold benefits the Retipster Club offers to enhance real estate success.
Navigating the Retipster Club
This article delves into the unique offerings of the Retipster Club, a community designed for individuals interested in real estate investment, providing educational resources and networking opportunities. Discover how the club supports its members through expert advice, comprehensive guides, and a robust community platform, all tailored to foster insightful and profitable investment strategies.
Pmoc Abrava: Practical Procurement and Quality Considerations
This guide explains how to approach Pmoc Abrava procurement with a quality-first, compliance-minded process. “Pmoc Abrava” is discussed as a term used in sourcing contexts, covering typical decision factors such as specification clarity, supplier capability, documentation, and handling requirements—using an objective framework for safer purchasing, risk control, and consistent performance.
Unveiling Grunig & Hunt's PR Models
This article explores the seminal work of Grunig & Hunt in developing models of public relations. The Grunig & Hunt models, fundamental to understanding PR theory, provide insight into the strategic approaches and methodologies utilized in the field. Each model offers a distinctive perspective on communication and engagement strategies, relevant to both academic discussions and practical applications.
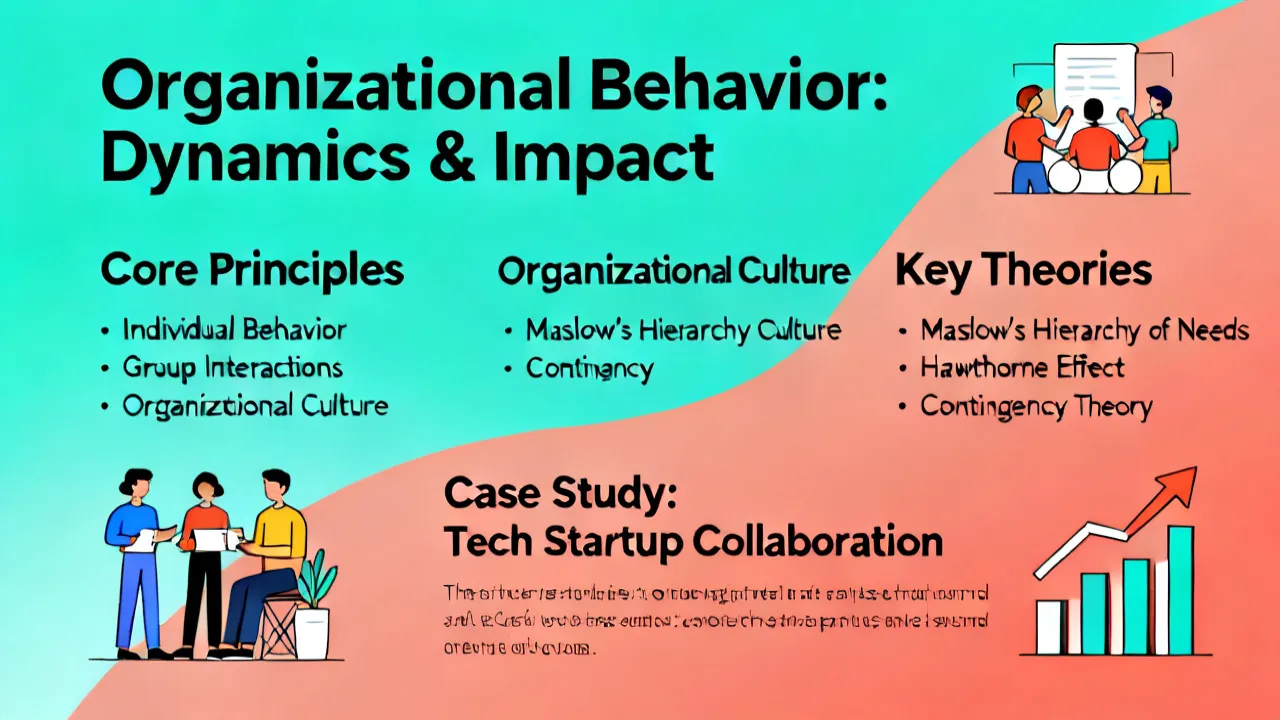
Understanding Organisational Behaviour Slideshare
This article delves into the significance of Organisational Behaviour Slideshare for both educators and professionals. Organisational Behavior is a field that examines the impact individuals, groups, and structures have on behavior within organizations, aiming to improve an organization's effectiveness. With Slideshare's platform, these insights are easily shared, promoting a collaborative learning environment.
Understanding Ltda Epp for Supplier and Compliance Decisions
Learn how “Ltda Epp” impacts supplier selection, contract structure, and compliance planning. This guide explains, in objective terms, what the label typically signals in company registration and how it can affect procurement processes, risk checks, and document readiness. It also frames practical conditions, comparison points, and decision steps to help you evaluate suppliers with clarity and consistency.
