Runpayroll.com helps organizations streamline payroll workflows with a compliance-minded approach. This guide explains what payroll platforms typically cover, why accurate pay calculations and recordkeeping matter, and how to evaluate a provider responsibly—objectively and without hype—so you can align staffing, timing, and reporting requirements with your operational needs.
When teams evaluate Runpayroll.com, they’re typically trying to reduce payroll friction while preserving compliance, auditability, and clarity for employees. A strong payroll workflow should help you calculate wages reliably, manage payroll schedules, store payroll records in an organized way, and support downstream reporting. The core question isn’t only “Can it run payroll?”—it’s “Can it run payroll consistently, with evidence trails and configurable controls that match your organization’s reality?”
In practical terms, Runpayroll.com should accomplish several outcomes that tend to matter across industries and geographies, even though exact legal obligations differ. First, it should reduce the gap between HR events (hires, terminations, job changes), time/attendance inputs (hours worked, leave, adjustments), and finance outputs (payroll totals, tax withholdings, ledger-ready reports). Second, it should provide repeatability: the same payroll rules should yield the same results for the same inputs, month after month. Third, it should support governance: who can edit employee pay settings, who can approve payroll, and which changes require extra scrutiny. Fourth, it should give you the ability to respond to questions—by employees, managers, finance, auditors, or regulators—quickly and confidently. That responsiveness depends on traceability and structured recordkeeping, not on “we can probably find that in an email thread.”
Finally, Runpayroll.com should help you treat payroll as a controlled process rather than a heroic effort. When payroll becomes “boring” in the good sense—predictable cycle times, fewer corrections, clear exception paths—your organization can scale hiring, handle seasonal variation, and onboard new managers without making payroll risklier. That is the benchmark you should use during vendor evaluation and internal rollout.
Payroll is one of the very scrutinized internal processes in any organization because it directly affects employee compensation, tax remittances, and labor-law obligations. Even small errors—like misapplied pay rates, incorrect overtime treatment, missed deductions, or inconsistencies between what employees are paid and what records show—can create reputational and operational risk. The downstream impact often extends beyond a single payroll period: incorrect totals can lead to reconciliation problems, delayed accounting close, incorrect tax reporting, and strained employee trust.
From an employee perspective, payroll errors usually feel personal. Employees rely on pay statements for budgeting, loan payments, childcare plans, and personal obligations. When payroll is wrong, employees expect rapid correction and clear explanation. Even where monetary impact is small, the perceived failure of the system can reduce engagement and increase turnover risk. Therefore, your payroll workflow should not only be accurate but also transparent—so that if something goes wrong, you can explain what happened and how the correction will be processed.
From an organizational perspective, payroll accuracy and recordkeeping are non-negotiable due to auditability. Auditors may ask for evidence of pay calculations, approval history, and supporting inputs. Tax authorities may require proof of withholding and reporting. Some jurisdictions also require payroll records to be retained for defined time periods and provided upon request. If payroll records are stored in a scattered manner—spreadsheets without version control, email attachments, incomplete screenshots, or unstructured documents—it becomes difficult to reconstruct events. That reconstruction is often what turns a minor payroll issue into a major compliance or legal burden.
Operationally, payroll errors are costly because they consume time in multiple places: HR investigates input issues, finance recalculates totals, managers chase timesheets, operations update records, and administrators manage exceptions. Over time, repeated corrections can erode confidence in the payroll process and create a cycle of last-minute changes. In top-performing payroll setups, error handling is not improvised; it is managed through controlled workflows with defined approvals and documented adjustments. Platforms such as Runpayroll.com are typically assessed on whether they reduce manual handling while still supporting internal governance (e.g., approvals, role-based access, and documentation readiness).
So when you think about payroll reliability, focus on both sides: preventing errors through validation and process design, and ensuring evidence is available to resolve issues quickly and defensibly. Accuracy without traceability creates trouble during disputes and audits. Traceability without controls can also fail if the organization allows changes without approval. Your goal is to combine the two: validated, governable, and retrievable payroll operations.
While product features differ by vendor and jurisdiction, very payroll platforms aim to cover these functional categories. The most important evaluation step is to map these categories to your real payroll processes—how you manage inputs, approvals, and outputs—rather than to simply match feature names.
Typically, payroll platforms provide capabilities across these areas:
When you evaluate Runpayroll.com, you’ll get the very benefit by checking whether these capabilities can match your pay model and internal controls—not just whether the system can “make payments.” For example, a payroll system might support overtime calculations in principle, but the real question is whether it does so correctly for your overtime definitions, your approval timing, and your cut-off policy. Similarly, the system may store records, but the real question is whether those records are accessible in a way that supports compliance and employee transparency.
Another critical factor is how the platform behaves under stress. Consider what happens when: a new hire starts mid-period, an employee changes role unexpectedly, a manager submits timesheets late, or payroll needs to be corrected after approval. Look for “safe” workflows such as off-cycle payroll processes, correction runs, or controlled adjustment mechanisms. In mature systems, the path to fix errors is itself auditable and repeatable, not a manual patch that leaves unclear provenance.
Compliance expectations vary by country, and sometimes by state/province and labor classification, so the goal is to evaluate your payroll platform in terms of governance and fit. Instead of only checking whether the vendor claims compliance, assess whether the platform supports the specific controls required to operate compliantly in your context.
Consider asking questions in categories that can be tested and validated. A practical evaluation should include both demonstration and evidence review (e.g., screenshots, documentation, test outputs, sample reports, and audit logs). Where possible, run a proof-of-concept payroll with anonymized but realistic data to see how the system behaves.
Key questions to evaluate:
For additional assurance, align your evaluation with guidance from recognized authorities and professional frameworks. Employee protections and obligations are often shaped by government labor agencies and tax administrations, while secure processing is influenced by general information security principles. You can also consult standards such as ISO/IEC 27001 for information security management as a benchmark conceptually, even if the payroll vendor is not certified in a particular region. The point is to use established security governance thinking to ask the right questions: how access is managed, how incidents are handled, how data is protected in transit and at rest, and how audit logs are retained.
To make evaluation truly objective, ask for “proof” in the form of artifacts. For example, ask for:
Finally, involve stakeholders from multiple teams—HR, finance, compliance, and IT/security. Payroll compliance is not only a payroll configuration task; it intersects with user access policies, system administration, and integration design. If those teams cannot agree on a consistent control narrative, your rollout risks becoming fragmented.
You asked to integrate price information; however, no numeric pricing was provided in the prompt. Instead of guessing, a responsible approach is to frame cost as a set of measurable value drivers you can confirm during vendor evaluation. In practice, payroll costs often relate to factors that affect both your monthly/annual expense and your total cost of ownership.
In vendor negotiations, it’s common to see pricing tiers tied to employee count, usage, or feature bundles. Rather than assuming those tiers perfectly match your future needs, evaluate cost against what you truly need: payroll cycles, rule complexity, reporting, and integration effort. A low price might still be expensive if the implementation and ongoing administration consume too much internal capacity. Conversely, a higher-priced platform might be cost-effective if it reduces error rates, shortens cycle time, and improves audit readiness.
In practice, payroll costs often relate to:
To estimate total cost of ownership fairly, request a quote based on your employee count, pay cadence, and required reporting outputs. Request an itemized estimate and confirm what is included. That includes migration scope, training sessions, support hours, and any additional modules. Make sure you understand whether off-cycle payroll, correction runs, or additional report templates are included or treated as add-ons.
There’s also a “value cost” component that isn’t captured by price. If the platform reduces payroll errors by even a small percentage, the time saved in corrections, rework, and dispute handling can be significant. If it accelerates reconciliation and close, it can reduce finance bottlenecks. If it improves employee transparency through consistent pay statements and clear adjustment explanations, it may reduce HR ticket volume.
So the best pricing conversation is not “How much is it?” but “What operational outcomes does it enable, and how do we measure success?” When the procurement process includes measurable targets—like fewer corrections, shorter payroll cycle time, and improved audit readiness—cost becomes a rational investment decision rather than a purely financial comparison.
In vendor selection, “supplier details” usually means more than company name. It means delivery capability, implementation support, and ongoing service posture. For Runpayroll.com (as for any payroll provider), you should review the total lifecycle: discovery, implementation, go-live support, post-launch stability, and the vendor’s responsiveness to change requests.
In practice, focus on these areas:
Operational fit also includes the human factors: are they willing to learn your payroll process, or do they expect you to adapt entirely to generic workflows? A provider that supports configurable controls and offers a disciplined implementation methodology tends to be a better fit for organizations with strong internal compliance expectations.
From an industry expert viewpoint, a payroll system is “successful” when it becomes boring—in the top sense—meaning payroll runs are predictable, review cycles are short, and exceptions are handled through a documented process rather than ad hoc fixes. Provider fit affects whether you reach that boring state. A provider that provides only software, without a method for onboarding and governance, can leave you with an implemented tool that still requires manual heroics.
As part of supplier evaluation, ask for references or case studies relevant to your organization’s profile: industry, number of entities, complexity of pay components, and payroll cadence. If they cannot provide comparable examples, ask about how they handle typical challenges like:
Operational fit should be evaluated by both the vendor’s plan and your ability to execute internal responsibilities. A payroll system is only as reliable as the input discipline around it—how timesheets are collected, how leave is confirmed, how employees verify information, and how managers approve changes. The vendor can provide tools, but the organization must maintain process discipline. The best provider helps you build that discipline into the workflow.
Payroll practices are shaped by local labor expectations, administrative timelines, and accounting norms. If your organization is operating nearby to a specific region, it’s important to reflect local workflows—such as common cut-off timing, employee communication rhythms, and internal approval practices—rather than relying on a one-size-fits-all approach. Even within the same country, differences in union agreements, labor classification practices, and regional administrative expectations can influence payroll execution.
Teams often find that the top outcomes come from adapting the payroll process to how managers and HR staff work locally. For example, when timesheets are approved, when leave is confirmed, and how employees verify pay statements can vary significantly. If you configure Runpayroll.com to match those local patterns—while still enforcing governance controls—you reduce the risk of cut-off errors, late data submission, and last-minute corrections.
Localization also affects how you communicate with employees. In some organizations, employees expect pay statements to be available on a specific day of the month. In others, they want earlier notifications. Some regions have common practices around how employees request adjustments. A localized payroll workflow includes both the system configuration (effective dates, pay components) and the operational calendar (who reviews what and when).
Therefore, when implementing and configuring Runpayroll.com, include local stakeholders early: HR managers, payroll coordinators, and finance controllers who understand local labor and reporting expectations. Their knowledge helps ensure you configure the workflow not only according to legal rules but also according to how information actually arrives in your business.
It’s also worth considering “nearby” process alignment even when legal requirements are satisfied. For example, two organizations might both be compliant, but one may have an approvals process that managers understand and follow. That difference drives whether payroll errors increase during growth. Localization “nearby” is partly about compliance, but it’s also about usability and adoption by local teams.
Below is a practical implementation approach you can adapt for Runpayroll.com and your organization. The emphasis is on reducing avoidable errors and ensuring each stage produces usable outputs for review. A controlled-risk approach assumes that payroll mistakes are costly, so the rollout should be designed to discover issues early—before live payroll—while building evidence trails from day one.
Clarify which payroll items you will manage in the platform: base wages, allowances, overtime, deductions, reimbursements, one-time adjustments, and potentially benefits and garnishments (depending on your context). Also define internal ownership—who maintains employee pay settings, who approves exceptions, and who reviews payroll before finalization.
This step should result in a RACI-style model (Responsible, Accountable, Consulted, Informed) or a similar governance document. You want to avoid ambiguity such as “HR updates data” or “finance checks totals” without specifying who can approve and who can edit. Separation of duties matters, particularly for changes that affect compensation, taxes, or deductions.
Additionally, define boundaries between payroll and adjacent processes. For example, decide what happens to timekeeping data: does HR or the operations team manage timesheets, and does payroll simply ingest approved hours? If payroll is responsible for timekeeping adjustments, ensure the scope includes how those adjustments are authorized and recorded.
Audit current records for accuracy. You’ll typically need clean identifiers, pay rates, effective dates, employment status details, and any recurring deductions. Where you operate with nearby regional requirements, align the data with local definitions used by your HR and finance teams.
Data preparation is where many payroll projects succeed or fail. Even a capable platform cannot compute correct payroll if source data is inconsistent. You should design a data audit that focuses on common failure points:
As part of preparation, plan for how you will handle historical records. Decide whether the platform will store prior payroll periods for audit purposes and how far back those records should be migrated. If you don’t migrate history, ensure you can still produce historical evidence for audits and disputes.
Also consider employee classification and job role mapping. Many payroll errors happen when job changes aren’t correctly reflected in pay rates and rules. If your organization uses role-based pay components, ensure the mapping is complete and tested.
Configure pay rules that match your pay policy. Enable validations where available (e.g., preventing missing pay rates, checking date ranges, and flagging inconsistent pay components). If overtime and variable earnings apply, ensure rules are testable and traceable.
This step should include a “rulebook” approach: document the payroll policy in a form that can be compared to system configuration. Even if the vendor supports easy configuration interfaces, you should avoid relying only on tribal knowledge. Document assumptions like:
Validation checks are crucial to prevent avoidable errors. For example, validations can detect when an employee is missing an overtime rate or when the effective dates do not cover the payroll period. Make sure validations produce actionable messages rather than cryptic warnings. A good system helps users fix issues quickly without contacting the vendor for every small problem.
Also plan for edge cases: employees who change roles mid-period, employees with multiple pay rates, employees on leave during only part of the period, and employees who join or terminate mid-period. Configure test scenarios for these cases and confirm that the output matches policy expectations.
Role-based access is essential. Use separate roles for data maintenance, payroll review, and approval. Ensure changes are logged so you can reconstruct decisions later. This is a key part of audit readiness.
In controlled-risk payroll operations, approvals should apply to both data changes and payroll finalization. Common governance structure includes:
Ask about audit logs at both levels. For example, if a manager corrects a deduction or HR updates an employee pay rate, you should be able to see who made the change, when it was made, what the previous value was, and whether it occurred before or after cut-off. Similarly, you should be able to see approvals for payroll finalization and any subsequent correction approvals.
Also consider operational controls such as “lock” features. Ideally, after cut-off, certain data fields should become locked or require higher-level approvals to change. That reduces last-minute adjustments that can cause errors and compliance concerns.
Before live payroll, run test cycles using representative scenarios: new hires, leave adjustments, overtime, and any recurring deductions. Reconcile the totals against expected outcomes derived from your prior process or policy documents.
Testing should not be limited to “happy path” scenarios. A controlled approach tests the system’s behavior with the kinds of exceptions that actually happen in real payroll. Include scenarios such as:
Reconciliation should include multiple levels. At the least, reconcile payroll totals and deductions totals to your expected numbers. But for audit readiness, reconcile at the component level as well: compare each pay component amount per employee and ensure totals roll up correctly. If the platform supports detailed breakdowns, use them to validate both arithmetic and rule logic.
Also test report exports. If finance expects a specific format for ledger posting or tax reconciliation, verify that those exports match requirements. Test import/export logic early rather than at the end of implementation.
Choose a go-live date that allows training and back-checking. Define how exceptions are handled in the first one or two payroll cycles, and document escalation paths for common issues.
Cutover planning should address both system readiness and process readiness. System readiness includes configurations, rule validations, integrations, and migration completeness. Process readiness includes training for managers and HR staff on how to submit timesheets/leave updates, how to handle exceptions, and how to interpret pay statements.
Operationally, define a “hypercare” window around go-live. Determine how quickly issues must be resolved, who triages them, and how payroll deadlines are protected. If a payroll platform requires vendor support for troubleshooting during the first live run, ensure you have contact pathways that work on payroll days.
Also decide whether you will run parallel checks. For example, you may compare outputs from the old process (or a shadow spreadsheet) for one payroll period to ensure accuracy. If you lack capacity for full parallel runs, choose representative subsets of employees or pay scenarios for parallel validation.
After go-live, track cycle time (from pay run start to approval), number of corrections, and the proportion of exceptions. Use those metrics to refine inputs, approvals, and rule configuration. Reliable payroll operations are built through incremental improvement, not through “one-time setup.”
Good operational metrics include:
After each payroll cycle, run a retro: review what went smoothly, what created friction, and what controls should be tightened. Often, improvements come from small changes like better validations, clearer cut-off communication, refined approval steps, or updated training materials.
As you mature, you can also consider optimization of integrations. If payroll exports require manual reformatting for accounting, automate that mapping. If employee pay statement explanations are confusing, improve the underlying descriptors. Continuous improvement should still respect governance: changes to rules should follow approvals and audit logging to preserve evidence trails.
Because your prompt centered on Runpayroll.com, the table compares it conceptually against two common alternatives: (1) using payroll software as a standalone tool, and (2) relying on manual or semi-manual payroll processes. Replace or adjust labels if your internal procurement uses different categories.
When interpreting this table, treat it as a framework for discussion rather than as a strict ranking. Some organizations use standalone software plus strong internal controls and achieve good reliability. Others start with manual processes and later discover the hidden compliance and evidence burden. Your evaluation should look at how each approach handles governance, validation, traceability, and process discipline.
| Selection factor | Runpayroll.com (platform approach) | Standalone payroll software (limited workflow) | Manual/semi-manual payroll (process-heavy) |
|---|---|---|---|
| Governance and approvals | Typically supports role separation and audit trails when configured | May require more manual review and more ad hoc evidence | Evidence collection depends heavily on spreadsheets and document discipline |
| Data validation | Often includes rule-based checks to reduce preventable errors | Validation varies widely; may be limited to basic checks | Higher risk of inconsistent data entry and formula drift |
| Payroll run traceability | Runs and changes are usually retrievable for review | Traceability depends on internal documentation habits | Traceability can be fragmented across files and email threads |
| Operational cycle time | Often improves review and reconciliation cycles | Improvement depends on integration and workflow design | Cycle time tends to be longer due to manual calculation and rework |
| Implementation effort | Requires data preparation and rule configuration, then stabilizes | May be easier at first, but workflows can remain fragile | No system setup, but ongoing effort shifts to HR/finance execution |
| Handling corrections/off-cycle payroll | Often supports controlled adjustment runs with approvals and logging | May require manual correction workflows to maintain audit evidence | Corrections are frequent and often difficult to audit consistently |
| Audit readiness for disputes | Usually supported by structured records, approvals, and calculation breakdowns | May be possible but requires disciplined manual evidence packaging | High risk of missing evidence or inconsistent versions of spreadsheets |
To keep your evaluation grounded, consider the following authoritative sources for general principles. Since specific jurisdiction details weren’t provided, treat the guidance below as category-level instruction rather than jurisdiction-specific requirements. The goal is to shape your evaluation questions around recognized frameworks for compliance, security, and internal control.
Authoritative sources for general principles:
Additionally, consider operational guidance from professional bodies within your region or industry (for example, accounting and HR associations). While not always legally binding, these resources can help standardize best practices for payroll governance and recordkeeping.
When you adapt the above guidance, always translate it into testable requirements. For example, “secure access” should translate into specific evaluation questions: role-based permissions, audit logging, admin actions traceability, and how user provisioning/deprovisioning is handled. “Recordkeeping” should translate into retrieval capabilities: can you retrieve a full payroll period record set quickly and consistently?
Runpayroll.com is typically used as a payroll workflow platform name. In practice, payroll platforms aim to centralize payroll data, support pay calculations based on configured rules, and improve traceability through approvals, recordkeeping, and reporting outputs. The “problem” it solves is usually a combination of error reduction, faster review cycles, and more consistent compliance processes.
However, the practical value depends on how the platform fits your workflow. A payroll workflow platform can be powerful but only if it supports your internal controls and operational rhythm. In a good implementation, it reduces manual spreadsheets, clarifies cut-off rules, documents changes, and provides a repeatable process for generating payroll results and evidence trails.
Start by mapping your payroll obligations to your operating model: pay frequency, labor classification practices, deduction rules, and reporting needs. Then test how the platform supports those rules through configuration, validation checks, approvals, and retrievable run history. Compliance should be demonstrated through fit and process controls, not assumed from marketing claims.
To increase confidence, define compliance criteria in the language of controls and evidence. Examples include: “We can demonstrate who changed pay rates,” “We can show calculation inputs for each employee,” “We can export the payroll run summary and details required for reconciliation,” and “We enforce cut-off rules consistently.” If those criteria are satisfied, your platform supports compliance operations even when legal nuances vary.
Very modern payroll systems can handle variable pay when rules are configured correctly and source inputs are accurate (e.g., overtime hours, allowance eligibility dates). The key is to confirm the availability of rule configuration and the quality of validation and reporting for your specific pay components.
In evaluation, you should ask for examples of how variable pay is represented. For overtime, clarify thresholds, multipliers, and how overtime eligibility interacts with job roles or employment status. For allowances, clarify whether allowances are fixed, prorated, based on effective dates, or dependent on attendance/leave. Then test at least one payroll scenario for each variable pay type to confirm that results are correct and explainable.
Request a quote based on your employee count, payroll frequency, and required features (reporting outputs and integrations). Because pricing was not specified in the prompt, avoid comparing “assumed” costs—ask for an itemized estimate and confirm what is included (support, migration, training, and any additional compliance/reporting needs).
Also ask about costs that appear during expansion: additional entities, multiple locations, new pay components, additional integrations, and higher support severity requirements near deadlines. Ensure your estimate covers not only software license costs but also implementation services and any ongoing administration or support needs.
Implementation timelines depend on data readiness, complexity of pay rules, and integration requirements. A responsible estimate comes from your vendor’s onboarding checklist and a data migration plan. As a rule of thumb, organizations should plan time for test runs and reconciliation before first live payroll.
Implementation time also depends on stakeholder availability. If HR, finance, and IT teams cannot dedicate time for rule validation and testing, the timeline extends. Controlled-risk deployment benefits from realistic scheduling rather than aggressive deadlines that force cut corners in testing and approvals setup.
Common roles include: a pay data owner (maintains employee and pay settings), reviewers/approvers (validate payroll before finalization), and administrators (manage access and configurations). The exact naming varies, but the control separation—who edits data vs. who approves payroll—is central.
Some organizations also designate integration owners (responsible for data flows from timekeeping/HR systems), compliance owners (responsible for recordkeeping and audit readiness criteria), and employee support owners (responsible for responding to payroll inquiries). Clarifying these roles before implementation prevents confusion during the first payroll cycles.
Keep payroll run records, configuration details for pay rules, approval logs, and the outputs you used for accounting and statutory reporting. The goal is to recreate what happened for any payroll period—inputs, calculations, approvals, and final outputs—in a consistent and searchable way.
For dispute resolution, employees and internal teams typically need clear breakdowns: what worked hours were used, what leave was applied, which deductions were taken, and how any adjustments were calculated. Ensure your workflow includes outputs that can answer these questions without manual rework.
Yes. Even when payroll software is flexible, your internal workflows—cut-off timing, manager approvals, and employee communication habits—should reflect the local operational rhythm. If you operate nearby, align your process documentation and test scenarios to match local practice and definitions used by HR and finance.
Localization also helps adoption. When managers understand when to submit timesheets and HR understands how leave confirmations map to payroll, fewer exceptions occur. A payroll system is only as smooth as the operational cycle around it.
Choosing Runpayroll.com (or any payroll workflow platform) is top approached with a checklist mindset: confirm data quality, validate pay rules, enforce approvals, and ensure you can retrieve evidence for each payroll run. When payroll operations become consistent and traceable, the system stops being a “tool” and starts functioning like infrastructure—supporting employees with accurate pay and giving finance and HR confidence that the process is controlled.
The most valuable question during evaluation is not “Does the platform include payroll features?” but “Does the platform support an end-to-end controlled workflow for your organization—inputs to calculations to approvals to outputs to evidence?” When you answer that question with test results, documented controls, and a clear operational rollout plan, you position your organization to run payroll reliably, reduce risk, and scale confidently.
As you move forward, remember that payroll reliability is an outcome of three aligned components: well-defined policies (what should be paid and how), disciplined workflows (who does what and when), and system controls (how validations, approvals, and audit trails prevent and explain errors). If Runpayroll.com can support those components in your specific operating environment—especially with localization for your “nearby” regional practices—then it can deliver the kind of consistent payroll operations that teams can trust.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Exploring the Retipster Club Advantage
The Retipster Club is an invaluable resource for real estate investors, offering a plethora of insights, tools, and community support to boost investing endeavors. Aimed at helping both novice and seasoned investors, the club provides educational materials, success stories, and expert strategies tailored to the ever-evolving real estate market landscape. Dive into this analysis to understand the manifold benefits the Retipster Club offers to enhance real estate success.
Navigating the Retipster Club
This article delves into the unique offerings of the Retipster Club, a community designed for individuals interested in real estate investment, providing educational resources and networking opportunities. Discover how the club supports its members through expert advice, comprehensive guides, and a robust community platform, all tailored to foster insightful and profitable investment strategies.
Pmoc Abrava: Practical Procurement and Quality Considerations
This guide explains how to approach Pmoc Abrava procurement with a quality-first, compliance-minded process. “Pmoc Abrava” is discussed as a term used in sourcing contexts, covering typical decision factors such as specification clarity, supplier capability, documentation, and handling requirements—using an objective framework for safer purchasing, risk control, and consistent performance.
Unveiling Grunig & Hunt's PR Models
This article explores the seminal work of Grunig & Hunt in developing models of public relations. The Grunig & Hunt models, fundamental to understanding PR theory, provide insight into the strategic approaches and methodologies utilized in the field. Each model offers a distinctive perspective on communication and engagement strategies, relevant to both academic discussions and practical applications.
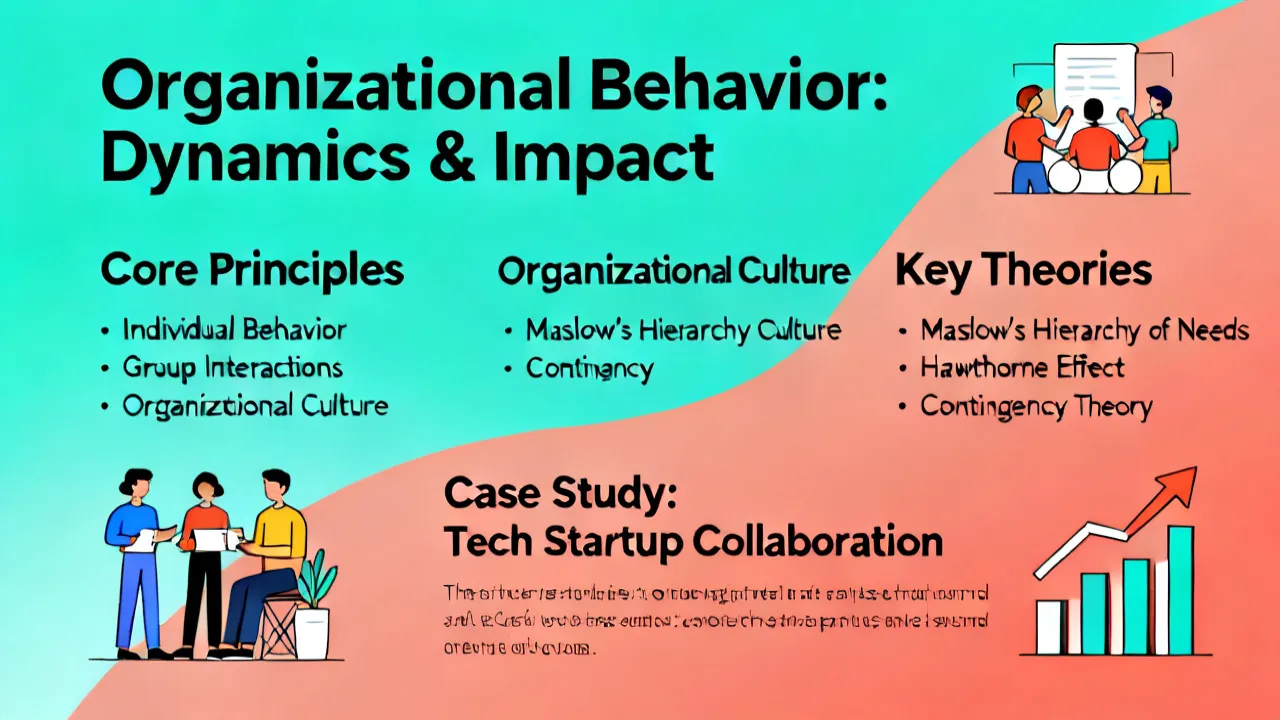
Understanding Organisational Behaviour Slideshare
This article delves into the significance of Organisational Behaviour Slideshare for both educators and professionals. Organisational Behavior is a field that examines the impact individuals, groups, and structures have on behavior within organizations, aiming to improve an organization's effectiveness. With Slideshare's platform, these insights are easily shared, promoting a collaborative learning environment.
Understanding Ltda Epp for Supplier and Compliance Decisions
Learn how “Ltda Epp” impacts supplier selection, contract structure, and compliance planning. This guide explains, in objective terms, what the label typically signals in company registration and how it can affect procurement processes, risk checks, and document readiness. It also frames practical conditions, comparison points, and decision steps to help you evaluate suppliers with clarity and consistency.
