This guide explains how organizations evaluate and use Runpayroll.adp.com for payroll administration, emphasizing setup accuracy, compliance, and operational controls. Background context covers payroll workflow components, why secure access matters, and how companies typically structure approvals, reporting, and data governance—drawing on standard industry practices rather than speculation.
Runpayroll.adp.com is commonly referenced by employers and HR/payroll teams as part of an ADP-linked payroll workflow, where the goal is to manage employee payroll tasks with consistent processing, reporting, and access controls. The very important starting point is not “logging in and hoping,” but treating payroll as a controlled business process: verify inputs, establish approvals, maintain audit trails, and align processing calendars with your local compliance obligations.
From an industry-expert perspective, the fastest path to stable payroll outcomes is to design your workflow before touching production data—especially around employee data integrity, pay-run eligibility rules, and downstream reporting. Even when the platform experience feels straightforward, payroll accuracy depends on preparation, system configuration, and governance.
Responsible payroll operations means more than producing checks. It includes ensuring employees are paid correctly for the correct time period, deductions are handled as authorized, taxes are calculated and remitted according to the applicable rules, and every change is traceable back to a person, a reason, and a timestamp. It also means acknowledging that payroll is both operationally critical and tightly regulated. A “responsible approach” therefore includes security, change management, testing discipline, and clear escalation paths when something looks wrong.
In practice, the teams that experience the fewest recurring payroll issues share a similar mindset: they design payroll around controls. They do not rely on individual memory or ad hoc decisions. Instead, they build repeatable steps, standard checklists, and exception handling procedures that remain effective even when staff changes occur or workloads increase near payroll deadlines.
Another responsibility layer is employee trust. Payroll is one of the most visible and emotionally loaded business processes. Even small errors can create significant employee frustration, HR workload spikes, and reputational damage. Therefore, responsible payroll operation is both a compliance requirement and a customer service commitment—where “customer” is the workforce and where correctness and timeliness are non-negotiable.
In practical terms, teams that reference Runpayroll.adp.com usually mean a payroll administration interface or payroll execution environment within the broader ADP ecosystem. Regardless of whether you are initiating a pay run, reviewing results, or producing payroll reports for finance and HR, the operational expectations are similar across payroll platforms:
Because payroll is both operationally critical and regulated, organizations should treat platform use as part of an end-to-end system—not a single click or isolated task.
It’s also important to understand that payroll platforms generally operate within a larger “ecosystem.” Runpayroll.adp.com might be the interface where the pay run is executed, but it likely relies on upstream systems such as time and attendance, benefits administration, HR master data, and accounting configuration. If those upstream sources are misconfigured, incomplete, or updated late, the downstream payroll execution will reflect those issues—even if everything is done correctly inside the payroll platform.
In other words, “Runpayroll.adp.com represents a workflow stage.” Responsible operations treat each stage—input, validation, calculation, review, approval, posting, and reporting—as part of one connected system. When teams do this, they can pinpoint where deviations occur. When they don’t, problems become mystery-driven, and remediation becomes expensive and slow.
Many payroll issues originate upstream: incorrect hire dates, mismatched pay frequency, missing benefit enrollments, or late updates to time and attendance. In mature payroll operations, teams use a “two-lane” approach:
Even if a platform such as Runpayroll.adp.com streamlines the execution lane, the execution lane still relies on the quality of the input lane. In day-to-day HR practice, that’s where very preventable problems occur.
Process design is what prevents payroll errors from becoming repetitive incidents. For example, consider the recurring scenario where employees are paid under the wrong pay rate. In many organizations, the root cause is not that payroll calculations are wrong, but that effective date updates were entered incorrectly or were not communicated to the payroll team until after the cutoff. A process design that includes validation of effective dates and a clear change communication protocol would detect and prevent this earlier.
Similarly, many “calculation seems off” issues are caused by upstream timing rather than computational errors. If time entries cross a payroll period boundary incorrectly, the pay run will be mathematically consistent but operationally wrong. A well-designed process includes cutoff enforcement, reconciliation between time totals and payroll totals, and exception review for unusual patterns.
Responsible process design also accounts for staff rotation and workload spikes. Payroll teams often face intense periods around month-end or multi-state tax recalculations. If the process is built only around tribal knowledge (“we always do it this way”), it becomes fragile. A process built around documented controls remains resilient.
Payroll operations teams typically implement a layered control framework. Below are practical controls that map well to any payroll admin environment, including those associated with Runpayroll.adp.com:
To make these validations practical, teams often establish “must-check” lists for each pay run. For instance, for hourly employees, hours totals should be compared against expected ranges, and the organization should review any employees whose hours are significantly outside typical patterns. For salaried employees, the main risk is not hours but compensation changes—such as new salary rates, promotions/demotions, or policy-driven changes.
Validation also applies to less obvious fields that can have large downstream consequences. Examples include:
When these validations are performed consistently before production processing, the payroll run becomes more reliable and review workload decreases. Reviewers can focus on exceptions rather than verifying basic correctness for every record.
Segregation of duties (SoD) is one of the most effective controls in payroll. It reduces the chance that a single person can both make changes and “sign off” without oversight. A common operational model is:
Even if your organization is small, you can implement an SoD-like approach. For example, one person prepares data updates but another reviews and approves the run. If roles are constrained by staffing, you can implement compensating controls—such as enhanced logging, documented second-person reviews, and stricter change windows.
Least-privilege access is also crucial. Payroll platforms contain extremely sensitive data: names, addresses, tax IDs, wage details, and deductions. Responsible access governance includes limiting access to the minimum required, enabling strong authentication, and performing periodic access reviews.
Pre-run verification answers the question: “Should we process this, and is it likely to be correct?” Post-run reconciliation answers: “Did the process produce expected results, and do we have accounting-ready outputs?”
Experienced teams often set expectations for what “reasonable” looks like. Reasonableness checks might include:
The goal is straightforward: prevent mistakes, detect mistakes early, and preserve evidence of what happened and why.
Below is a step-by-step approach that an experienced payroll operations lead would typically recommend. The exact menu names may differ based on your contract and configuration, but the workflow logic remains stable.
In a responsible payroll operation, preparation is not just “review a list.” It includes establishing that the organization is in a position to run payroll before deadlines. That means you should:
Preparation also includes planning for what happens if inputs arrive late. Rather than improvising, many organizations maintain a “late changes policy” describing:
This makes your payroll process calmer under pressure.
During pre-run configuration, the most common failure mode is selecting the wrong payroll period or running payroll with incorrect settings. Even if the platform provides a strong user interface, a responsible process does not rely solely on user attention. Teams typically reduce the risk with:
Pre-run exception reports are especially valuable. Instead of reviewing every employee record manually, reviewers focus on flagged items. Exception lists might include employees with missing tax fields, employees with inconsistent pay rates, or employees with deductions that have no valid effective date.
When discrepancies are found, the team should document:
This documentation becomes part of audit evidence and also helps reduce repeat incidents.
Execution should be treated as a controlled operation. Responsible teams avoid “partial” or “unauthorized” runs. If your policy supports staged execution (for example, run in a preview mode first), you should follow that. If preview mode is available, it should be used to validate output before finalization.
Approval workflows should be explicit. For example, approvals can be structured around:
In organizations where approval roles are not easily separable due to staffing, a responsible alternative is to implement a “two-person review” even if both persons have the ability to edit. The key is ensuring accountability and traceability.
During register review, reviewers should pay attention to both totals and individual employee outcomes for exceptions. It is common to review totals at a macro level (gross pay, net pay, deductions total) and then drill into employee-level items only for exceptions or outliers.
Posting is where many teams accidentally lose control if they do not verify that payroll is finalized correctly and in the expected state. Responsible operations include:
Distribution of payroll documents should follow privacy policies and controlled communication channels. Even though payroll statements are employee documents, they still contain sensitive financial information and should be handled securely.
Reconciliation to accounting is where payroll becomes financial reporting readiness. Many organizations create a standard reconciliation pack that includes:
When reconciliations are consistent and well documented, finance and compliance teams experience fewer surprises and faster close processes.
With this workflow in place, Runpayroll.adp.com becomes a predictable execution point in a broader operational system rather than the center of gravity for accuracy.
You may encounter references to “price” when searching for payroll administration tools, but it’s important to distinguish between platform subscriptions, implementation services, and ongoing support. Payroll costs are usually influenced by factors such as:
Because I do not have verified, current price data for your specific contract or region, the responsible approach is to request a quote from the supplier or your ADP representative and compare it against internal process costs (labor time for payroll processing, rework, and error remediation). Where vendors provide published pricing frameworks, you can use those as starting points, but final pricing is typically contract-based.
Supplier context: ADP is a widely used payroll and HR services provider. When organizations mention Runpayroll.adp.com, they typically mean part of an ADP customer workflow for payroll administration. As with any supplier, the evaluation should cover security posture, audit support, service level expectations, and how payroll results are delivered for your reporting needs.
In addition to direct costs, responsible procurement evaluates total cost of ownership (TCO). For payroll platforms, TCO often includes:
Because payroll is high-impact, the best “value” is not always the lowest subscription fee. Instead, it is often the configuration and operational model that minimizes mistakes and reduces the burden on payroll staff.
Payroll touches tax withholding, wage and hour obligations, and employee privacy. Therefore, any team using Runpayroll.adp.com should confirm that their configuration aligns with applicable regulations and internal policies. While requirements vary by jurisdiction and employment type, common risk-reduction conditions include:
If you operate across jurisdictions (even within a single country), you should also ensure that tax and reporting mappings are correct and updated when rules change. Use your supplier’s release notes and your internal change management process to stay current.
Compliance is not a one-time checklist. It is a lifecycle activity. Regulations can change, and so can your workforce structure. The payroll process must adapt, and adaptation requires controlled change management.
Some common compliance and risk areas payroll teams monitor include:
A responsible payroll governance model includes a clear “owner” for compliance updates. That owner might be the payroll leader, tax/HR compliance lead, or operations manager—depending on your organization. What matters is that someone is accountable for staying informed and for coordinating changes through testing and approvals.
The following table compares practical options for managing payroll execution and review around Runpayroll.adp.com. It is designed to help teams think in terms of governance, not just interface familiarity.
| Option / Source | Step-by-step guide (what to do) | Conditions / requirements to succeed |
|---|---|---|
| Internal payroll operations team (source: internal SOPs and HR/finance policies) |
1) Confirm pay calendar and deadlines. 2) Affordableze data inputs per your SOP. 3) Run pre-checks and exception reviews. 4) Execute pay run via the appropriate ADP workflow. 5) Review payroll registers, then approve. 6) Reconcile outputs to finance and archive evidence. |
Documented SOPs; trained reviewers; defined approval roles; consistent cutoff timing; evidence retention for audits. |
| Supplier guidance (source: vendor documentation and release notes) |
1) Review supplier documentation for your specific configuration. 2) Follow recommended setup and validation practices. 3) Apply updates via change management. 4) Re-test key scenarios (hires, terminations, retro adjustments). 5) Monitor post-release outcomes. |
Access to release notes; a test or staging environment if supported; designated owner for configuration changes; alignment between documentation and your actual process. |
| Security and audit model (source: internal controls and compliance requirements) |
1) Define least-privilege roles for payroll data access. 2) Require segregation of duties for edits vs approvals. 3) Confirm logging and audit trail retention. 4) Perform periodic access reviews. 5) Validate incident response steps for payroll-impacting events. |
RBAC configured correctly; periodic access review cadence; staff training; ability to evidence approvals and changes. |
When payroll systems are connected to other enterprise tools—such as time tracking, benefits administration, HR records, and accounting—operational risk increases if data governance is unclear. An expert payroll leader will typically ask:
Even in a well-designed platform workflow, the “handoff points” between systems are where inconsistencies can emerge. Teams should document integration boundaries and confirm that every input transformation is repeatable and testable.
Operational continuity is another expert topic. Payroll must happen even during system outages or connectivity problems. While specific contingency planning varies by supplier and contract, responsible teams prepare by:
Data governance also includes controlling master data changes. If pay rates or employment statuses can be modified in multiple places without a clear single owner, payroll risk rises. An effective governance model clarifies:
In many organizations, a governance council or weekly operations meeting helps. It can include payroll, HR operations, benefits admin, and sometimes finance. The goal is to anticipate issues before they reach payroll day, rather than react after outputs are produced.
Payroll accuracy depends on correctly handling both common and edge cases. Instead of relying on one standard pay run, an expert team maintains a set of test scenarios. Examples include:
After updates, the team re-validates these scenarios to confirm that calculations and reporting outputs remain consistent. This is particularly important when new features, tax rule updates, or workflow changes are introduced by the supplier.
A robust testing approach includes several layers:
Testing should be scheduled and communicated. Payroll is time-sensitive, so testing should avoid interfering with active cycles. Many organizations implement a test window after each release or after internal configuration changes. If staging environments are limited, teams can still do “small-scope” validation using limited employee samples or partial payroll runs in a controlled manner—while staying within supplier guidance.
Another reliability technique is to maintain a “known issue” log. If a certain integration scenario tends to fail or produce an exception, the team documents it and builds detection into pre-run checklists. This prevents repeated firefighting and makes exceptions more predictable.
When payroll corrections become necessary, reliability requires a disciplined correction strategy. Corrections often involve reprocessing, supplemental runs, or retro adjustments. Responsible teams:
This approach reduces the risk that a correction process introduces new inconsistencies.
Runpayroll.adp.com is typically referenced as part of an ADP-related payroll administration workflow. In general, such environments are used for payroll execution, review, reporting, and controlled processing steps required to produce accurate payroll results.
Very organizations do. A common top practice is to require segregation of duties—separating who can make changes from who can approve the finalized payroll—so errors are caught during review rather than after final posting.
Focus on input accuracy and control: validate employee data and deductions before the run, review exception reports, reconcile totals after processing, and maintain an audit trail of edits and approvals.
Start with the very likely upstream causes: incorrect pay rates, effective dates, missing or duplicated deductions, time/attendance timing issues, or eligibility mapping errors. Then compare pre-run and post-run reports to pinpoint the change that produced the discrepancy.
Use your internal cutoff policy and reprocessing rules. Many organizations decide whether late changes apply to the current pay period or the next one, and they document corrections so payroll records remain consistent and auditable.
No. Payroll platform costs commonly depend on employee volume, service scope, integrations, implementation needs, and support model. For the very accurate pricing, organizations typically obtain a quote or proposal from the supplier based on their configuration and requirements.
Compliance comes from correct configuration, timely updates, and internal governance: validate effective dates, confirm tax/reporting mappings, use a payroll calendar aligned to requirements, and preserve logs and run outputs for auditability. Also, follow supplier release guidance and incorporate changes through controlled testing.
Implement least-privilege access, segregate duties, conduct periodic access reviews, and ensure audit logs are retained. Also train staff on how to recognize and report suspicious activity, since payroll data is sensitive and targeted.
Runpayroll.adp.com (as referenced in many payroll-administration contexts) should be approached as an operational control point inside a broader, documented payroll process. The interface matters, but outcomes depend on governance: data readiness, disciplined review, segregation of duties, and reliable reporting. When organizations apply these principles consistently, payroll processing becomes more predictable—and when exceptions occur, the team can resolve them with confidence and evidence.
Responsible payroll operations is ultimately about building a system that prevents errors, detects them quickly, and corrects them with transparency when they arise. Treating Runpayroll.adp.com as a disciplined workflow stage—not as the source of truth—helps payroll teams maintain accuracy, compliance, security, and employee trust across every pay cycle.
Note: This article provides guidance on payroll operations and governance concepts. Specific features, naming conventions, and configuration steps may vary by organization and contract. For authoritative instructions, consult your supplier documentation and implementation support.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Exploring the Retipster Club Advantage
The Retipster Club is an invaluable resource for real estate investors, offering a plethora of insights, tools, and community support to boost investing endeavors. Aimed at helping both novice and seasoned investors, the club provides educational materials, success stories, and expert strategies tailored to the ever-evolving real estate market landscape. Dive into this analysis to understand the manifold benefits the Retipster Club offers to enhance real estate success.
Navigating the Retipster Club
This article delves into the unique offerings of the Retipster Club, a community designed for individuals interested in real estate investment, providing educational resources and networking opportunities. Discover how the club supports its members through expert advice, comprehensive guides, and a robust community platform, all tailored to foster insightful and profitable investment strategies.
Pmoc Abrava: Practical Procurement and Quality Considerations
This guide explains how to approach Pmoc Abrava procurement with a quality-first, compliance-minded process. “Pmoc Abrava” is discussed as a term used in sourcing contexts, covering typical decision factors such as specification clarity, supplier capability, documentation, and handling requirements—using an objective framework for safer purchasing, risk control, and consistent performance.
Unveiling Grunig & Hunt's PR Models
This article explores the seminal work of Grunig & Hunt in developing models of public relations. The Grunig & Hunt models, fundamental to understanding PR theory, provide insight into the strategic approaches and methodologies utilized in the field. Each model offers a distinctive perspective on communication and engagement strategies, relevant to both academic discussions and practical applications.
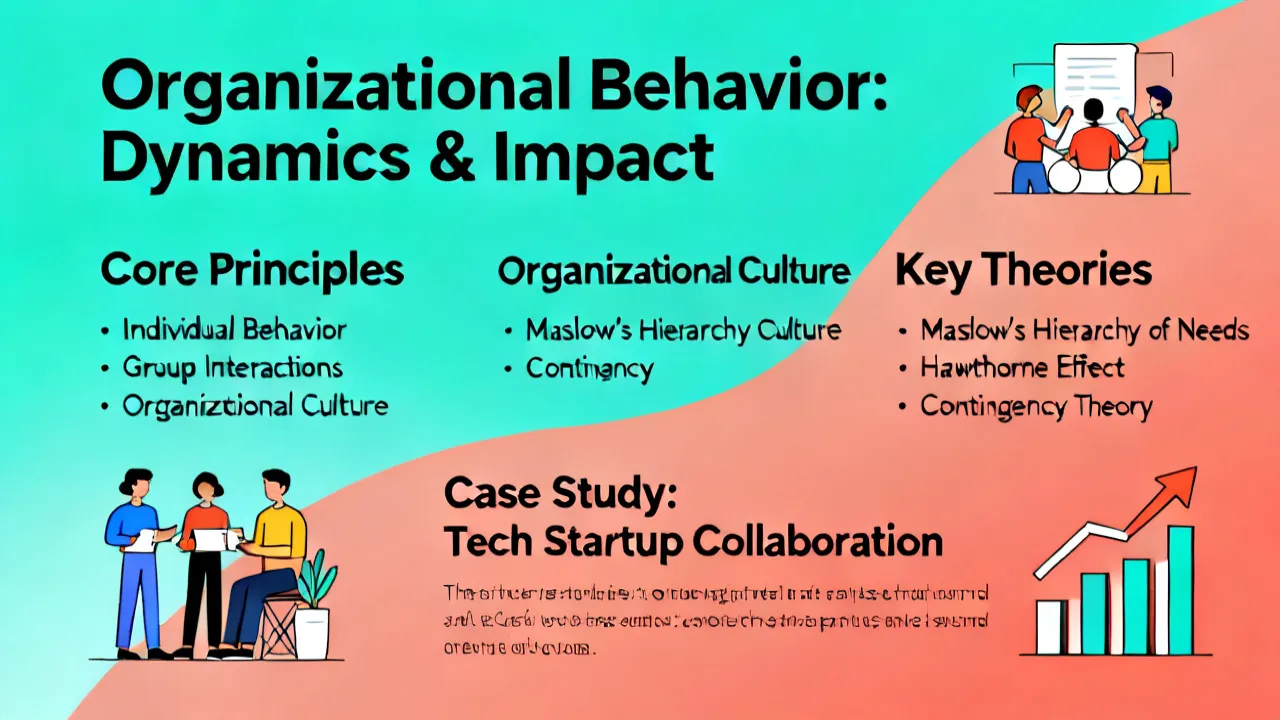
Understanding Organisational Behaviour Slideshare
This article delves into the significance of Organisational Behaviour Slideshare for both educators and professionals. Organisational Behavior is a field that examines the impact individuals, groups, and structures have on behavior within organizations, aiming to improve an organization's effectiveness. With Slideshare's platform, these insights are easily shared, promoting a collaborative learning environment.
Understanding Ltda Epp for Supplier and Compliance Decisions
Learn how “Ltda Epp” impacts supplier selection, contract structure, and compliance planning. This guide explains, in objective terms, what the label typically signals in company registration and how it can affect procurement processes, risk checks, and document readiness. It also frames practical conditions, comparison points, and decision steps to help you evaluate suppliers with clarity and consistency.
