Layaway programs help shoppers reserve an item by paying in scheduled installments before pickup. This guide explains how layaway works, what to confirm with the supplier, and how terms like payment schedules, fees, and cancellation policies affect cost and risk. Background sections outline key industry practices and practical decision criteria.
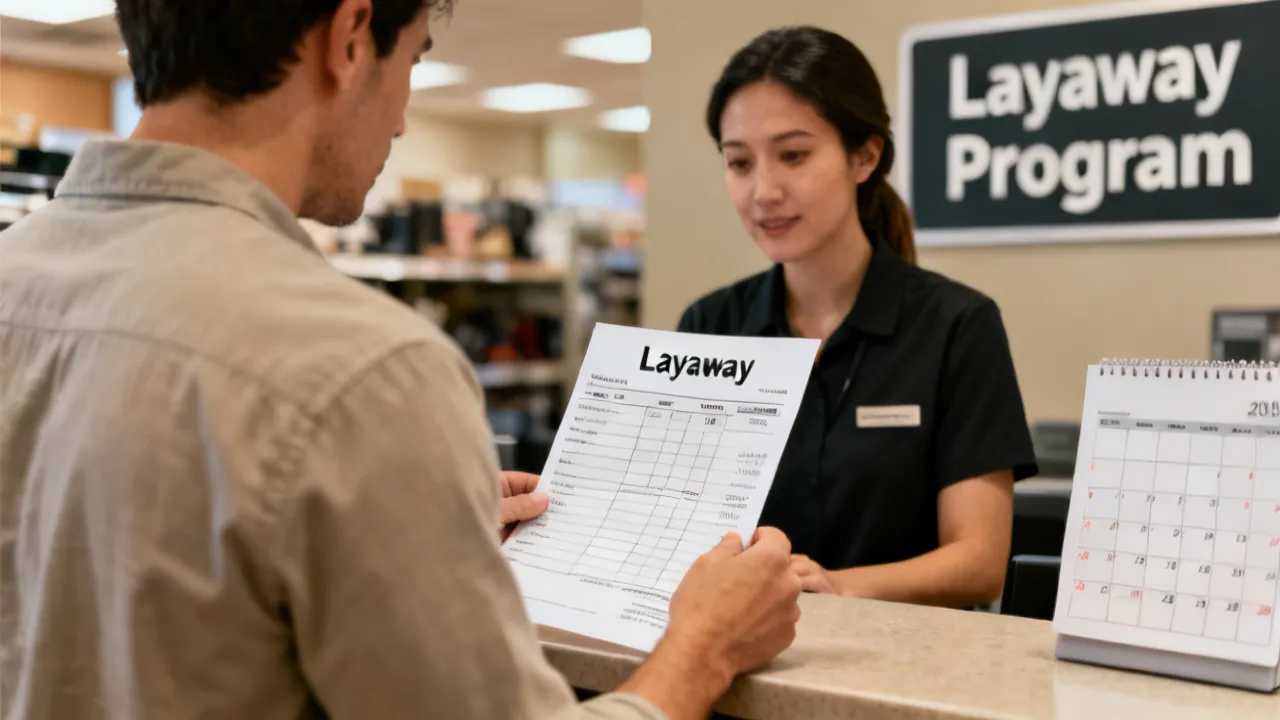
Layaway is a purchase arrangement where you reserve merchandise with a series of payments over time, and the item is released once you meet the agreed payment requirements. For many shoppers, it functions as a structured alternative to paying the full price upfront—provided the plan terms are clear and the supplier’s conditions are realistic for your budget and timeline.
In practical terms, a layaway agreement typically outlines: (1) the total price of the item, (2) a payment schedule, (3) any service or administrative fees, (4) the length of the layaway period, and (5) what happens if you miss payments or need to cancel. Because these elements vary by supplier and jurisdiction, objective due diligence matters more than the promise of “affordability.”
Although many people talk about layaway as if it’s simply a “hold until paid” option, the reality is that layaway is a full purchase contract with an operating process behind it. That means your experience is not only about the item you want—it’s also about the procedures the retailer follows to reserve inventory, record payments, handle changes, and ultimately transfer ownership when the plan is completed.
When a layaway plan is run well, it can reduce financial strain by breaking one large expense into manageable installments. When it is run poorly—or when the terms are unclear—it can create confusion, unexpected costs, or frustration around refunds, cancellations, and pickup timing. That’s why understanding layaway means understanding both the consumer-facing features and the operational mechanics.
From an industry perspective, layaway programs are a merchandising tool that helps suppliers manage inventory risk and customer commitment. When a shopper initiates layaway, the supplier generally reserves the item and records the customer’s obligation to complete the schedule. The supplier’s internal process may include inventory tagging, documented authorization, and a release rule tied to payment milestones.
Unlike revolving credit, layaway is usually not a credit line that continues indefinitely. Instead, it is oriented around completing a defined purchase. That structure is part of why many customers view layaway as a “plan-based” approach: you are not just receiving an invoice—you’re participating in a step-by-step reservation process.
In many retail environments, layaway involves the following operational steps behind the scenes:
Because these steps are procedural, customers benefit from thinking ahead about the parts of the process that require action—such as bringing required identification, paying through acceptable methods, or submitting documentation for refunds if issues arise.
People often consider layaway when they want to spread payments without using a credit product. However, the decision should be grounded in the total cost and the operational friction of the plan.
It helps to remember that layaway changes timing: you pay over time, but the retailer is holding an asset you’re not yet taking home. Because inventory can sometimes be damaged, restocked, re-priced, or re-allocated, a legitimate layaway program usually includes clear rules about what happens if something changes.
When evaluating a layaway offer, consider the following practical factors:
These factors matter because layaway is an agreement with operational and contractual consequences. A well-run program should be transparent about terms before the customer confirms the reservation. If the retailer cannot or will not explain the terms clearly, that is a signal you should pause and ask for written details.
Another key evaluation point is your personal tolerance for schedule risk. Layaway can be effective for shoppers with stable income and predictable expenses, because the plan relies on consistent payment behavior. If your income is variable (for example, commissions, tips, or seasonal work), you may find a layaway schedule harder to maintain—even if the installment amount seems small at first.
An industry expert typically views layaway as balancing two goals: customer accessibility and inventory protection. Suppliers must ensure that reserved items do not sit indefinitely while warehouse space, display commitments, and staffing time carry real costs.
Therefore, legitimate layaway programs often include controls such as:
When these controls are communicated effectively, customers can make informed decisions and suppliers can process agreements consistently. From a consumer perspective, that communication is not merely “nice to have.” It is essential for reducing the chance of misinterpretation—especially around fees, cancellation, and the exact point at which the customer’s purchase is considered complete.
On the supply side, layaway programs also have to consider:
These supply-side concerns translate directly into consumer outcomes. For example, a substitution rule affects whether you can still get the same product you initially selected. A repricing rule affects whether your total cost changes over time. Clear terms reduce uncertainty for both parties.
Before starting a layaway plan, treat it like any other purchase agreement. Ask questions that connect terms to your actual circumstances:
Good supplier practices typically include clear written confirmation, not only a verbal explanation. If an offer is presented with ambiguity—especially around fees or cancellation—ask for a document, receipt, or written policy summary. If the store cannot provide any written detail, consider whether you want to assume that risk.
It can also be helpful to consider your timeline before enrolling. Layaway is most predictable when the payment period lines up with your pay schedule and when you know you will still be able to visit the store by appointment windows and deadlines.
Layaway pricing should be assessed in two layers:
If the supplier provides a total “amount due” figure for the layaway, you still should request the component details—especially if the plan includes service charges. That approach helps you understand the true affordability of layaway rather than relying on the merchandise price alone.
In many real shopping scenarios, the difference between the sticker price and the total amount due can come from:
Another pricing nuance is how the retailer handles taxes. Depending on local rules and store practice, taxes may be calculated at the time of purchase reservation, at the time of final payment, or as part of the total amount due. If taxes are unclear, you should ask: “Is sales tax included in the total amount due?” and “Will tax amounts change if the item price changes?”
Pricing clarity is also important when comparing layaway to other options. For example, a store may advertise a low installment amount, but if the administrative fee is large or if the refund is limited, the true cost may be less favorable than it appears.
Even when payments are on track, the customer journey continues into pickup. Ask about:
By understanding these steps early, customers can reduce the chance of a dispute or an unexpected financial outcome. For example, a store may release the item to pickup only after the final payment posts and the system updates. If you assume pickup is immediate on payment day, you may experience delays.
Item change rules are another operational area that matters. Many layaway buyers start with a specific version—such as a particular model number or a color variant. Over time, stock levels can change, and retailers can become unable to fulfill the original selection. A fair substitution policy typically provides options or offers replacements of comparable value, but the exact terms determine whether you get what you expected.
Questions you can ask include:
Finally, consider return eligibility. Even if a layaway plan is completed properly, returns and refunds after pickup may be restricted by the store’s standard policy. Some stores may treat layaway as a special transaction and may require a receipt, specific packaging, or a return within a short window. Knowing the return process in advance helps you avoid uncertainty later.
The rules governing layaway vary by region and are often influenced by consumer protection frameworks. In many jurisdictions, the key concerns are disclosure and fair handling of customer funds. Reliable suppliers typically align their processes with consumer finance expectations such as clear fee communication and documented payment status.
To keep this guide objective, it avoids speculation about specific regulatory outcomes in any one location. Instead, it emphasizes the universal top practice: read the written agreement, confirm fee treatment, and understand the consequences of nonpayment.
From a consumer standpoint, legal and regulatory context usually shows up in the following ways:
Even if rules differ across regions, the consumer lesson remains consistent: conditions matter. A layaway plan is not simply “a way to pay.” It is a contract with consequences, and those consequences are shaped by local consumer protection policies and by the retailer’s own compliance practices.
| Condition / Requirement | What to Expect in a Typical Layaway Setup | Why It Matters for Total Risk |
|---|---|---|
| Payment schedule | Defined installment frequency (e.g., weekly or monthly) with specific due dates | Determines whether you can consistently meet obligations without triggering cancellation |
| Upfront deposit (if any) | May include an initial payment to begin reservation | Impacts how much of your money is at risk if the plan fails |
| Administrative fees | Some plans include processing or service charges | Changes the true cost beyond the merchandise price |
| Late payment policy | Often specifies grace periods, late fees, or payment interruption rules | Late fees or interruptions can quickly increase cost and uncertainty |
| Cancellation and refund terms | Defines refund eligibility and timelines; some portions may be nonrefundable | Sets expectations about how quickly funds can return to you |
| Inventory hold length | Includes a layaway completion deadline | Prevents indefinite reservation and clarifies the time commitment |
| Item release conditions | Usually requires full payment and identification for pickup | Reduces the chance of disputes around “completion” status |
| Change-of-mind rules | Specifies whether you can change items or request partial adjustments | Determines flexibility if your needs change mid-plan |
Below is a structured approach aligned with common retail layaway workflows. While suppliers may differ in details, these steps reflect how agreements are typically managed:
Because layaway is a multi-step agreement, responsible use often includes building “buffer behavior” into your plan. For example, if payments are due on a certain date but you sometimes run late due to work scheduling, you can reduce risk by paying a day or two early (if allowed). If paying in store requires travel time, you can plan ahead so you’re not rushing on the deadline.
Another practical step is to check whether the store allows online verification or whether you must check in person. Some retailers provide a layaway status lookup; others require customer service contact. Knowing how to confirm your balance can prevent unpleasant surprises.
If you ever need to pause a plan—due to unexpected expenses—ask what options exist. Some stores may allow you to adjust dates or restructure payments; others may not. Asking early can be the difference between a manageable solution and a cancellation triggered by a missed payment.
Even with a straightforward layaway agreement, customers can run into preventable issues:
Below are additional mistakes that come up frequently:
To reduce these risks, create a simple system: keep your layaway paperwork in one place, record payment dates, and note any changes the store agrees to. Even a basic spreadsheet or a folder can prevent confusion.
Layaway sits within a broader consumer payment landscape that includes credit cards, installment loans, and “pay over time” models. Objective comparisons should focus on how consumers manage repayment and how suppliers disclose terms.
When discussing consumer finance behavior, it is important to rely on established sources. For general context on consumer financial stress and household budgeting, widely cited frameworks come from official or reputable institutions such as the U.S. Federal Reserve Board’s consumer studies and the Consumer Financial Protection Bureau (CFPB). For credit and payment practices, the Federal Trade Commission (FTC) provides guidance on consumer rights and financial product terms. These sources can help consumers understand the importance of clear disclosure and payment responsibility—principles that also apply to layaway programs.
While layaway is not always categorized the same way as revolving credit, the consumer-behavior lesson is still relevant: a plan is only affordable if the payment behavior matches real life. Many families plan budgets around recurring bills; layaway introduces a new recurring commitment. For some shoppers, that commitment can improve discipline because it restricts spending outside of the plan. For others, it can be an additional financial burden if the payment schedule collides with other expenses.
Consumers often compare layaway to “buy now, pay later” (BNPL) arrangements. Even if both involve installment payments, they can differ in critical ways:
Because these differences matter, consumers should avoid assuming that “pay over time” automatically means “similar risk.” The terms determine the actual risk, and the customer’s ability to make consistent payments determines whether the experience remains predictable.
No. Layaway typically reserves an item while you pay in installments, then releases the item after completing the required payments. Credit cards involve borrowing and revolving balances under separate terms.
Some suppliers charge administrative or service fees to process and manage the reservation. Others may require a deposit. The specific fee structure depends entirely on the supplier and the written agreement.
Often it’s possible, but the refund is subject to the cancellation policy. Many agreements specify timelines and whether certain portions—such as fees or deposits—are nonrefundable.
Policies vary. Some suppliers offer a grace period; others may charge a late fee, pause the plan, or cancel the layaway after a set number of missed or late payments. Check the written terms before enrolling.
It depends on the supplier. Some plans lock the price at reservation; others may adjust if the item is repriced. The written agreement is the authoritative source.
Typically, pickup is allowed once you complete all required payments and meet the supplier’s release conditions. Confirm the pickup window and required documentation.
No. Different suppliers can have different schedules, deadlines, fees, and cancellation rules. Objective comparison requires reading the agreement carefully.
Some layaway programs allow you to pay early or pay extra to reduce the duration of the plan; others require payments to follow the agreed schedule. Ask the retailer whether early payoff changes the pickup date or whether it affects any fees.
Keep your receipt or payment confirmation, then contact the store promptly with your layaway number and proof. Request verification of the payment posting. If the discrepancy is not resolved, ask for the policy for dispute resolution or escalations.
In some situations, a store may transfer accounts or apply a new process. However, the exact handling depends on the retailer’s policies and the written agreement you signed. This is why it’s valuable to keep documentation and to ask the store how it handles operational changes.
Layaway can be a practical option for shoppers who want a structured path to purchase without paying the full amount immediately. The very important takeaway is not the concept alone—it’s the contract details: total cost, payment schedule, fees, cancellation terms, and pickup conditions. When these elements are confirmed upfront, layaway becomes less of a guess and more of a predictable plan.
If you’re considering a layaway arrangement, approach it with the same discipline you’d use for any financial agreement: ask for written terms, verify the full cost, track your payments, and plan for pickup on time.
To make the experience as smooth as possible, keep your focus on the controllable actions: understand the schedule before committing, confirm the exact item and identification requirements, maintain proof of payments, and stay aware of deadlines. When you do, layaway can function as intended—not just as a way to postpone payment, but as a step-by-step plan that helps you purchase thoughtfully within your budget.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Understanding Digio Livelo Benefits and Partner Options
This guide explains how Digio Livelo works, what to check before using it, and how partner offers are typically structured across the ecosystem. Objectively, “Digio” is a financial services brand and “Livelo” is a points-and-rewards program in Brazil; together, these commonly function as a way to earn and redeem rewards through eligible purchases and promotions.
Digio Livelo: How Rewards and Payments Work
This guide explains how Digio Livelo connects everyday spending to rewards and how customers can use it with confidence. Background research covers what Livelo is, why partner ecosystems matter for consumer rewards, and how card-based or account-based offers are typically structured—without hype. Practical considerations and conditions are included later for clarity.
Digio Livelo Guide: How It Works and What to Check
This guide explains Digio Livelo’s mechanics, from eligibility and redemption logic to practical evaluation points before you choose. Background context outlines what Digio and Livelo generally represent in reward ecosystems, the role of suppliers, and why careful comparison matters. The article remains objective, focusing on real-world decision criteria rather than promises.
57587795987: A Practical Procurement & Sourcing Guide
57587795987 is very useful as a reference point for procurement workflows—helping buyers verify supply details, manage lead times, and reduce mismatch risk. This guide explains what such identifiers typically represent in sourcing contexts, how to evaluate suppliers using objective criteria, and how to structure requirements before contacting vendors for quotes and delivery terms.
A Practical Guide to 57587795987 Procurement
This guide explains how to evaluate supplier options and pricing while referencing the product identifier 57587795987. It provides objective background on how identifiers, purchasing workflows, and supplier verification typically work, helping readers compare risk, delivery readiness, and documentation quality without relying on unverifiable claims.
Selecting Reliable Suppliers for K Industrial Components
This guide explains how to choose reliable suppliers for K industrial components, focusing on specification fit, quality assurance, and procurement planning. It reviews what “K” often represents in supplier catalogs, the typical documentation buyers should request, and how pricing models are evaluated using objective criteria from industry practice.
