This guide explains how Layaway works, what to verify before enrolling, and how to compare terms so shoppers avoid common pitfalls. Layaway is an installment-based purchase arrangement where an item is reserved while payments are made. Background topics cover eligibility, contract terms, payment schedules, and transfer/cancellation policies, with an objective lens on consumer protections.
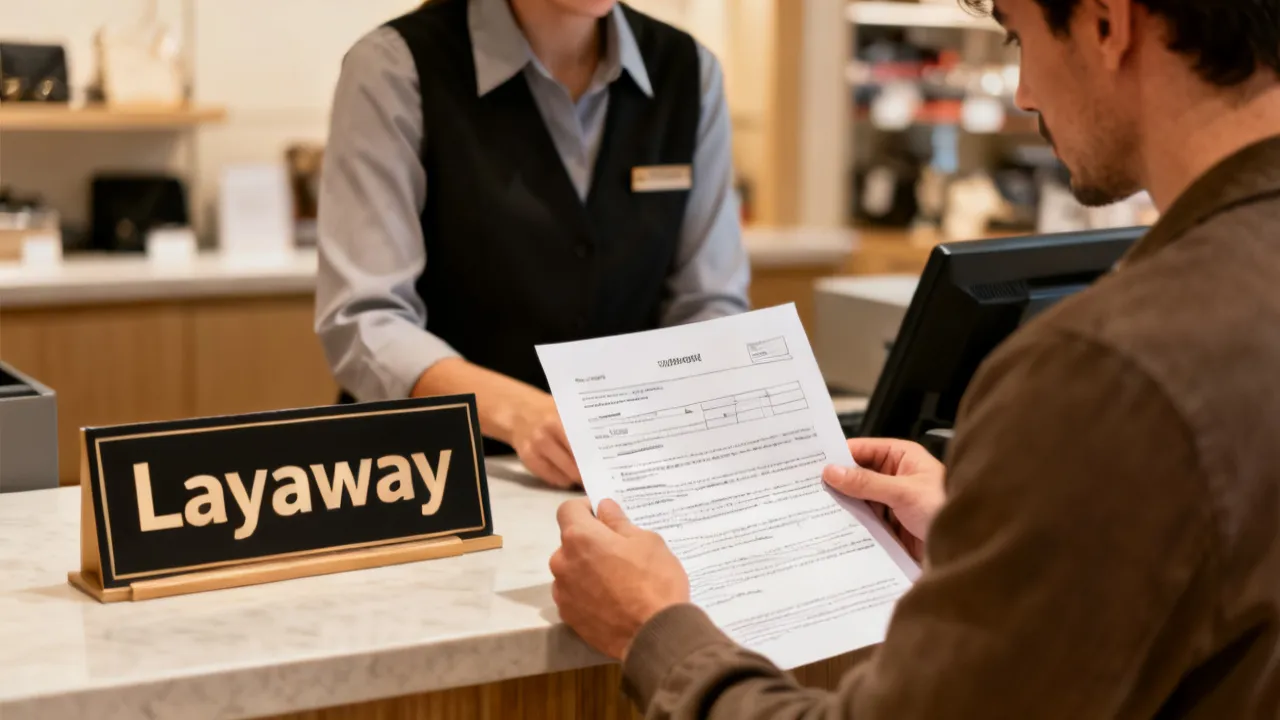
Layaway is a purchasing arrangement designed to help households plan for a future purchase by reserving an item while you make scheduled payments. In practice, the store typically takes custody of the item (or places it on reserve), and you pay in installments until the full price is reached—often before the item is released to you. Because the experience varies by supplier, the very important step is to review the contract details: the payment schedule, service fees, cancellation/return rules, and what happens to your reservation if you miss a payment.
From an industry-expert perspective, the value of Layaway is not merely “spreading costs,” but also the governance around risk allocation. Retailers use structured terms to manage inventory hold, administrative handling, and consumer default. Shoppers should therefore treat Layaway like a contract, not a casual payment plan—because the contract defines what you receive at the end, what you may lose along the way, and what protections (if any) exist when life changes.
Layaway plans tend to appeal to shoppers who want a deliberate path to ownership—often when timing matters more than immediate convenience. For example, customers may use Layaway for seasonal items, big-ticket essentials, or planned gifts. In many cases, the psychological benefit is that the item remains reserved while the shopper follows a defined payment cadence rather than relying on revolving credit.
However, it’s equally important to recognize that Layaway does not automatically eliminate total cost. Some agreements include non-refundable fees (such as reservation charges or handling fees). Those costs can matter as much as the sticker price, especially if you end up needing to cancel or change items. Layaway can also shift the “cost” from money to flexibility: you may be able to pay smaller amounts, but you lose the freedom to make last-minute substitutions without consequences.
Another reason people choose Layaway is to avoid interest charges that may apply with credit cards or installment loans. Layaway is often perceived as “interest-free,” but that perception can be misleading if the true cost is embedded in fees, service charges, price markups, or penalties for non-completion. The best way to evaluate Layaway is to think like a contract reviewer: focus on the full amount due at completion and the downside if you stop paying.
While individual suppliers differ, very Layaway arrangements share a similar structure:
As an expert in retail operations and consumer transaction design, I’d summarize the guiding principle this way: Layaway creates a temporary allocation of inventory risk between the retailer and the customer. Retailers want predictable payment behavior; customers need predictable outcomes. The contract terms are where those expectations are formalized. In practice, that means you are not just buying later—you are agreeing to a set of conditions under which the retailer holds inventory and under which you commit to consistent payments.
It also means the layaway account is a live, trackable relationship. Many disputes arise not because layaway “failed” as a concept, but because customers did not realize that the account balance, payment posting time, or compliance with the due dates determined whether the reservation remained active.
Before enrolling, you should verify specific terms that directly affect cost, timing, and your ability to pivot if plans change. The very critical items to check include:
These checks help you avoid misunderstandings that often occur when the shopper assumes Layaway functions like a simple deposit. In reality, many agreements specify that part of your payments compensates for inventory handling and time-based reservation risk. Even if the store is polite and responsive, you still want objective written clarity because store policies can vary by manager or by location.
In a practical sense, you should also ask whether the store will provide a running balance statement. If not, request at least a receipt for each payment and confirm that the receipt includes the layaway account identifier. That simple step prevents many problems like “the store didn’t receive my payment” or “the payment was applied to the wrong account.”
Even without “interest” being explicitly stated, Layaway can change the total outlay through fees. To evaluate whether Layaway is financially sensible for your situation, compare:
An industry lens emphasizes that affordability should not be measured solely by monthly payment size. Instead, evaluate “cost to completion” and the probability that you can reach completion without interruption. This is where budgeting discipline matters: if you choose a payment schedule that you can maintain, Layaway becomes a predictable path. If you choose a schedule you cannot maintain, the arrangement may turn into a partial loss plus administrative hassle.
To make the comparison concrete, consider two shoppers buying the same item. Shopper A pays in full and takes the item immediately. Shopper B uses Layaway with a small reservation fee and modest service charges. If Shopper B successfully completes the plan, Shopper B may effectively spend a bit more due to fees, but they avoid credit charges. If Shopper B cancels midstream, Shopper B may lose some portion of the payments—especially the non-refundable portion—making the effective “price” of Layaway far worse than it looked.
So the question is not only “What do I pay each month?” It’s “What is the total cost if things go right, and what happens if they go wrong?”
Different suppliers manage Layaway differently based on merchandise type, inventory turnover, and operational complexity. For instance, durable goods with long storage requirements might have stricter policies than items with quick restocking cycles. Retailers may also apply internal controls—such as verifying identity, limiting the number of active reservations per customer, or requiring a minimum initial payment.
To make your experience smoother, communicate clearly with the supplier. Ask how payments are posted, what you should do if a due date falls on a weekend/holiday, and whether you can make payments ahead of schedule. Many operations teams will accept earlier payments and update the account balance immediately, but some systems only post payments during certain processing windows. Knowing the posting timing helps you avoid “technically late” situations.
Additionally, ask about inventory handling. Some retailers may keep the item in a back room labeled with a reservation code; others may use a system reservation that does not physically separate the item until certain thresholds are met. While your contract should protect you either way, the practical reality of inventory handling can affect substitution likelihood if inventory availability changes.
If you’re laying away multiple items (or a bundled set), ask whether each item has its own reservation status. Sometimes a bundled purchase may be treated as one plan with shared completion requirements, which can affect whether partial completion triggers partial pickup or separate refunds.
Layaway can be a practical tool, but certain pitfalls show up repeatedly:
Practical prevention strategy: request the terms in writing and keep receipts. If the supplier provides an installment ledger, confirm that the balance and remaining number of payments align with what you expect. A useful habit is to record the amount paid, the date, and the receipt number in a simple personal tracker (paper or digital). This helps you reconcile the store’s system if there’s ever a discrepancy.
Another common pitfall is assuming that every payment counts exactly the same way toward completion. For instance, some plans treat certain fees as “service charges” that do not reduce the completion threshold, while other plans apply all payments proportionally. The contract should clarify, but if not, ask directly: “Does my payment reduce the remaining amount to complete 1:1, or are there fees that don’t reduce the completion balance?”
Finally, be careful with promotional pricing. If the store advertises a discount available only if you buy immediately, ask whether the promotional price carries over to layaway completion or whether the plan reverts to standard pricing. Promotions may have specific eligibility requirements, and the terms can be strict.
It’s useful to situate Layaway among common alternatives: paying in full, using a savings plan, credit-based financing, or store-specific installment arrangements. While specifics vary by jurisdiction and supplier, the broad trade-offs are generally:
From a consumer-protection standpoint, the “top” option depends on your predictability of income and your tolerance for contract-defined forfeiture if circumstances change. If your household income is steady and your budget is consistent, Layaway can be a disciplined alternative to credit. If your income is irregular or you anticipate possible job disruption, you might be better off saving with a plan you can pause without losing money to fees—unless the Layaway contract provides favorable cancellation terms.
It can also help to evaluate “timing value.” If an item is needed by a certain date—like school start dates or a seasonal event—Layaway can solve timing constraints without triggering credit. But because layaway release is contingent on completion, you should confirm the timeline from the day you enroll to the day you’ll be able to pick up the item.
Consider also the “administrative friction” dimension. Saving might be simple: you deposit money and withdraw later. Layaway involves active management of payments and recordkeeping. If you prefer low administrative overhead, you may find Layaway harder than saving—even if Layaway payments are smaller.
Below is a practical approach designed to reduce uncertainty and administrative friction. Use it whether you are choosing a store-based supplier or a kiosk-based reservation process.
One small but powerful practice: bring the layaway receipt or reservation number to each payment visit. This prevents misapplication and speeds up service. It also helps you demonstrate that you are an active participant in the plan, not a shopper who forgot the process.
Additionally, if you pay by cash, ask whether change is exact and whether there is any process for overpayments. If you pay by card, confirm whether the store will charge different processing fees on different payment methods. These details are usually in the contract or store policy, but asking up front can prevent friction later.
Layaway agreements frequently include conditions intended to protect both parties. While you should always review the specific contract you receive, these are typical requirements:
Another condition that sometimes appears relates to item condition. For example, if the item is a pre-owned good (less common in layaway but possible in some markets), the contract might detail cosmetic wear expectations or warranty handling. Even for new items, the contract could describe how defective goods are handled once the item is released to you.
Also pay attention to how the plan handles sales tax and shipping. Some plans include tax upfront in the layaway amount, while others add it at release. If you want to budget accurately, ask how tax is treated.
| Term/Area | What to Ask | Why It Matters |
|---|---|---|
| Total cost | “What is the full amount paid to complete Layaway, including any fees?” | Fees can change the true cost versus the shelf price. |
| Fees | “Which fees are non-refundable if I cancel?” | Prevents unpleasant surprises at cancellation time. |
| Payment schedule | “How often are payments due, and what happens if I pay late?” | Defines whether missing a due date triggers default. |
| Cancellation/refunds | “If I cancel, how much is refunded and when?” | Determines your downside risk if circumstances change. |
| Item availability | “If the item is unavailable, can it be substituted and at what price?” | Prevents a “bait-and-switch” outcome caused by inventory changes. |
| Release/pickup | “When will I be able to pick up the item after final payment?” | Affects your timeline for using the purchase. |
| Documentation | “Will I receive a contract or reservation number?” | Supports accurate account tracking and dispute resolution. |
| Tax/shipping handling | “Is tax included now or calculated at release? What about delivery/shipping costs?” | Ensures your budget matches the final amount you’ll actually pay. |
| Rescheduling options | “If I need to change a due date, is there an option to extend or reschedule?” | Helps you handle real-life emergencies without immediate forfeiture. |
Layaway sits at the intersection of retail inventory management and consumer finance behavior. Retailers offer it as a structured alternative to immediate purchase, but the arrangement inherently changes who bears the risk if a customer cannot complete payments. That’s why consumer protections—typically rooted in contract disclosure and fair handling of refunds—matter.
To ground this discussion in objective context, note that consumer financial education and disclosure principles are widely emphasized by regulators and consumer agencies. In the United States, for example, the Federal Trade Commission highlights the importance of clear disclosures and truthful advertising. While Layaway terms vary by supplier, the underlying expectation is that consumers should receive accurate information about fees, obligations, and outcomes. For general guidance, see the FTC’s consumer education materials and pages on understanding contracts and billing practices.
In other jurisdictions, consumer rights may be supported by local laws governing prepayments, contract cancellation, or unfair contract terms. Because these rules vary widely, always rely on the agreement provided by your specific supplier and consult local consumer-protection resources when needed. The practical takeaway is that even when laws exist, your best protection is still careful documentation and early clarification of ambiguous terms.
Operationally, retailers are balancing storage constraints, administrative costs, and demand variability. If a store holds inventory physically for many weeks, it incurs storage costs and must manage space and tracking. If the item is expensive or fragile, they may impose stricter conditions. If the item has high theft risk, they may add requirements for pickup verification or require immediate pickup after completion.
These realities affect what you experience as a consumer. The more complex the item’s handling, the more likely it is that the contract includes tighter rules around pickup, substitution, and cancellations.
Most shoppers receive the layaway terms as a printed document or as part of a receipt packet. Even if you’re in a rush, you can still review the contract effectively by focusing on a few high-impact sections. Think of it as a “three-lens” review: cost, risk, and procedure.
1) Cost lens: Find the total cost to complete, including any fees. Then look for whether fees are non-refundable and whether the tax is included. Some agreements show monthly payment amounts but hide the true completion total in small-print fee sections.
2) Risk lens: Look for consequences of non-completion. Pay special attention to the definition of default: is it “missed payment by X days,” “two consecutive missed payments,” or “any late payment”? Also check cancellation rules: are you allowed to cancel early, and is any portion refundable?
3) Procedure lens: Find rules that affect how you actually execute the plan. Examples include where you can make payments, which payment types are accepted, whether there is an online account portal, and when the item becomes eligible for pickup.
If the contract includes a “notice” requirement—such as you must notify the store in writing to cancel—treat that seriously. In many real-world situations, “I told them verbally” is not the same as meeting the contract’s required procedure. When in doubt, ask how to submit written notice (email, in-store form, customer service line) and whether you will receive confirmation.
Not always. A deposit may simply reserve an item for a short period. Layaway usually involves installment payments over a defined schedule, with the contract spelling out what happens at completion and what happens if payments are missed or the plan is canceled.
Many agreements include a reservation or service fee and may charge additional fees for changes, late payments, or cancellation. The exact fee structure depends on the supplier and the contract terms you receive. Pay attention to what the fee is compensating for (handling, storage, administration) and whether it is refundable.
Often yes, but cancellation policies vary. Some suppliers refund a portion of payments; others deduct non-refundable fees or apply different treatment to the reservation/service charges. Always confirm the refund calculation before you enroll, and ask how quickly refunds are issued.
Very suppliers define a grace period or specify consequences for missed payments (such as suspension of the reservation, cancellation, or forfeiture). The contract should describe whether you can catch up and whether missed payments accumulate consequences.
It can. Some supplier agreements charge the item price plus fees, while others may keep fees minimal. Ask for the full “amount to complete” and compare against any current promotions. Also ask whether the price is locked at the time of layaway enrollment or can change if the item’s shelf price changes.
Frequently, yes. Qualifying items may exclude clearance inventory, certain brands, or items with limited availability. Supplier rules can also vary by store department or product category.
Possibly, but substitution terms depend on inventory and contract rules. Ask whether substitutions are allowed, whether the new item’s price changes the balance, and whether fees apply. If the substitute is more expensive, you should confirm how the additional amount is handled.
Typically after you complete all required payments and the supplier processes release. Some suppliers require immediate pickup; others schedule it within a specific processing window. Confirm the timeline in writing, including whether pickup appointment scheduling is required.
Availability depends on the supplier and local market practices. Some retailers offer it in-store, online through reservation systems, or only for specific product lines. Even if a store offers layaway in general, availability may depend on item type.
Keep the Layaway contract (or written terms), proof of each payment, and any reservation number or confirmation receipt. Documentation is important if there’s ever a discrepancy in the account balance or release status. Also consider keeping a copy of your original payment schedule or receipt packet so you can compare what was promised versus what appears on the account.
To make Layaway operationally painless, adopt a simple discipline: treat each installment as a scheduled obligation and maintain clear records. When people run into trouble, it’s often not because the concept is flawed, but because terms were assumed rather than verified—especially around cancellation, missed payments, and fee treatment.
From an expert standpoint, you can also reduce risk by setting a realistic completion horizon. Choose a payment cadence you can sustain. If your budget is tight, consider whether a smaller item or a longer plan duration reduces the chance of default—then verify how the supplier’s timeline interacts with fees and default rules.
Another practical recommendation is to plan for communication. If you foresee difficulty making a payment, don’t wait until the contract has already triggered default. Ask what options exist while you still have time. Some retailers may offer a brief extension, allow a one-time reschedule, or convert the plan into a different arrangement. Even when official policies prohibit changes, a proactive customer often gets the best available help.
It’s also wise to check whether the store offers a customer service number or an online account portal for layaway balances. Access to your account status reduces the risk of surprises. If the store provides a phone number, ask whether representatives can confirm the balance and whether verification requires the reservation number.
Finally, prepare for the final pickup stage. Many shoppers focus on paying and then assume the item will be ready automatically. But some suppliers require that you pick up the item within a specified window after completion. If you miss that window, you might face additional fees or other consequences. Plan your pickup as carefully as you planned your payments.
Layaway is easiest to manage when you anticipate real-world situations. Below are common scenarios and practical responses grounded in how layaway contracts typically operate.
Scenario A: Your income changes mid-plan. If you experience reduced hours, delayed pay, or unexpected expenses, contact the supplier immediately. Ask whether you can reschedule payments, extend the plan length, or switch items. If none of those are permitted, ask exactly how cancellation would work and what portion of your payments would be refunded. This turns an emotional decision into a calculated one.
Scenario B: The item is discontinued or no longer available. Ask whether substitution is allowed and whether you will be charged any additional difference. If substitution is not allowed, the supplier’s obligation to refund (or re-reserve a similar item) should be addressed in the contract. Ensure you get any resolution in writing or via a documented confirmation receipt.
Scenario C: A payment is delayed or misapplied. Sometimes a payment is made on time but posted late due to processing delays. Or a payment is applied to the wrong reservation. If you have proof (receipt number or digital confirmation), present it promptly. Request a written statement or manager confirmation that the payment has been properly credited. This can prevent the store from canceling the plan based on a balance that appears incorrect.
Scenario D: You finish payments but cannot pick up right away. Ask whether there is a grace period after completion. Some retailers may hold the item for a certain number of days; others may require immediate pickup. If you anticipate a delay, coordinate ahead of time to avoid penalties.
Scenario E: You want to switch to a different version (size, color, model). Many layaway systems can allow substitution only if the customer meets certain conditions and the new item is eligible for layaway. Ask whether the substitution resets the plan, changes the remaining balance, or introduces new fees. If your preferred item is more expensive, confirm exactly how the difference is paid—before you assume it will be automatically covered.
Layaway can be an effective tool for responsible household budgeting when you approach it as a contract with clear responsibilities and consequences. The top outcomes usually come from two behaviors: (1) verifying the written terms before paying, and (2) managing the payment schedule with discipline and documentation.
If you do those things, Layaway serves its intended purpose—helping you move from reservation to ownership with predictable steps. And if circumstances change, your understanding of cancellation and missed-payment terms will determine whether the experience remains manageable or becomes costly.
Ultimately, the “wisdom” in using layaway lies in matching the plan to your real life. If you can reliably make the scheduled payments, Layaway can help you obtain a desired item without using credit. If your budget is uncertain, you should be more cautious, read cancellation terms more thoroughly, and consider whether saving instead might reduce your downside risk. When you align your choice with your ability to complete it, Layaway becomes a practical pathway rather than a stressful commitment.
For general principles on consumer disclosure and truthful advertising, consult the Federal Trade Commission (FTC) consumer guidance and contract-related educational materials in your jurisdiction. For Layaway-specific enforcement, always rely on the supplier’s written agreement and applicable local consumer-protection regulations, as terms differ widely by retailer and region.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Understanding Digio Livelo Benefits and Partner Options
This guide explains how Digio Livelo works, what to check before using it, and how partner offers are typically structured across the ecosystem. Objectively, “Digio” is a financial services brand and “Livelo” is a points-and-rewards program in Brazil; together, these commonly function as a way to earn and redeem rewards through eligible purchases and promotions.
Digio Livelo: How Rewards and Payments Work
This guide explains how Digio Livelo connects everyday spending to rewards and how customers can use it with confidence. Background research covers what Livelo is, why partner ecosystems matter for consumer rewards, and how card-based or account-based offers are typically structured—without hype. Practical considerations and conditions are included later for clarity.
Digio Livelo Guide: How It Works and What to Check
This guide explains Digio Livelo’s mechanics, from eligibility and redemption logic to practical evaluation points before you choose. Background context outlines what Digio and Livelo generally represent in reward ecosystems, the role of suppliers, and why careful comparison matters. The article remains objective, focusing on real-world decision criteria rather than promises.
57587795987: A Practical Procurement & Sourcing Guide
57587795987 is very useful as a reference point for procurement workflows—helping buyers verify supply details, manage lead times, and reduce mismatch risk. This guide explains what such identifiers typically represent in sourcing contexts, how to evaluate suppliers using objective criteria, and how to structure requirements before contacting vendors for quotes and delivery terms.
A Practical Guide to 57587795987 Procurement
This guide explains how to evaluate supplier options and pricing while referencing the product identifier 57587795987. It provides objective background on how identifiers, purchasing workflows, and supplier verification typically work, helping readers compare risk, delivery readiness, and documentation quality without relying on unverifiable claims.
Selecting Reliable Suppliers for K Industrial Components
This guide explains how to choose reliable suppliers for K industrial components, focusing on specification fit, quality assurance, and procurement planning. It reviews what “K” often represents in supplier catalogs, the typical documentation buyers should request, and how pricing models are evaluated using objective criteria from industry practice.
