Paychex 401(k) Fidelity options can shape how employees save for retirement, so this guide explains how plan administration, investment choices, and account features interact. It then provides objective background on how 401(k) recordkeeping and fiduciary-related responsibilities are structured, helping readers evaluate fit, fees, and operational details before enrolling.
When people search for Paychex 401k Fidelity, they’re usually trying to understand how their employer’s payroll/benefits setup connects to a 401(k) retirement plan experience—particularly recordkeeping, service workflows, and investment access. In practical terms, the “fit” of a 401(k) plan is determined by how contributions flow from payroll, how the account is serviced, and how investment options and plan-level terms are designed. This guide approaches the topic from an objective, industry-informed standpoint so employees and HR teams can compare options with clarity.
Instead of focusing on promises, the more reliable question is: What does the plan actually do for you day-to-day—especially at contribution time, during withdrawals, and when you need customer support?
It can be tempting to treat provider names like they automatically predict outcomes. But in retirement planning, the “outcome” an employee feels is often shaped less by marketing and more by operational design: posting timelines, the accuracy of payroll contribution mapping, how quickly allocations update, whether service requests are frictionless, and what choices exist for building and maintaining a diversified portfolio. When an employer uses Paychex for payroll/benefits administration and pairs that with Fidelity-style 401(k) recordkeeping and participant tools, the combined system can create a smoother experience—or, if configured poorly, a confusing one.
That’s why Paychex 401k Fidelity becomes a meaningful search phrase: it’s shorthand for “How does my paycheck connect to my retirement account?” It’s also shorthand for “Where do I go when something goes wrong?” And in many real-world cases, those practical questions matter as much as (and sometimes more than) the headline investment lineup.
A 401(k) plan is more than an investment lineup. Very employee experience issues trace back to four operational layers:
In many workplaces, the employer’s benefits technology stack—including payroll and administrative partners—helps determine how smoothly those layers operate together. That’s why “Paychex 401k Fidelity” tends to appear in searches: people want to know whether their employer’s arrangement brings the participant experience associated with Fidelity’s recordkeeping and platform capabilities (or similar services), while still using Paychex for payroll administration or benefits management.
To make this more concrete, imagine two employees—both eligible for the same deferral percentage. One sees their contributions appear quickly and consistently after payroll. The other sees late postings, frequent mismatches, or delayed updates after changing their election. Over time, the employee who experiences fewer operational issues is more likely to feel confident, continue contributing, and adjust allocations as needed. Those behaviors compound into meaningful differences in retirement readiness.
At the HR level, those operational layers also influence compliance and administrative workload. When contribution data arrives cleanly from payroll systems and recordkeepers can validate transactions with minimal rework, administrative costs can be lower and participant issues can be resolved faster. When the mapping is inconsistent, time is consumed correcting errors, responding to participant concerns, and reconciling discrepancies.
So when we talk about “Paychex 401k Fidelity,” we’re really talking about system interoperability: does payroll data flow correctly into retirement recordkeeping, and does the participant experience stay coherent across the lifecycle of the account?
Even when investment returns vary over time, the quality of the participant experience can noticeably affect engagement, contribution behavior, and the ability to make timely changes. As an industry analyst would frame it, you can evaluate recordkeeping quality using observable criteria:
These factors are operational and decision-relevant. They influence how quickly participants can adjust to life events—job changes, family needs, or retirement timing—without getting stuck in administrative friction.
To evaluate recordkeeping in a way that doesn’t require deep technical knowledge, it helps to translate each criterion into a participant scenario. Consider common moments where employees interact with their 401(k):
In many employee complaints, the underlying complaint isn’t “the 401(k) performed poorly.” It’s “the 401(k didn’t behave predictably.” Recordkeeping quality directly affects predictability.
Because “Paychex 401k Fidelity” searches often reflect employee frustration or curiosity about operational workflows, it’s especially useful to look for evidence of consistent posting, clear transaction logs, and responsive support channels. If the recordkeeper and payroll integration behave smoothly, it reduces confusion and helps participants maintain appropriate investment choices and contribution levels.
When comparing a 401(k) platform associated with Paychex 401k Fidelity configurations, it’s tempting to focus on brand recognition. However, an expert approach emphasizes that the investment menu you see depends on the employer’s plan design. Two employees at different companies may experience different fund lineups, even if both use similar providers.
Before making assumptions, review the Summary Plan Description (SPD) and the investment lineup documentation. Consider:
From a participant standpoint, the key question is not merely “What funds are offered?” but “How practical is it for me to implement a reasonable, diversified strategy within that lineup?”
This practical question matters because the “best” investment options on paper don’t help if a participant can’t use them easily. For example:
When employees search for provider names like “Fidelity” in connection with “Paychex 401k,” they often expect the investment lineup to be automatically favorable. But investment outcomes come from the combination of (1) what funds are selected by the plan sponsor under governance, (2) how participants allocate their assets, and (3) how the recordkeeping platform enables participation.
Therefore, it’s important to treat the provider name as a clue about the administrative infrastructure—not a guarantee about fund selection or performance. Fund selection is a plan-level decision and should be evaluated on the disclosed menu, associated costs, and whether the plan supports sensible diversification.
Because 401(k) cost details can be presented differently across plans, comparisons should rely on what is actually disclosed in official plan materials. The goal is to avoid confusion caused by mixing mutual fund expense ratios with plan-level administrative charges.
In the U.S., the Department of Labor (DOL) and IRS require disclosures for many retirement plan-related items, and participants can use those materials to understand costs and operations. For background on required disclosures and fiduciary concepts, the DOL provides educational resources (for example, through its ERISA retirement topics and fee-disclosure guidance). You should cross-check your employer’s documentation to determine exactly how costs are applied in your plan.
Practical takeaway: If you see fees, ask whether they appear as fund-level expenses, plan-level administrative charges, or both—then evaluate the total cost structure rather than judging a single line item.
It’s also useful to understand why fee comparisons can be tricky even for educated participants. Two plans can both advertise “low expense ratios,” yet have different revenue sources and fee allocation methods. For example:
Because fees compound over time, clarity here is not just academic. Operational friction that causes delayed contributions or makes participants more likely to keep cash in a default holding option can also affect “outcomes” even if the fee level is reasonable. In other words, cost matters, but so does behavior and timing.
When you compare plans, focus on what you can verify:
That defensible comparison method allows employees to make informed decisions without guessing what’s happening behind the scenes.
People usually encounter payroll-linked 401(k) setups in one of three ways:
If Paychex 401k Fidelity reflects a combined operational workflow between payroll administration and retirement recordkeeping, the “seam” between systems matters. Small delays or reconciliation issues can create participant confusion—such as seeing a mismatch between payroll deductions and account updates.
An expert recommendation is to treat these as process checks: confirm the deferral effective date rules, expected posting times, and how corrections are handled. These details are rarely “headline topics,” yet they drive real day-to-day trust.
To make this clearer, consider how timing can go wrong and how to identify the symptoms:
None of these issues are guaranteed simply because of a provider name. But when employees search for “Paychex 401k Fidelity,” they are often attempting to confirm whether this payroll-to-recordkeeping “seam” is handled well in their particular environment.
From a best-practice standpoint, participants can reduce frustration by knowing what to expect:
These operational expectations can prevent overreaction to temporary delays and help participants recognize whether a pattern suggests a configuration issue that HR should address with the service providers.
The phrase “Fidelity” in Paychex 401k Fidelity searches often refers to a service provider context—commonly recordkeeping and participant services. But it’s important to avoid conflating provider involvement with fiduciary status in a legal sense.
In ERISA-governed retirement plans, fiduciary responsibilities are determined by the specific functions performed. Employers and investment/plan committees may take on different roles depending on plan structure and delegated responsibilities. An objective way to think about governance is to distinguish:
To ground this concept, the U.S. Department of Labor’s ERISA fiduciary education materials explain that fiduciary status depends on function, not job title. Readers should consult their plan’s governance documentation (such as committee charters, if provided, or disclosures within plan materials) for specifics.
It’s worth highlighting that many participants assume that if a well-known recordkeeper like Fidelity administers the account, that implies a fiduciary role in investment selection. In practice, recordkeepers often perform operational administration, while fiduciary responsibilities may remain with the employer sponsor, named fiduciaries, or independent committees depending on how the plan is structured and what duties are delegated.
Why does this matter for employee outcomes? Because governance affects the quality of the investment menu, the fee structure, and the process for monitoring changes over time. A strong governance process doesn’t just reduce compliance risk; it helps ensure that the plan’s investment lineup and costs remain competitive and appropriate.
However, an employee typically doesn’t have full visibility into fiduciary processes. That’s why the participant’s best tools are documentation and disclosures. Even if the legal fiduciary roles are unclear, participants can still evaluate:
So the key is to understand role separation without overreaching. Provider names can tell you something about the administrative system, but governance and fiduciary responsibilities are determined by plan-specific function and documentation.
The following supplement is designed to help you evaluate a Paychex 401k Fidelity-type setup. It does not represent a single universal plan design; instead, it outlines common conditions and practical steps that participants and HR teams should verify in the official plan documentation.
| Evaluation Area | What to Check | Typical Conditions/Requirements | Why It Matters |
|---|---|---|---|
| Enrollment and eligibility | Entry date rules, waiting periods, auto-enrollment (if any), and rehire eligibility | Defined by the plan document and SPD; may vary by employment classification | Determines when contributions begin and when elections become effective |
| Payroll deferral mechanics | When payroll deductions start, posting timeline, catch-up provisions | Timing depends on payroll processing and plan transaction cutoffs | Helps avoid confusion about deduction vs. account credit dates |
| Investment lineup access | Fund list, target-date series availability, trading/reallocation rules | Employer selects the lineup within plan governance constraints | Impacts whether a diversified strategy is practical |
| Fees and disclosures | Expense ratios, administrative charges, and fee disclosure documents | Disclosures follow plan and regulatory requirements; formats vary by provider | Enables defensible comparisons across plans |
| Participant support | Customer service channels, escalation path, distribution processing steps | Service model defined by recordkeeping platform and plan policies | Reduces delays during loans, withdrawals, and corrections |
Use this structured approach to evaluate whether your employer’s Paychex 401k Fidelity arrangement (or similar) is aligned with your needs. The steps below emphasize verification using plan documents and account terms.
To further strengthen your evaluation, consider adding a “test run” mindset. You can’t easily simulate a full retirement distribution, but you can often validate operational clarity by doing smaller, reversible actions (within plan rules), such as:
These checks provide practical evidence of how smooth the system behaves. They can be especially helpful if you’re comparing options across employers or if your HR team is planning a vendor transition.
Before choosing or changing elections, consider these common conditions that often apply to 401(k) administration:
Some of these conditions can affect your actual retirement outcomes in subtle ways:
While these are not typically daily concerns, they become critical when you need the plan to function reliably under real-life time constraints. Therefore, evaluating “conditions and requirements” isn’t just compliance reading; it’s risk management from a participant perspective.
From an industry perspective, “good” recordkeeping and plan design typically has two characteristics: operational clarity and governance discipline.
Operational clarity means participants can reliably track contributions, see transaction history, and understand election effects. It also means administrative corrections are handled with a transparent and documented process.
Governance discipline means the investment lineup, monitoring approach, and fee presentation are managed under the plan’s compliance framework. Even if a provider brand is recognizable, the plan sponsor’s oversight is what sustains good quality—particularly when market conditions change.
If you’re evaluating Paychex 401k Fidelity specifically, treat it as a clue about the service ecosystem—not as proof of an investment outcome. Your top evidence is the plan’s disclosed structure and your own ability to execute elections efficiently.
Operational clarity can be broken down into additional “experience signals,” including:
Governance discipline often shows up indirectly in plan design characteristics such as:
In an employee’s life, “good” ultimately means: when you need to contribute, you can do it. When you need to change your allocation, it works as you expect. When you need a distribution or rollover, the steps are clear and processing timelines are reasonable.
It generally points to a combined arrangement where payroll/benefits administration is handled through Paychex and 401(k) recordkeeping or participant services are provided by Fidelity (or a Fidelity-related platform). Exact responsibilities depend on your employer’s plan agreement and plan documents.
In many cases, Paychex is involved in payroll execution and benefits administration workflows (like eligibility tracking, deferral setup, and data transfer). Fidelity (or a similar recordkeeping platform) is involved in the participant-side experience (like online account access, transaction processing systems, loan and distribution administration). The employee experiences these pieces as one continuous system—even though the components may be operated by different organizations.
No. Investment menus vary by plan sponsor decisions and governance. The recordkeeping platform may be similar, but the available funds, employer contributions, and plan rules can differ widely.
Even if two employers both use the same recordkeeper technology, the employer can select different fund lineups. For example, one plan may feature a robust target-date series and multiple index funds, while another may use a smaller lineup or incorporate different share classes. The participant “interface” might look similar, but the investment content can differ significantly.
Start with the plan’s official fee and disclosure materials. Separate fund-level expense ratios from plan-level administrative charges and look for a total cost view expressed in participant-facing disclosures. Then compare that total cost structure against the investment options available in your plan.
If you’re comparing two employers, consider building a simple “cost context” checklist:
No. Returns are driven primarily by the underlying investments and participant allocation decisions. A recordkeeper’s role is mainly operational—how accounts are serviced, how investments are offered, and how transactions are executed.
Recordkeeping quality can indirectly affect outcomes by influencing participant behavior. For example, easier access to transaction history can encourage timely rebalancing. Clear loan workflows can reduce errors. Faster posting can maintain participant confidence. But the investment returns themselves come from the chosen funds and the market.
This can happen because payroll processing cycles and account posting timelines may have cutoffs or reconciliation periods. Review your plan’s posting and transaction timing disclosures, and ask HR or the participant services team if you see recurring mismatches.
Occasional mismatches may be normal if there is a delay between payroll deduction and recordkeeping posting. However, repeated mismatches could indicate that the payroll remittance schedule and recordkeeper posting timeline aren’t aligned—or that payroll data mappings are encountering exceptions.
Confirm reallocation rules, settlement timing, and any trading restrictions. Also verify that your chosen funds still appear on the current lineup, and consider whether your risk level matches your time horizon.
Additionally, consider whether your plan provides allocation instructions that apply to existing balance only, future contributions only, or both. The difference affects how quickly your new strategy takes effect.
Those rules are in the plan document and SPD, along with any participant guides provided by the recordkeeping platform. Because approval criteria and required steps can be strict, rely on the official plan materials rather than general advice.
Loan and hardship provisions can be sensitive to plan design and timing. For instance, eligibility may require certain employment status or minimum account balances, and the required documentation may vary. Reviewing the official process reduces the chance of delays or rework.
Not necessarily. In ERISA contexts, fiduciary status depends on the functions performed. Recordkeeping providers typically perform administrative services, while investment selection and plan governance involve responsibilities that may fall to the plan sponsor or appointed fiduciaries, depending on the plan’s structure.
Understanding this distinction helps employees avoid over-attributing responsibility. Instead of assuming that “the provider” is guaranteeing investment quality, it encourages focusing on the plan’s disclosed governance approach, investment lineup rationale, and the transparency of fees.
Ask for your SPD, fee disclosure documents (as applicable), enrollment materials, and investment lineup information. If you are considering a distribution, request the distribution processing guide and the required documentation checklist.
If your question is operational (like why an election didn’t apply when you expected), request documentation that describes election timing and effective dates. If your question is cost-related, request the most recent fee disclosure package that includes administrative and investment expenses.
A practical, expert approach is to review when your life circumstances change (marriage, job change, major expenses) and at least annually. The optimal frequency depends on your personal situation and how complex your allocation strategy is.
Reviewing annually isn’t just about performance. It’s about alignment: has your risk tolerance changed? Have you added or changed contributions? Do you still want the same investment approach as your retirement timeline evolves?
For readers seeking objective grounding, the U.S. retirement plan landscape is shaped by ERISA compliance principles and IRS rules. The Department of Labor provides educational resources on ERISA, fiduciary concepts, and participant disclosures—useful for understanding how fiduciary responsibility is defined and why plan-level oversight matters. Additionally, the IRS sets framework rules for contributions, limits, and distributions. While your provider and your employer determine day-to-day experience, these regulatory foundations guide required disclosures and procedural compliance.
Source guidance (general): For foundational policy context on ERISA fiduciary concepts and retirement plan disclosures, refer to the U.S. Department of Labor’s ERISA/retirement education resources. For tax rule framework and contribution/distribution constraints, refer to IRS publications related to qualified retirement plans.
To put it simply: providers and employers implement the plan under a regulatory umbrella. That umbrella doesn’t guarantee that each plan will be equally user-friendly, equally transparent, or equally cost-effective—but it does create disclosure expectations and compliance standards that participants can use to evaluate the plan.
When employees compare provider combinations, they should interpret the results cautiously. A provider’s name may indicate the administrative technology used, but the actual plan’s terms are what drive eligibility, effective dates, and distribution workflows. Those terms are what participants can verify through SPD and plan documentation.
Searching for Paychex 401k Fidelity is a reasonable starting point because it hints at the service ecosystem behind your retirement account. But the very defensible decisions come from what your plan document and disclosures actually say: eligibility timing, payroll posting processes, the investment menu you can realistically use, and the complete fee picture as presented to participants.
If you want a simple next action, it’s this: review your SPD and fee disclosures, then confirm how quickly your contributions and allocation changes appear in your account. Those operational details are often where the biggest participant experience differences show up—long before any discussion of performance.
As you take that next step, remember that your “retirement outcome” isn’t only a function of market returns. It’s also a function of whether your plan allows you to contribute consistently, adjust your strategy when your life changes, avoid avoidable administrative errors, and make distributions or rollovers smoothly when the time comes. Provider integration—often reflected in arrangements like Paychex 401k Fidelity—can support that outcome when it’s implemented with clarity and good governance. Your task is to verify the specific plan rules and operational realities that apply to you.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

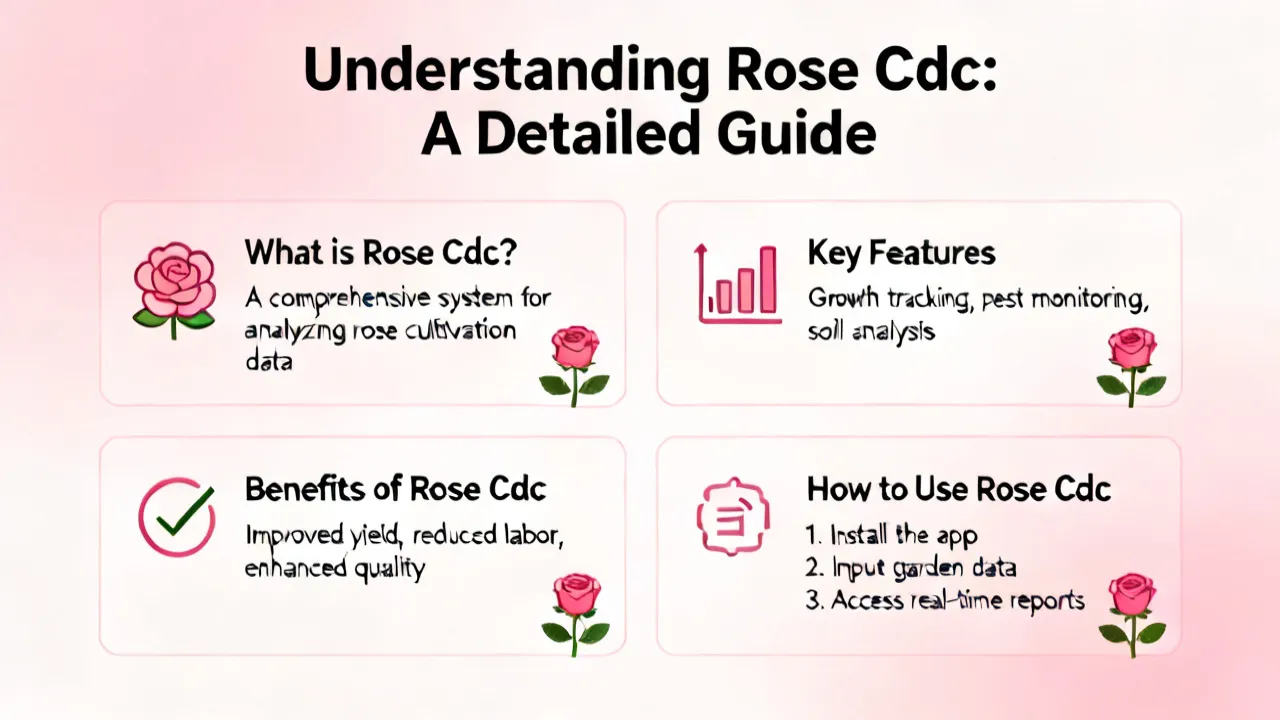
Understanding Rose Cdc: A Comprehensive Guide
This article provides an in-depth exploration of Rose Cdc, a term rapidly gaining attention in specific industries. Our discussion delves into the significance and application of Rose Cdc, its potential impact on various sectors, and expert insights into its future developments. This comprehensive analysis is designed to inform readers about the multifaceted aspects of Rose Cdc, its current applications, and potential advancements.
Understanding Compliance and AML Strategies
This article delves into the intricate realm of Compliance and Anti-Money Laundering (AML) strategies, highlighting their significance in the corporate world. Compliance AML refers to the organizational adherence to legal standards and regulations to deter financial crimes, ensuring transparent and ethical financial practices. This comprehensive guide examines these strategies' complexities and their pivotal role in safeguarding economic integrity.
Mastering Inbound B2B Strategies
The foundation of successful B2B strategies often lies in the effective implementation of inbound marketing techniques. In today's globally connected business environment, inbound B2B strategies have become critical for companies seeking to engage target audiences, optimize lead generation, and establish long-lasting partnerships. Understanding these strategies is essential for companies aiming to thrive in competitive markets.
Exploring B2B MBA Opportunities
Dive into the dynamic world of B2B MBA programs, designed for professionals seeking to enhance their strategic and management skills in a business-to-business context. This comprehensive guide discusses the significance of B2B MBAs in today's market, highlighting how these programs equip leaders with the expertise to navigate complex B2B relationships and drive business success.
Understanding Whitewater Regenerative Blowers
Whitewater Regenerative Blowers are essential in various industrial applications for their efficiency in moving air and gases. These blowers are known for their durability and ability to operate continuously, making them a preferred choice for industries ranging from wastewater treatment to aquaculture. This article explores their features, benefits, and applications, offering readers a comprehensive understanding of their importance in modern industry.
Mastering Employee Retention Strategies
Employee retention has become a critical aspect of organizational success, particularly in the dynamic landscape of 2020. As businesses strive to maintain a stable and productive workforce, understanding effective retention strategies is essential. This article delves into key methods for enhancing employee satisfaction and retention, offering a comprehensive guide for HR professionals and business leaders alike.
